What You Actually Need to Know Before Running the Numbers
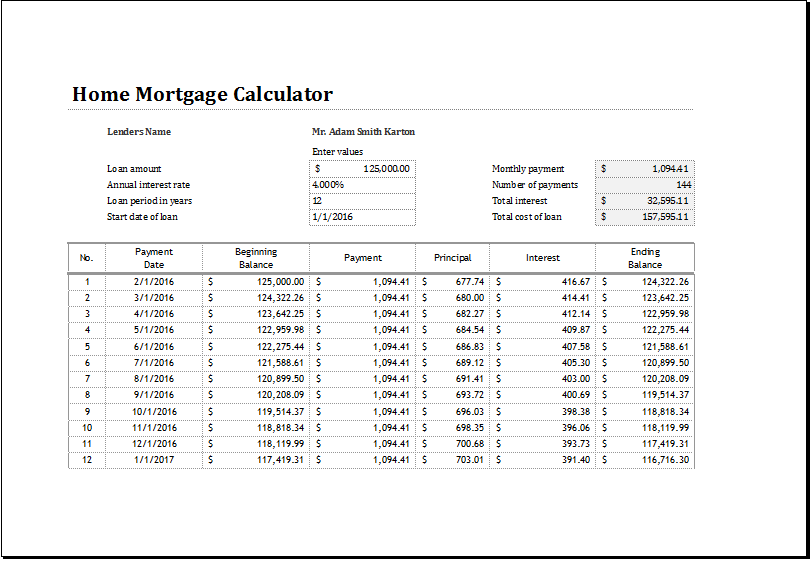
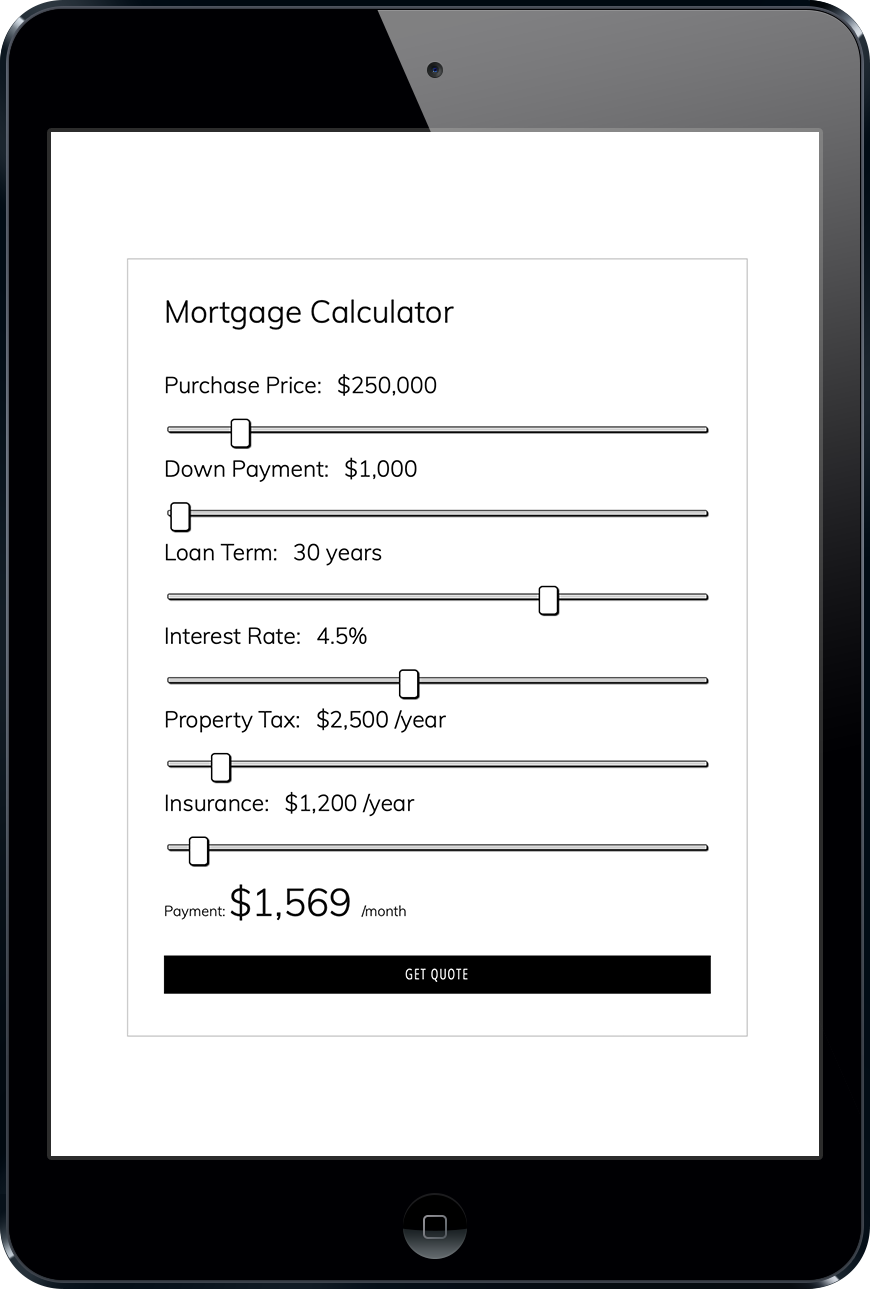
A mobile home mortgage calculator is just a tool that takes your loan amount, interest rate, and term, then spits out a monthly payment. The problem is almost nobody explains what happens when the inputs are wrong or when the calculator's assumptions don't match your actual situation. I've filled out more of these than I care to count across different platforms, and the results can vary by hundreds of dollars depending on which one you use and how you interpret the output. The basic operation is straightforward enough. You enter the purchase price of the mobile home, your down payment percentage, the interest rate offered by your lender, and the loan term. The calculator applies a standard amortization formula and gives you a monthly principal and interest figure. Simple on paper. The edge cases are where things get messy.
Using a Mobile Home Mortgage Calculator Without Wasting Your Time
Start by getting real numbers from actual lenders before you touch any calculator. Interest rates for manufactured homes differ significantly from site-built mortgages. Lenders often classify mobile homes as personal property if the unit isn't permanently affixed to owned land, which pushes rates higher and terms shorter. I once ran a calculation that looked reasonable at first glance, then realized the rate I had entered was for a traditional FHA 203(k) loan while my situation actually fell under the FHA Title I program for manufactured housing. That mistake changed my monthly payment by about $180 and added nearly $4,000 to the total interest over the life of the loan. I had to start over with the correct loan classification before the numbers meant anything. Once you have accurate inputs, most calculators will ask for a few optional fields like property taxes, homeowner's insurance, and PMI. If your mobile home is in a park, you might not owe traditional property tax but instead pay lot rent, which some calculators won't account for. Fill in what you can and flag what you can't. The difference between a partial calculation and no calculation is usually small, but knowing which costs are excluded matters when you're comparing offers. The trick most people miss is that calculators typically show principal and interest only. Your real monthly housing cost includes the land portion whether you own it outright or rent it, plus the insurance premium which tends to be higher for manufactured units, and maintenance reserves that are more frequent than with stick-built homes. A $1,200 monthly payment on the calculator might actually be closer to $1,550 when you layer in lot rent of $400 and insurance around $120.
Why Mobile Home Financing Is Different From What You Expect
Manufactured housing loans operate under separate rules because the collateral depreciates differently. A site-built house generally appreciates over time. A mobile home, unless it's classified as real property through permanent attachment and titled as such, loses value the way a vehicle does. This distinction affects everything from loan-to-value ratios to the types of programs available to you. I learned this the hard way when a calculator I was using showed a comfortable payment on a unit that turned out to be classified as personal property. The lender's appraisal came in below the purchase price because comparable sales for titled personal property were scarce in my area. The calculator had assumed a 95 percent loan-to-value ratio based on standard home purchase assumptions. The actual financing came in at 90 percent with a rate half a point higher. That single classification issue cost me an extra $95 a month and limited my refinancing options later on. Some calculators let you toggle between real property and personal property classifications, but many don't. If yours doesn't, you'll need to adjust the inputs manually to reflect the actual terms you're being offered. There's no automatic correction for a fundamental change in how the loan is structured. The tool can't know your local lender's policies or how your county records the unit.
Get the Full Details
Another nuance that trips people up involves the loan term. Standard site-built mortgages run 15 to 30 years. Personal property loans for manufactured housing often max out at 20 years, sometimes less. When you run a 30-year calculation on a loan that's actually capped at 20 years, your payment estimate will be misleadingly low. I've seen this error repeated across multiple calculator platforms, probably because the developers treat all housing types the same under the hood.
Where These Calculators Fall Short and What to Do Instead
Most online mobile home mortgage calculators share the same fundamental limitation: they're built on generic amortization engines. They don't account for the quirks of manufactured housing financing like the fact that HUD-tagged units may qualify for different programs, or that newer construction can sometimes be financed more cheaply than older models. They also rarely factor in the additional costs unique to this space, such as skirting, foundation work, or the tie-down requirements that some insurers demand. When the calculator gives you a number, verify it against an actual loan estimate from a lender who specializes in manufactured housing. Standard mortgage lenders often don't handle these loans well, and the ones that do may have proprietary calculations that differ from free online tools. The gap is usually small, but it can widen quickly if you're comparing multiple offers or if your situation involves something like a co-op lot lease instead of owned land. If you're near the edges of qualification, the calculator's output won't save you. Income verification, debt-to-income ratios, and credit score thresholds operate independently of whatever payment estimate you see on screen. A monthly payment that looks affordable on the calculator could still disqualify you if your other debts push your DTI over the lender's limit. I once had a client who was thrilled about a low calculated payment until his debt-to-income ratio disqualified him from the best rate, forcing him into a higher-priced loan that erased the apparent savings within a month.
The most practical approach is to use the calculator as a rough screening tool, not a decision-making instrument. Run several scenarios with different down payment amounts and rate points to get a sense of the range. Then take those numbers to a lender and ask them to walk through the actual terms with you. The conversation will be faster and more useful than any adjustment you can make to an online form.