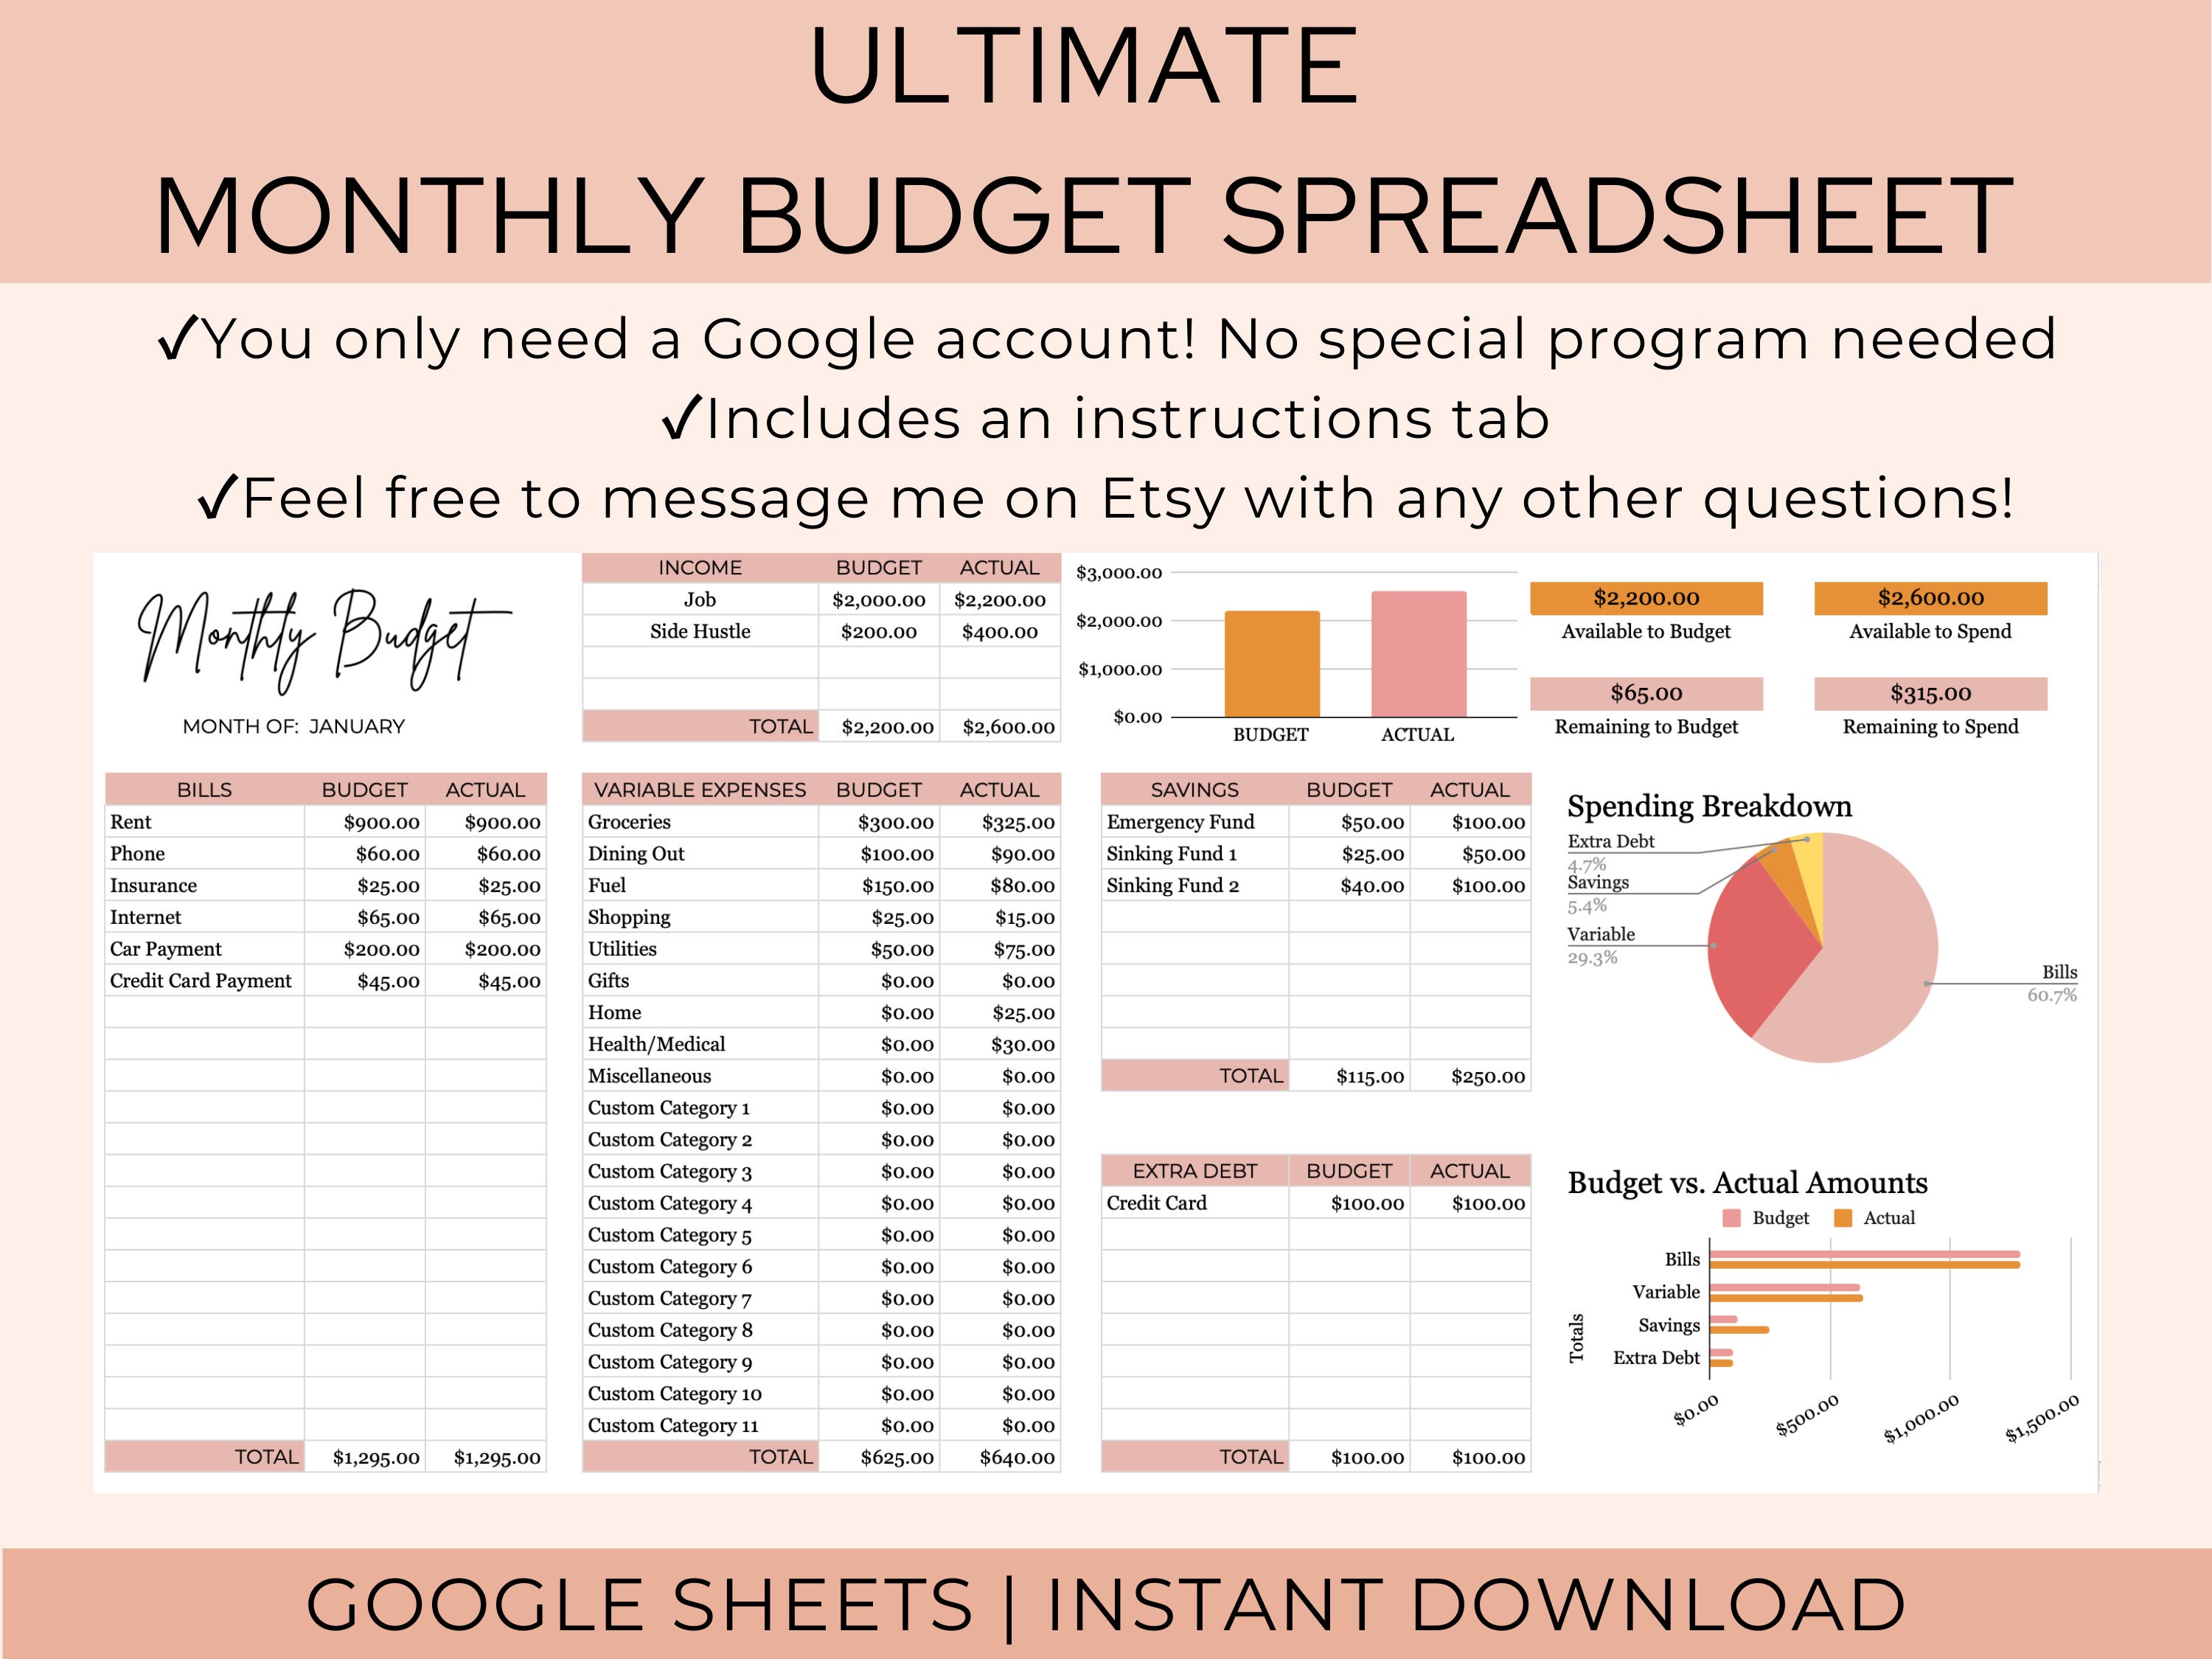
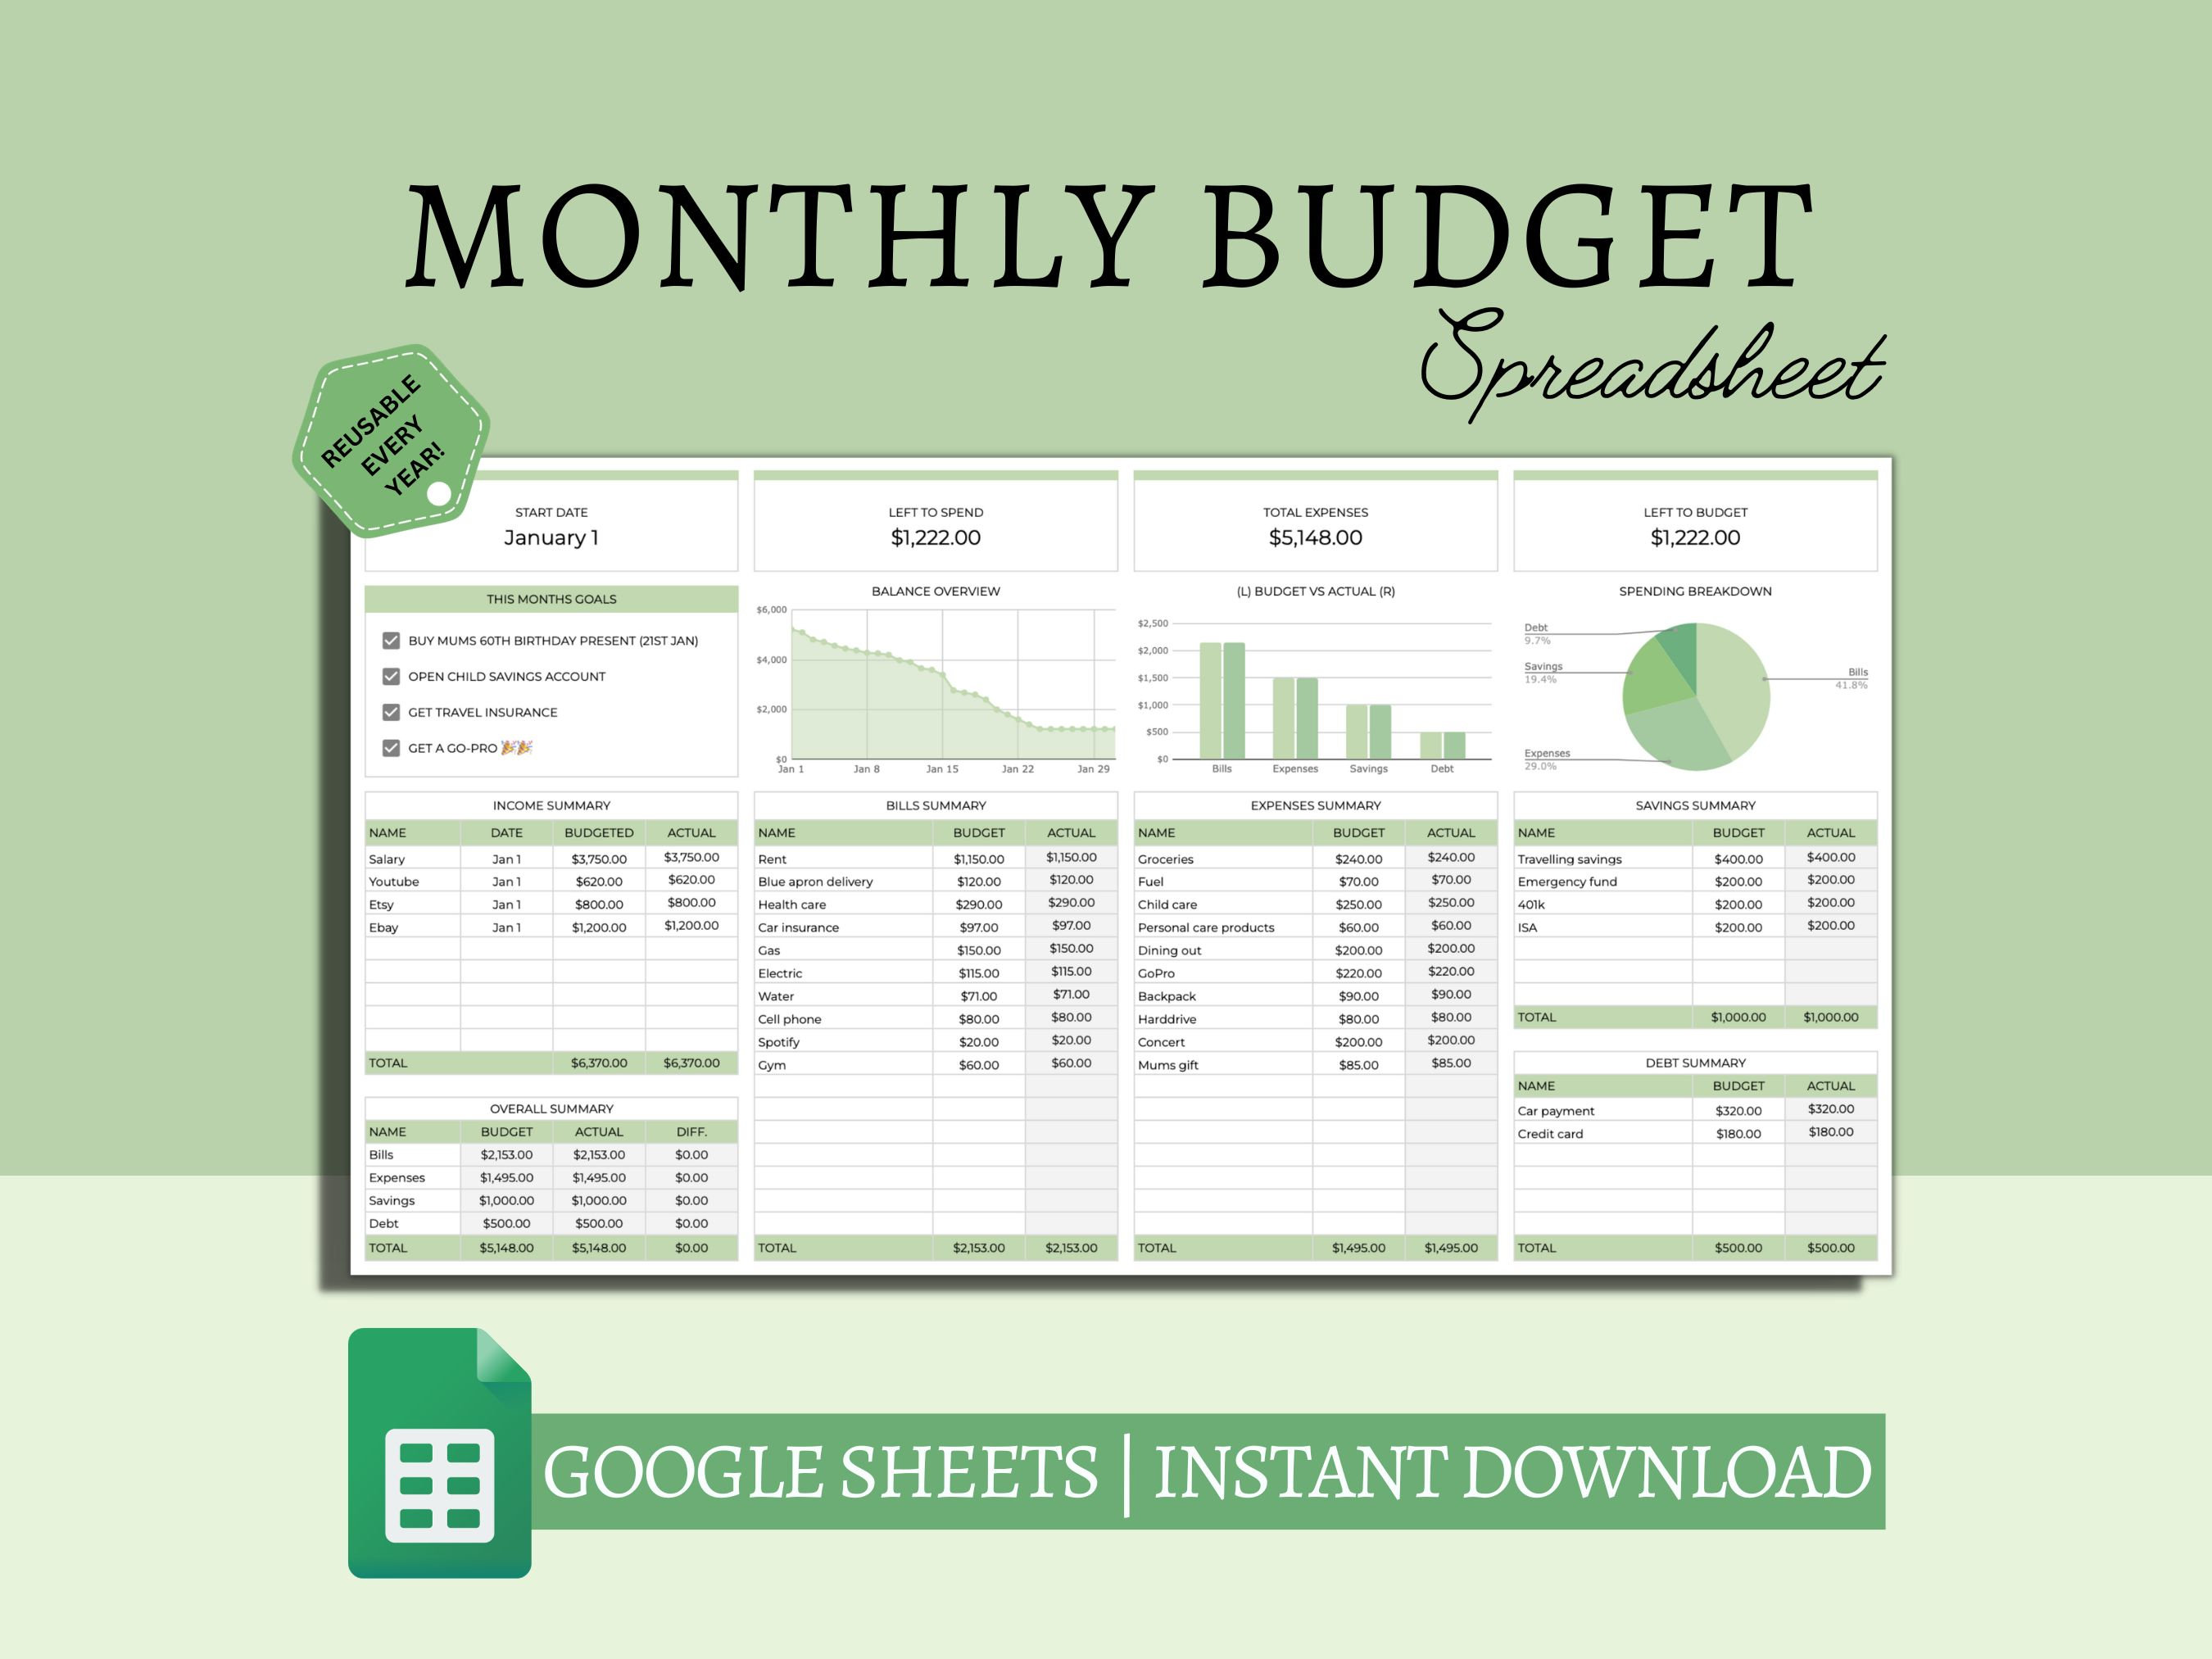
Building a Monthly Budget Template Google Sheets That Actually Sticks
Most people abandon their budget within three weeks. Not because budgeting is hard, but because they build something too rigid to survive real life. I built a Monthly Budget Template Google Sheets for my own finances about four years ago. It has survived every rent increase, freelance income swing, and unexpected car repair since then. Here is how it works. Open a new spreadsheet. Name it "Budget 2025." You are going to create four tabs across the bottom: Summary, Income, Expenses, and Transactions. That is the entire structure. Anything more and you will stop using it. In the Transactions tab, set up these columns: Date, Category, Description, Amount In, Amount Out, Month, Year. Nothing fancy. The Month and Year columns are where most people skip ahead and then regret it later. Put a data validation dropdown on Month with the names of all twelve months, and same for Year. This makes grouping later painless.
In Income, list your regular income sources as rows with expected monthly amounts. Use a formula in the Summary tab to pull totals: =SUMIF(Income!B:B, "Salary", Income!C:C) or whatever structure you build. Keep it simple. You will change it anyway. In Expenses, do the same for fixed costs: rent, utilities, subscriptions, insurance. Then add a section for variable spending categories: groceries, dining out, transportation, entertainment, healthcare, miscellaneous. The key insight beginners miss is that you need a buffer category. Call it "Miscellaneous" or "Sinking Fund." Every month, put $100 to $300 there. It absorbs the things you forget to plan for, like the $47 office supply run or the $18.50 parking ticket. Without this category, your budget will show a deficit every single month even when your math is correct, and you will lose faith in the system. The Summary tab ties it together. Put Income Total at the top, Expenses Total below it, and Net Savings as the difference. Add a conditional formatting rule so negative numbers turn red. That visual cue alone saves you from doing arithmetic in your head while half-awake on a Tuesday morning.
Here is the practical part that nobody mentions: do not enter every transaction daily. I tried that for six months. What actually works is a weekly sweep. Every Sunday evening, you open the Transactions tab and log the past seven days in one sitting. It takes about twelve minutes. You will spend about an hour a month reconciling against your bank statements. The alternative — chasing individual $3 coffee purchases throughout the week — kills momentum faster than any bad math. One edge case that almost broke my system: I once had a joint account with my partner and we kept double-entering the same expense. One of us logged it, the other forgot, and then when we synced our spreadsheets, the expense appeared twice in both copies. The fix was dead simple — I added a "Matched" checkbox column in Transactions and marked each entry as matched once both accounts confirmed it. Takes thirty seconds per line. Prevents the kind of confusion that makes you want to quit entirely. Another thing that matters: use absolute references sparingly. Beginners love =A1*0.3 because it feels precise. But when you move rows around, those hardcoded references break. Use =OFFSET(A1,2,0) or better yet, build named ranges. It adds ten minutes to setup and saves you four hours of debugging over a year.
Get the Full Details

The real bottleneck with a Google Sheets budget is collaboration. If you share the file with anyone — a partner, an accountant, a financial advisor — version control becomes a problem. Google Sheets does not have true multi-user editing with rollback. Two people editing the same cell at the same time creates a race condition that silently drops data. The workaround is assigning roles: one person logs transactions, another reviews and approves, and a third manages the formula structure. It sounds bureaucratic but it is faster than reconstructing corrupted numbers. If your income varies significantly — freelance, commission, seasonal work — this template still works but you need to adjust your approach. Instead of budgeting by expected income, budget by lowest realistic month. Calculate your expenses first, then see what margin exists between baseline expenses and your worst-case income month. If the margin is negative, you do not have a budgeting problem. You have a structural problem that no template will fix. I also learned the hard way that currency formatting matters more than you think. If you operate in multiple currencies or deal with international clients, mixing USD and EUR in the same column without a dedicated Currency column will corrupt your sums. Use =SUMIF(D:D,"USD",E:E) to separate totals by currency. It is a small detail that causes enormous headaches when you are trying to reconcile at end of quarter.
The one scenario where a Google Sheets budget completely fails: if you have more than fifteen spending categories and track everything manually, you will hit a maintenance wall within two months. The cognitive load of deciding which category a purchase belongs to becomes exhausting. At that point, the spreadsheet is working against you. Consider switching to an app with auto-categorization, or simplify drastically by collapsing your categories into five to seven buckets: Housing, Food, Transport, Healthcare, Debt, Savings, Everything Else. There is also a hidden tax on perfectionism. I spent three months refining conditional formatting rules, building pie charts, and creating dynamic dashboards. I used the dashboard exactly twice. The rest of the time, I was just looking at the raw Transactions tab. The most valuable part of this system is not the Summary page. It is the raw data. Keep the dashboard minimal. Let the transactions do the work. If you want a starting point, copy this structure and modify it. The specificity of your own financial situation will matter more than any template you download. A budget that matches your actual behavior beats a perfect budget you abandon after three weeks.