Commercial mortgage payments are harder to estimate than people think
A standard residential mortgage calculator works because the terms are mostly standardized. You plug in the principal, interest rate, and term, and you get a number. Commercial loans don't work that way. The payment you owe can depend on amortization length, balloon timing, prepayment penalties, ARM caps, and whether you're dealing with a fully amortizing loan or something more complex. A Monthly Commercial Mortgage Calculator helps cut through some of that noise, but it only gives you a reasonable estimate unless you feed it the right inputs. The core formula is the same one you learned in high school math. Monthly payment equals the principal times the monthly interest rate, divided by one minus one plus the monthly rate raised to the negative number of payments. In practice that means P times R over 1 - (1+R) to the negative N power. Most calculators do this internally. You just need to understand what each variable actually represents in a commercial context. P is the loan amount, which in commercial real estate is typically a percentage of the property value or appraised value, not the purchase price. Lenders usually finance between 65 and 75 percent for a standard deal. The cap rate on the property drives the loan-to-value ratio, so a higher cap rate property might get a lower LTV than a class-A asset in a prime market. This matters because your principal balance determines everything downstream.
Using a Monthly Commercial Mortgage Calculator correctly
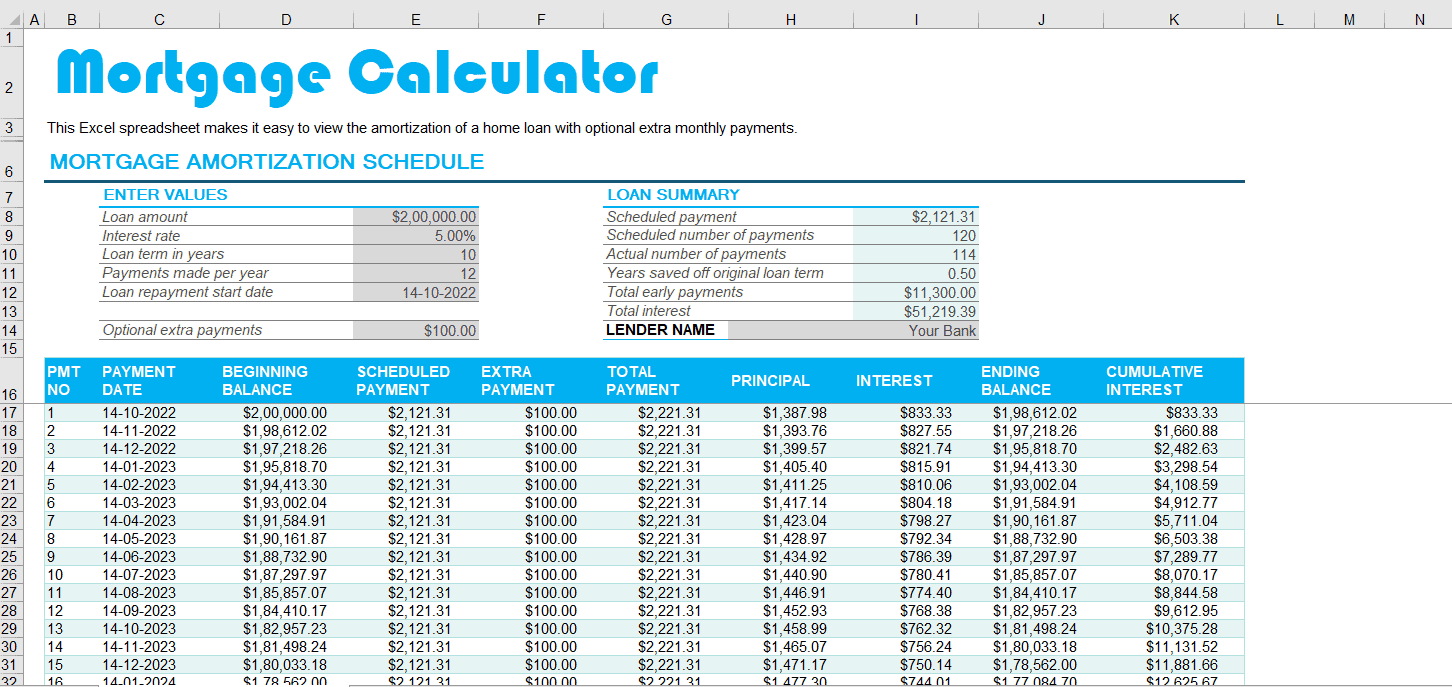
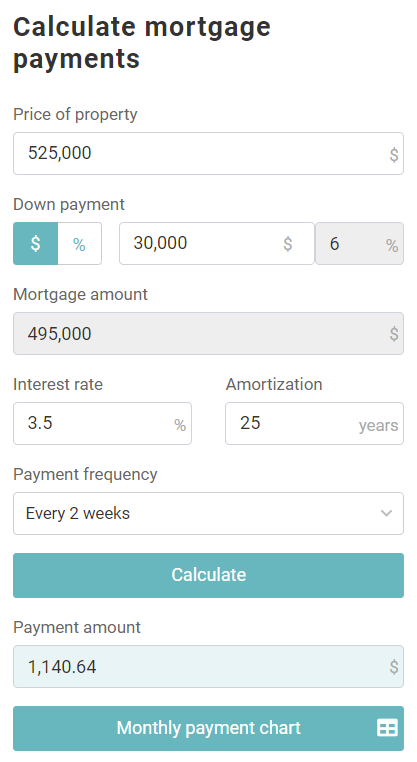
Enter the loan amount, the annual interest rate, and the amortization period. That gives you a baseline payment. But here is where most people stop and miss critical details. Commercial loans frequently have a shorter amortization than the actual loan term. A common structure is a 30-year amortization with a 7-year balloon. The calculator will show you the payment based on 30 years of amortization, but you need to understand that at year seven, the entire remaining balance comes due unless you refinance. The payment you see in the calculator is not necessarily the payment you'll make every month until maturity if there are interest-only periods or step adjustments. Interest rates in commercial lending are often quoted as spreads over SOFR or the prime rate. A loan might be priced at SOFR plus 275 basis points. If SOFR is 4.25 percent, your effective rate is 7 percent. Many calculators ask for a flat rate, so you need to calculate the total before entering it. Variable-rate loans will change your payment over time, and most simple calculators don't model that unless they have a specific adjustable-rate feature built in. I spent three hours last year tracking down why a client's actual payment was $400 per month higher than what the calculator showed. The loan had a debt service coverage ratio requirement baked into the terms. The lender's underwriting model assumed a DSCR of 1.25, and the amortization schedule was adjusted downward accordingly, which increased the monthly payment. The standard Monthly Commercial Mortgage Calculator had no way to account for that. I ended up building a spreadsheet that factored in the DSCR constraint and recalculated the payment based on the required debt service rather than the raw amortization formula. It took about 20 minutes once I had the right template.
What commercial mortgage calculators typically miss
Property taxes and insurance are usually escrowed into the payment on commercial loans, but most online calculators don't include them. A $2 million office building in a high-tax jurisdiction could be paying $15,000 to $25,000 annually in property taxes alone. That adds roughly $1,250 to $2,100 per month to your total housing cost. You need to factor this in manually or find a calculator that includes tax and insurance inputs. PMI or mortgage insurance is another omission. Commercial loans above a certain loan-to-value threshold often require CMRA or similar insurance products, which can add 0.5 to 1.5 percent to your effective borrowing cost. Prepayment penalties are a major issue that virtually no free calculator addresses. A typical commercial prepayment penalty might be 5 percent declining to 1 percent over five years, or it might use a yield-maintenance formula. If you plan to sell or refinance within the first few years, the penalty can eat into your proceeds significantly. I once saw a borrower who refinanced at a lower rate only to find the prepayment penalty was $47,000, which negated most of the monthly savings for nearly two years. There is no shortcut for this. You need to read the loan estimate and prospectus carefully. Another thing calculators ignore is the difference between simple interest and compound interest compounding methods. Some commercial loans compound daily rather than monthly. The payment difference is small on a standard loan but becomes noticeable on larger balances over longer terms. A $3 million loan at 7 percent over 25 years compounds differently depending on the method, and the variance can be several hundred dollars per month.
Get the Full Details

Downsides and when a calculator fails you
A Monthly Commercial Mortgage Calculator is useful for initial screening and quick comparisons between scenarios. It is not useful for final decision-making. The output is only as good as the inputs you provide, and commercial loan terms are far more variable than residential ones. If you are evaluating a multifamily acquisition with a 1031 exchange component, the calculator will not account for the tax implications of the exchange on your overall cash flow. If you are dealing with a CMB or CMBS loan, the seasoning requirements and lockout periods are entirely separate from the payment calculation. The calculator cannot tell you whether you can exit the loan early or what the costs would be if you tried. For anything beyond a straightforward amortizing commercial loan, you should work with a commercial mortgage broker or a loan officer who has access to the actual loan programs available. They can model the full payment structure including escrows, insurance, taxes, and any lender fees that get rolled into the note. A free online calculator will typically show you the base principal and interest only, which is maybe 60 to 70 percent of your actual monthly outlay on a commercial deal. If you need a more detailed analysis, the best approach is to take the calculator output and build a simple spreadsheet that layers in the additional costs. Use the calculator for the base P&I figure, then add lines for taxes, insurance, and any mortgage insurance. For variable-rate loans, run scenarios at different rate levels so you can see the payment range. This takes about 15 minutes and gives you a much more realistic picture than the raw calculator number alone.
The biggest mistake I see is people treating the calculator result as the final answer. It is a starting point. Commercial lending is messy, and the real numbers only emerge when you read the actual loan documents. Use the calculator to get a sense of whether the deal makes rough sense, then dig into the specifics with someone who understands the loan structure you are looking at. The time you save by doing that upfront usually prevents a costly surprise down the line.