Building a Monthly Economics Template That Actually Survives Real Use
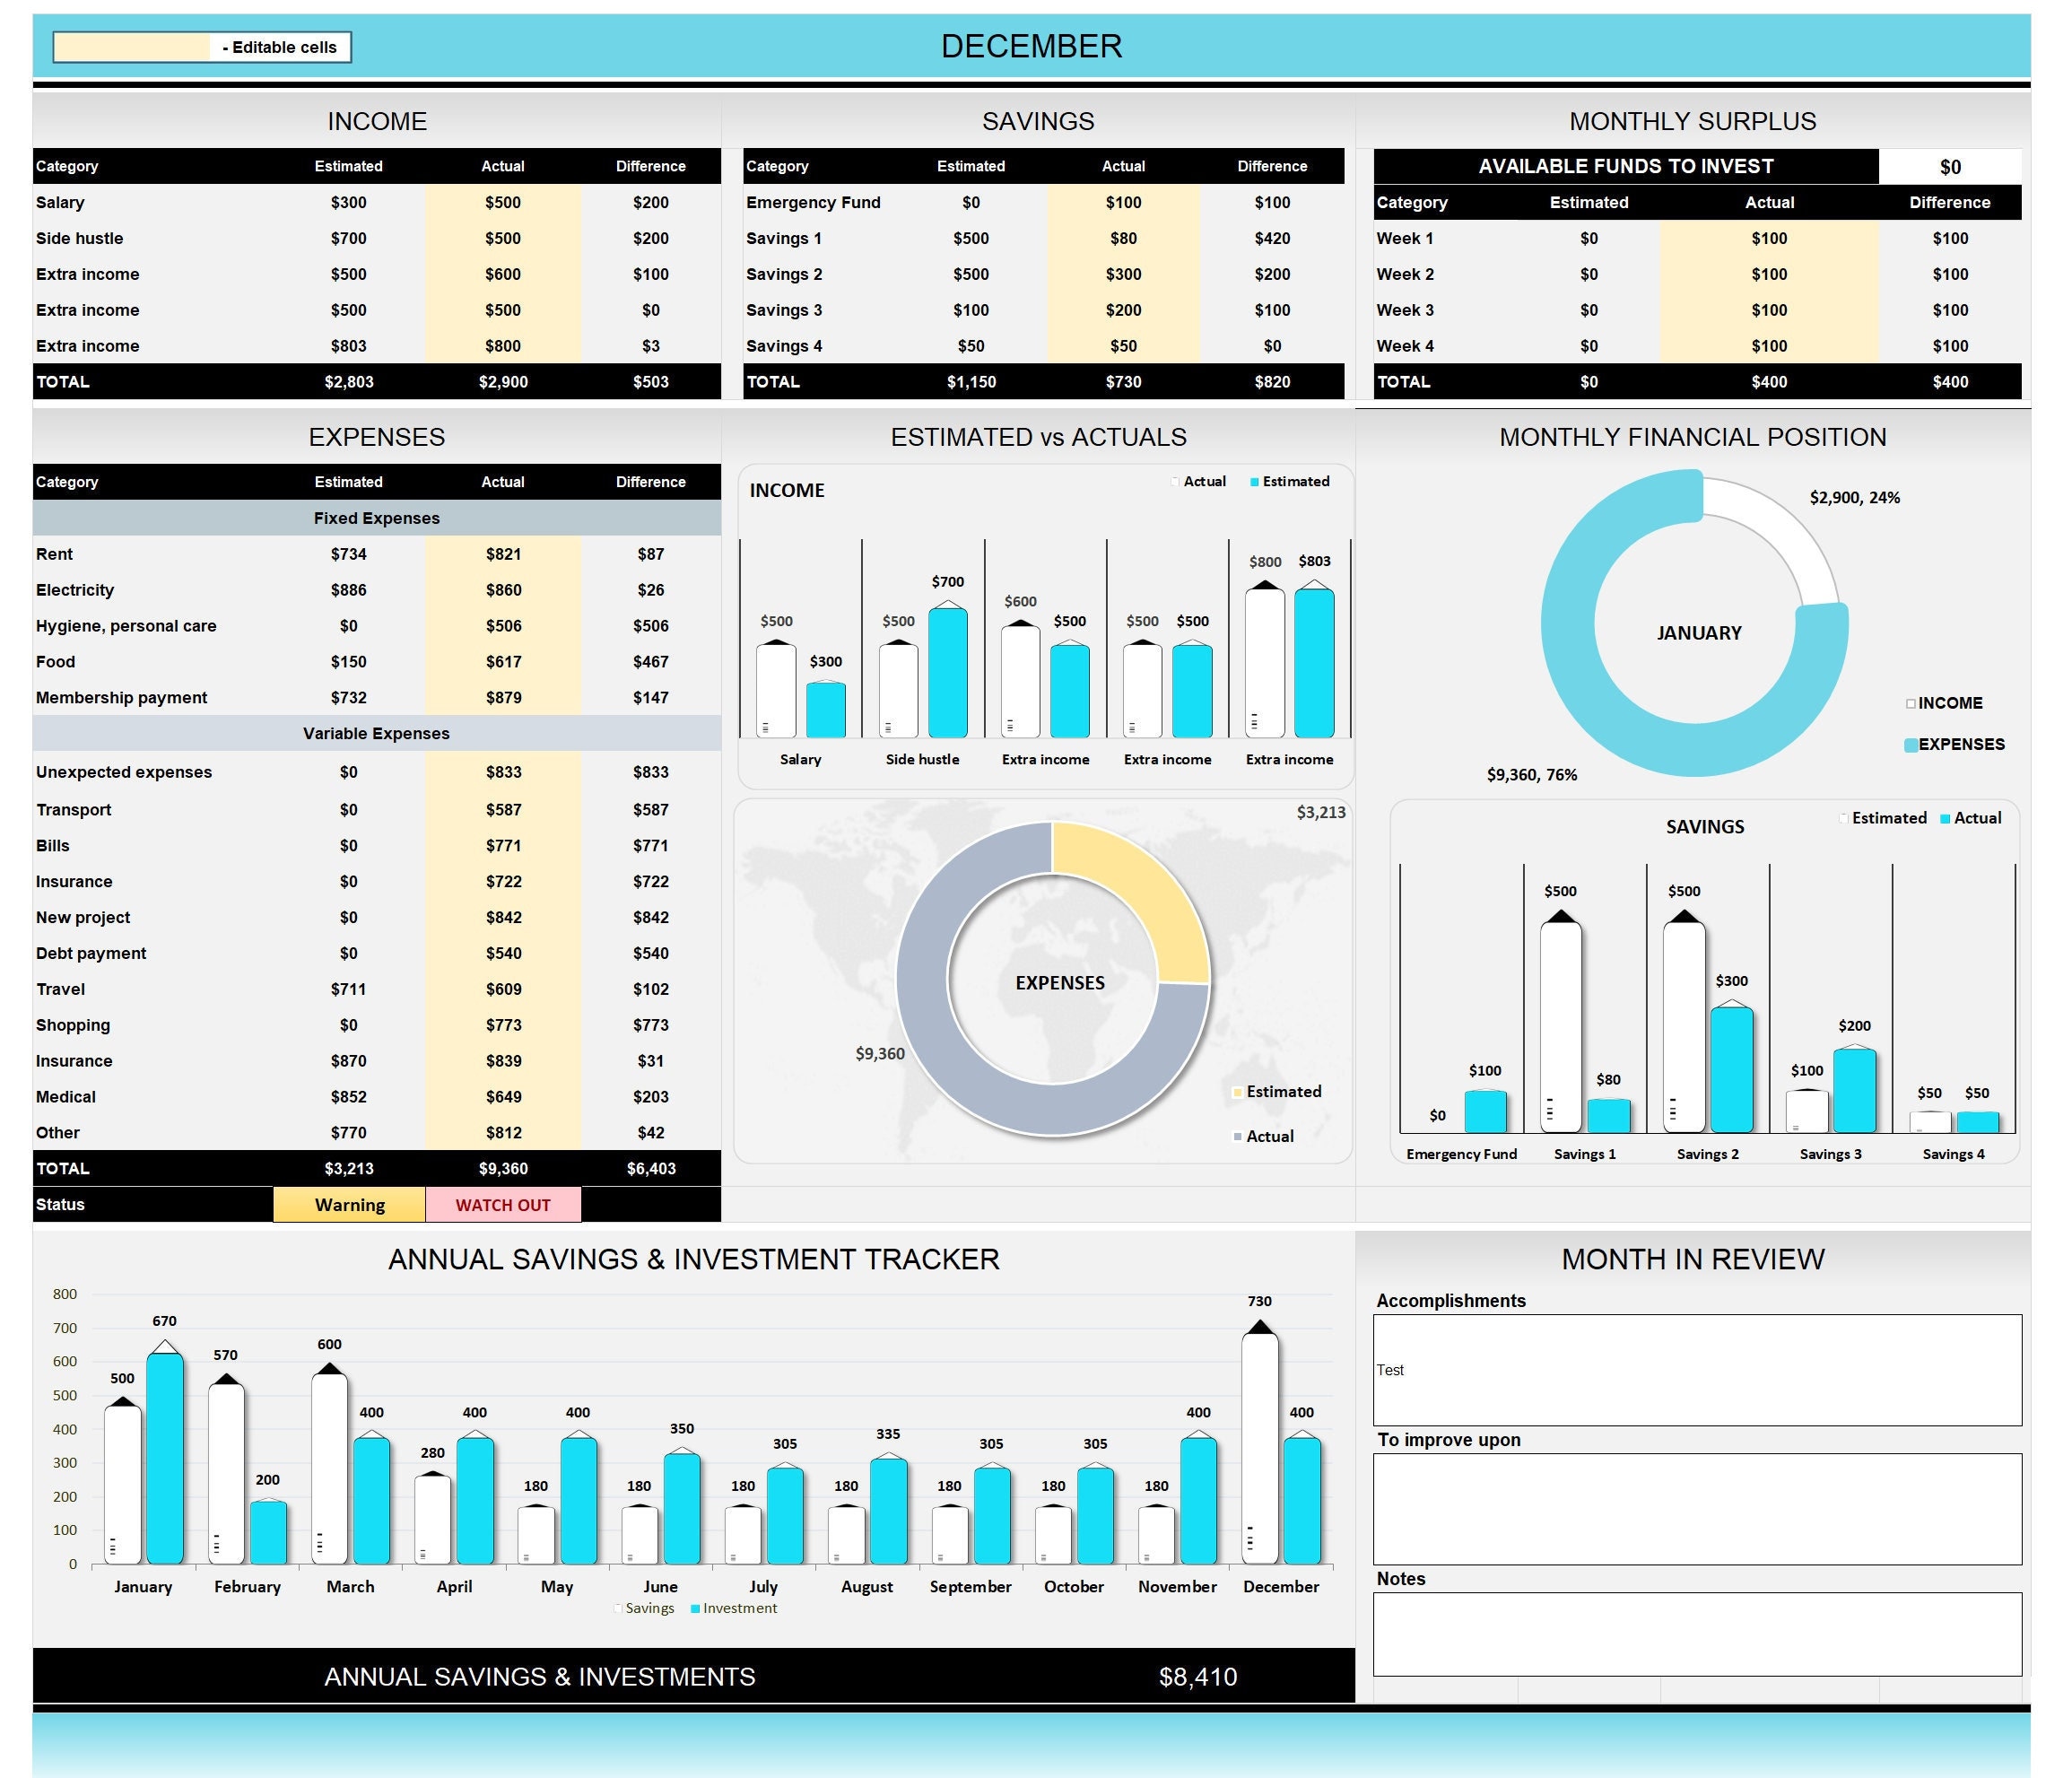
Most spreadsheet templates for personal economics fall apart within three months. They look clean when you first set them up, but the moment your data gets messy — receipts, partial payments, transactions split between categories — they break. I've built and rebuilt these things enough times to know where the weak points are, so here's what actually works when you stop trying to make it pretty and start making it functional. The core of a working template is structure before styling. Start with three sheets. The first is raw data entry where you dump every transaction as it happens. The second is your categorized summary with pivot tables pulling from that raw sheet. The third is your monthly view with month-over-month comparisons. Anything more than that and you're maintaining a system instead of tracking your money. The raw data sheet should have these columns in this exact order: date, description, amount, category, subcategory, payment method, note. Keep the date as a true date field, not text. That one decision saves you from pivot table nightmares later. The amount column should store the raw number without currency formatting — formatting belongs in the summary sheet, not the input layer. I learned this the hard way when I tried to sum a column of currency-formatted cells and spent two hours figuring out why my totals were returning errors instead of numbers.
For categorization, use a flat list. Don't create nested category hierarchies in your raw data. Instead, put category in one column and subcategory in the next. This gives you the organizational depth you need without making your data entry slower. A typical structure looks like housing for rent or mortgage, utilities for electric or internet, transportation for fuel or car payment, groceries, dining, subscriptions, healthcare, and personal spending. Your subcategories should be specific enough to be useful but broad enough that you don't end up creating a new one every week. The summary sheet is where most templates fail. People build complex formulas that calculate everything at once. What you actually need is a pivot table that groups by month and category, with a second pivot that shows running totals. Add a simple subtraction row at the bottom that calculates net cash flow by subtracting total expenses from total income. That's it. Five or six lines of visible math, the rest handled by pivots. This usually cuts the monthly review process down to about ten minutes instead of the forty-five minutes people spend wrestling with broken formulas. Here's something people don't usually tell you about monthly economics tracking: the biggest accuracy problem isn't forgetting to log transactions. It's the timing mismatch between when a charge hits your account and when it actually belongs to a month. I had a subscriber service that billed on the 28th of each month, but it always fell in the wrong month on my summary because I was sorting by transaction date instead of the billing period date. The workaround was adding a "billing period" column to my raw data and using that as the primary sort key in my pivot tables. Takes thirty seconds to fill in and prevents an entire class of errors.
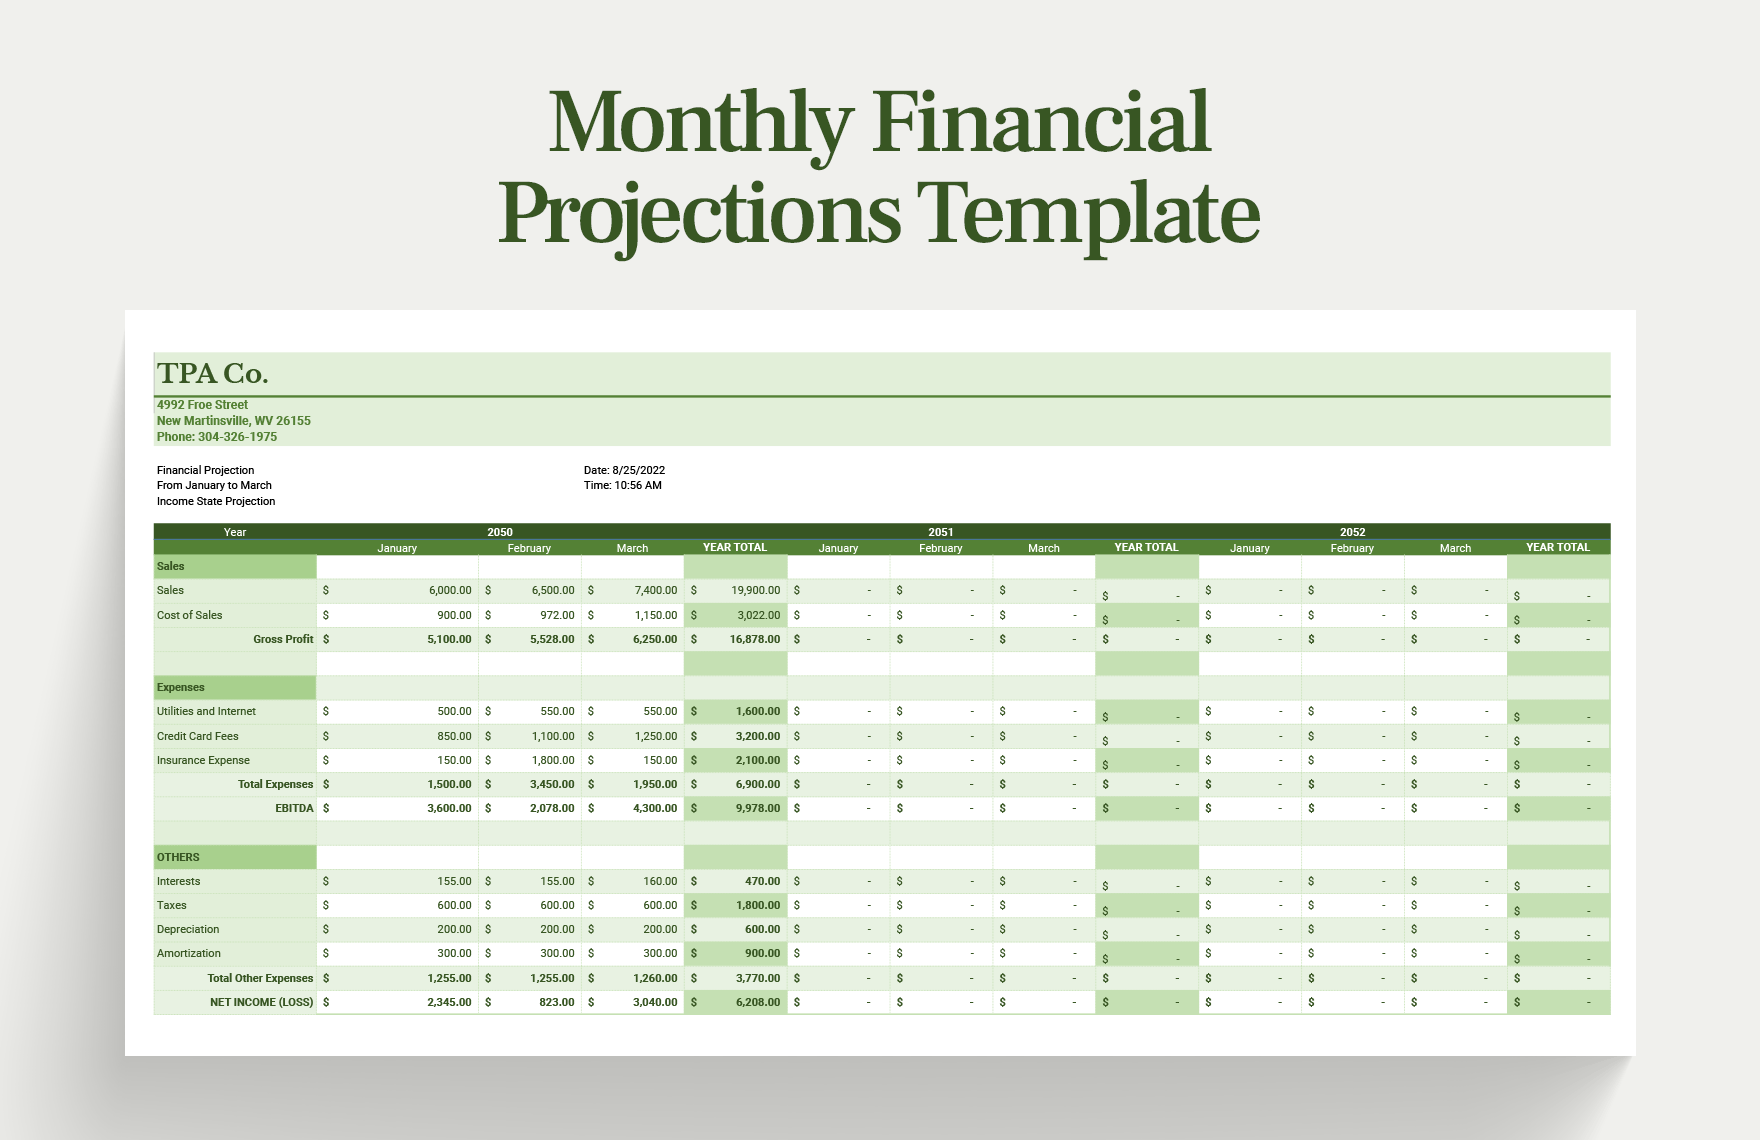
Another counter-intuitive thing: don't try to reconcile your template against your bank statements every single month. Do it quarterly. Reconciling monthly sounds disciplined but it's where most people quit. They get overwhelmed by the volume of minor discrepancies — a dollar here, a fee there — and abandon the whole system. Quarterly reconciliation catches the same errors without the burnout. You'll spot the pattern mismatches and one-off charges just fine, and you'll actually stick with the template long enough for it to be useful. For the monthly comparison view, use a simple grid. Rows are your categories. Columns are the current month, previous month, and the difference between them. Add a conditional format that highlights any category where spending increased by more than fifteen percent. That threshold catches genuine problems without flagging normal month-to-month variation. I've seen people set the threshold at five percent and end up highlighting everything, which makes the system useless because nothing stands out. There are legitimate limitations to this approach that no template guides will tell you. If your monthly income varies significantly — freelance work, commission, seasonal employment — the template becomes less useful because your baseline is constantly shifting. In that case, you're better off tracking on a rolling twelve-month basis instead of month-over-month. The template can handle this by adding a trailing twelve-month column, but it adds complexity that may not be worth it if your primary goal is just knowing where your money went each month.
Get the Full Details
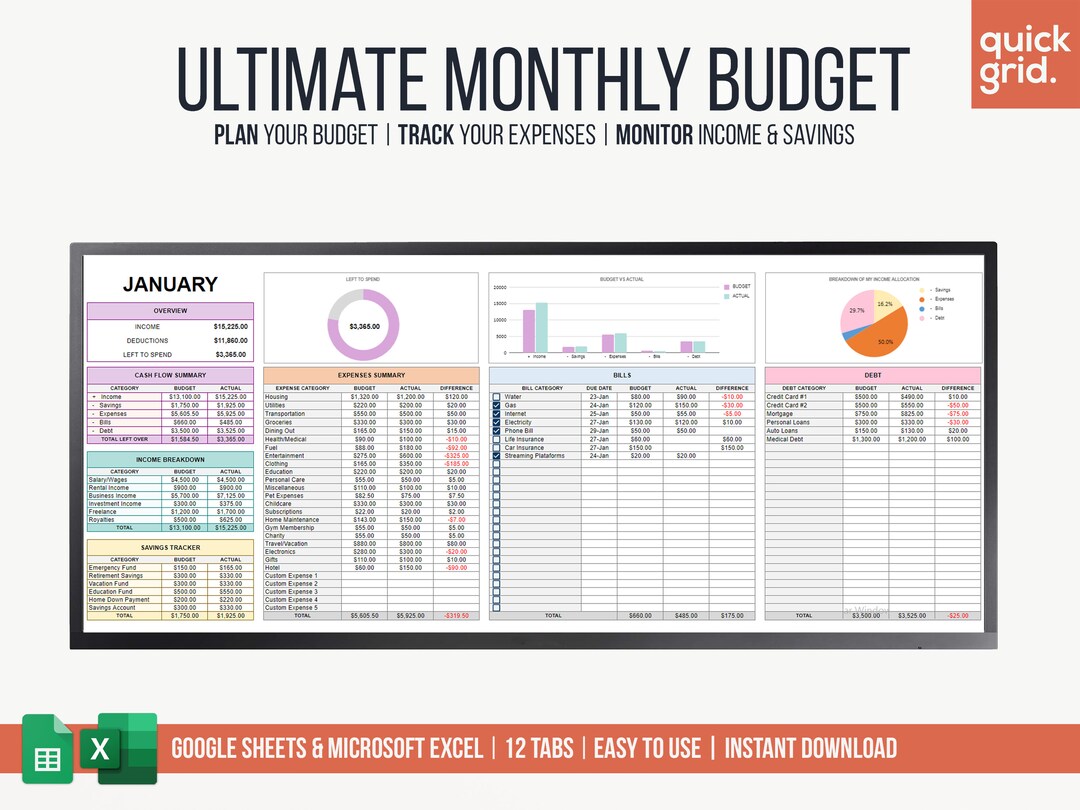
Another failure mode: if you have more than twenty categories, the template starts to lose its value. You spend more time deciding which bucket a transaction goes into than actually gaining insight from the data. The solution is to merge subcategories back into parent categories for your summary view and keep the granularity only in the raw data sheet where it doesn't slow you down. Here's what I'd recommend if you're starting from scratch. Build the raw data sheet first and use it for two weeks before adding any summary calculations. You need to understand your actual spending patterns before you design the reporting layer. Most people build the reporting first and then find their categories don't match their real behavior. I've done this twice myself. The second time I just tracked everything manually for fourteen days, noted which categories actually mattered, and then built the template around those instead of an idealized version of my finances. The template itself doesn't need to be complicated. It needs to be something you'll actually open every month and update without frustration. That means keeping the data entry surface minimal, the calculations automatic, and the reports glanceable. If you can look at the summary sheet and understand your financial position in under thirty seconds, you've built the right thing. If you're clicking through multiple sheets and hunting for where numbers came from, you've overbuilt it.