What Monthly Finance Actually Is
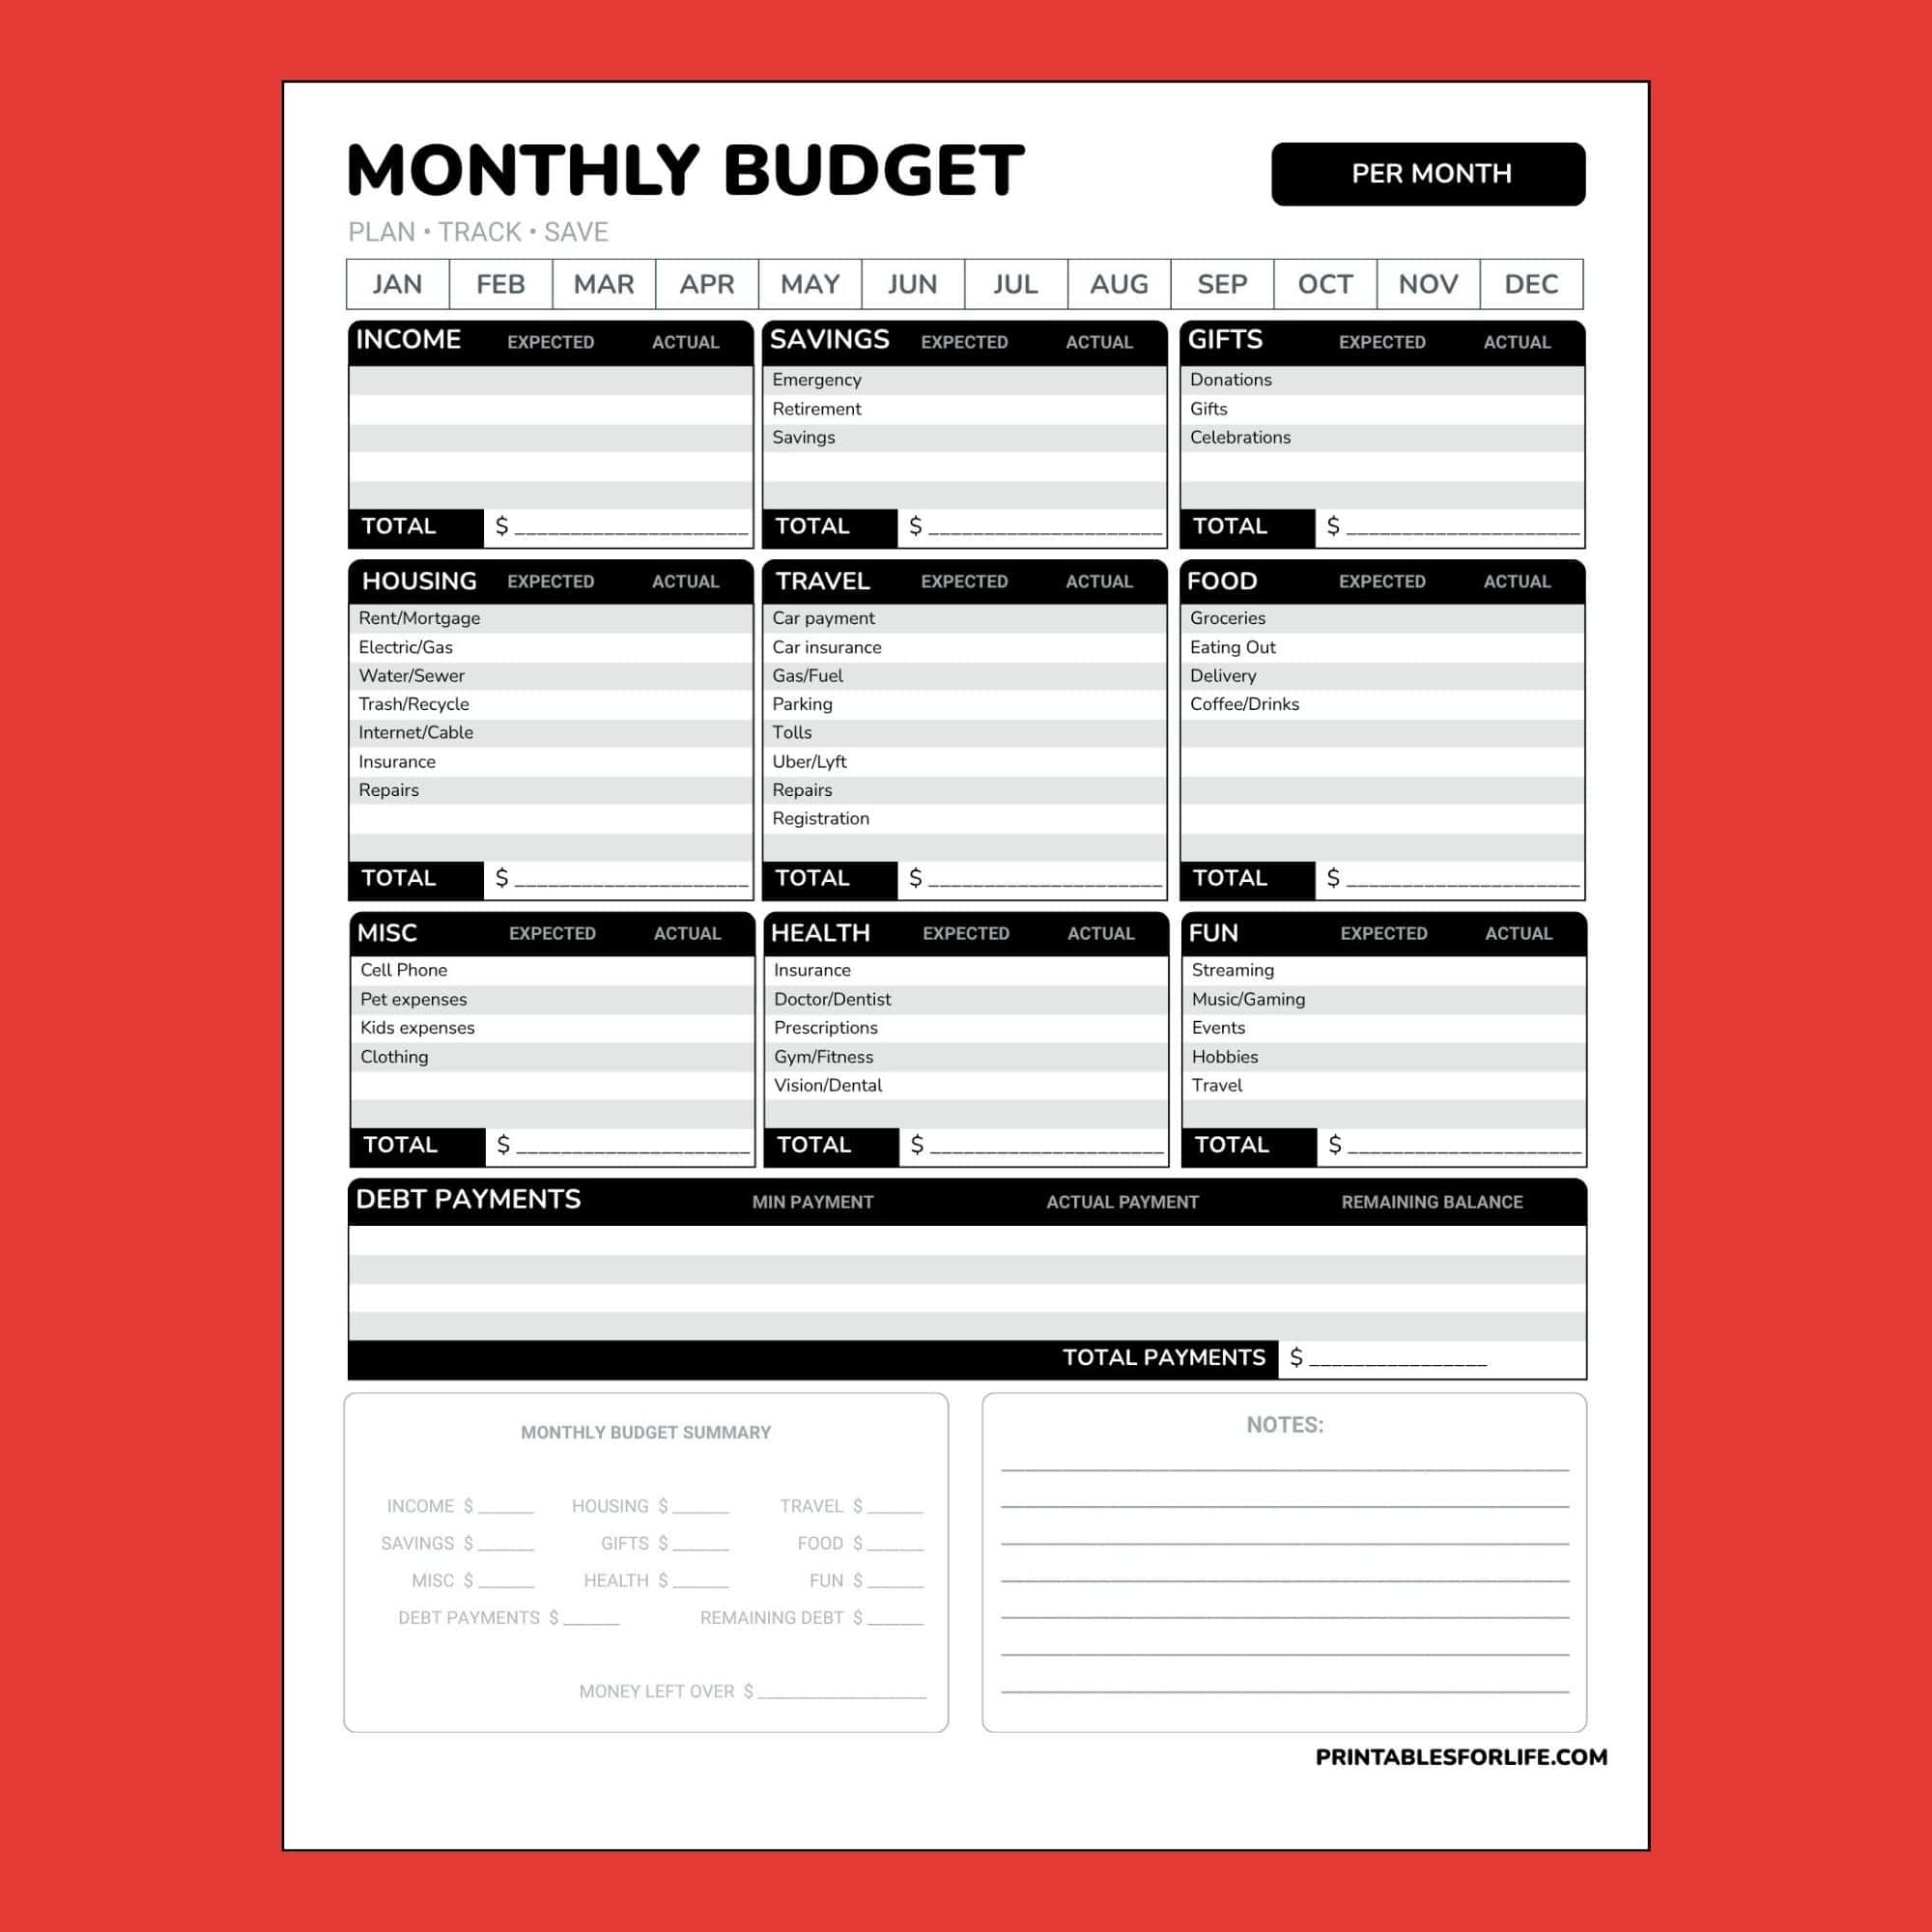
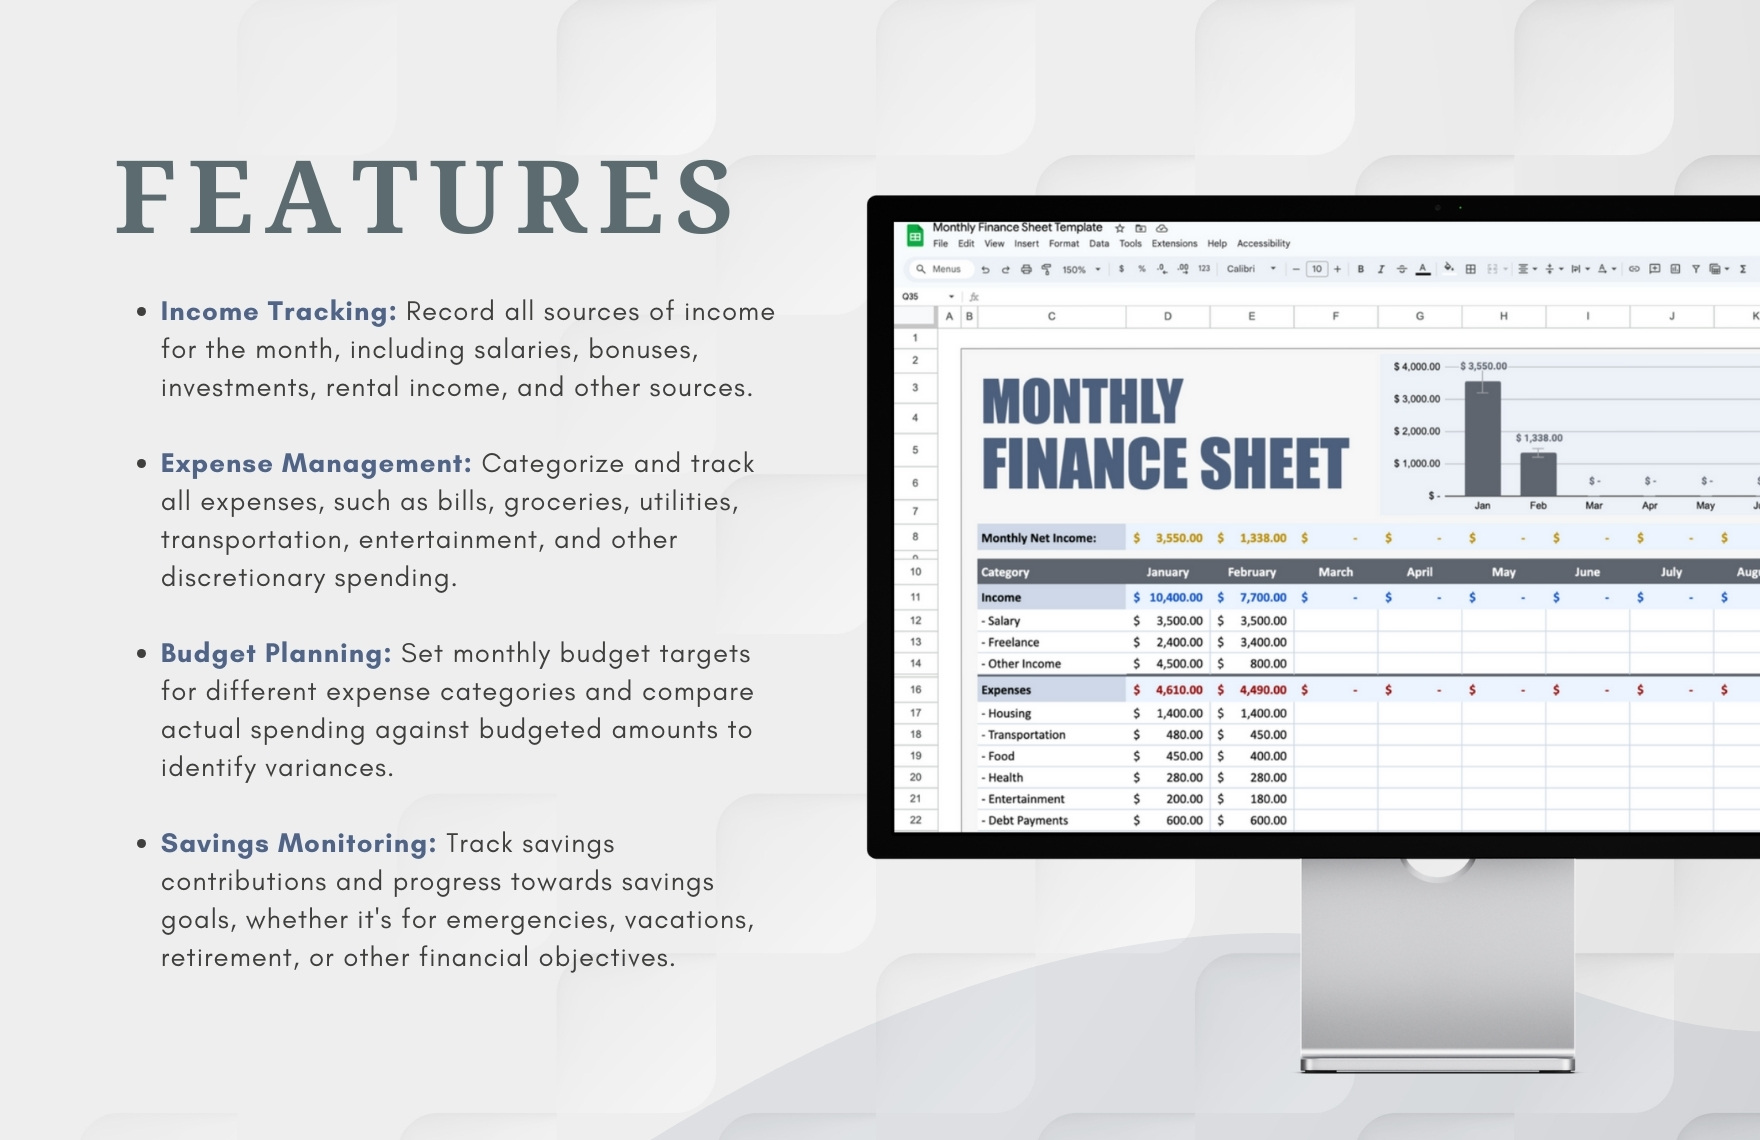
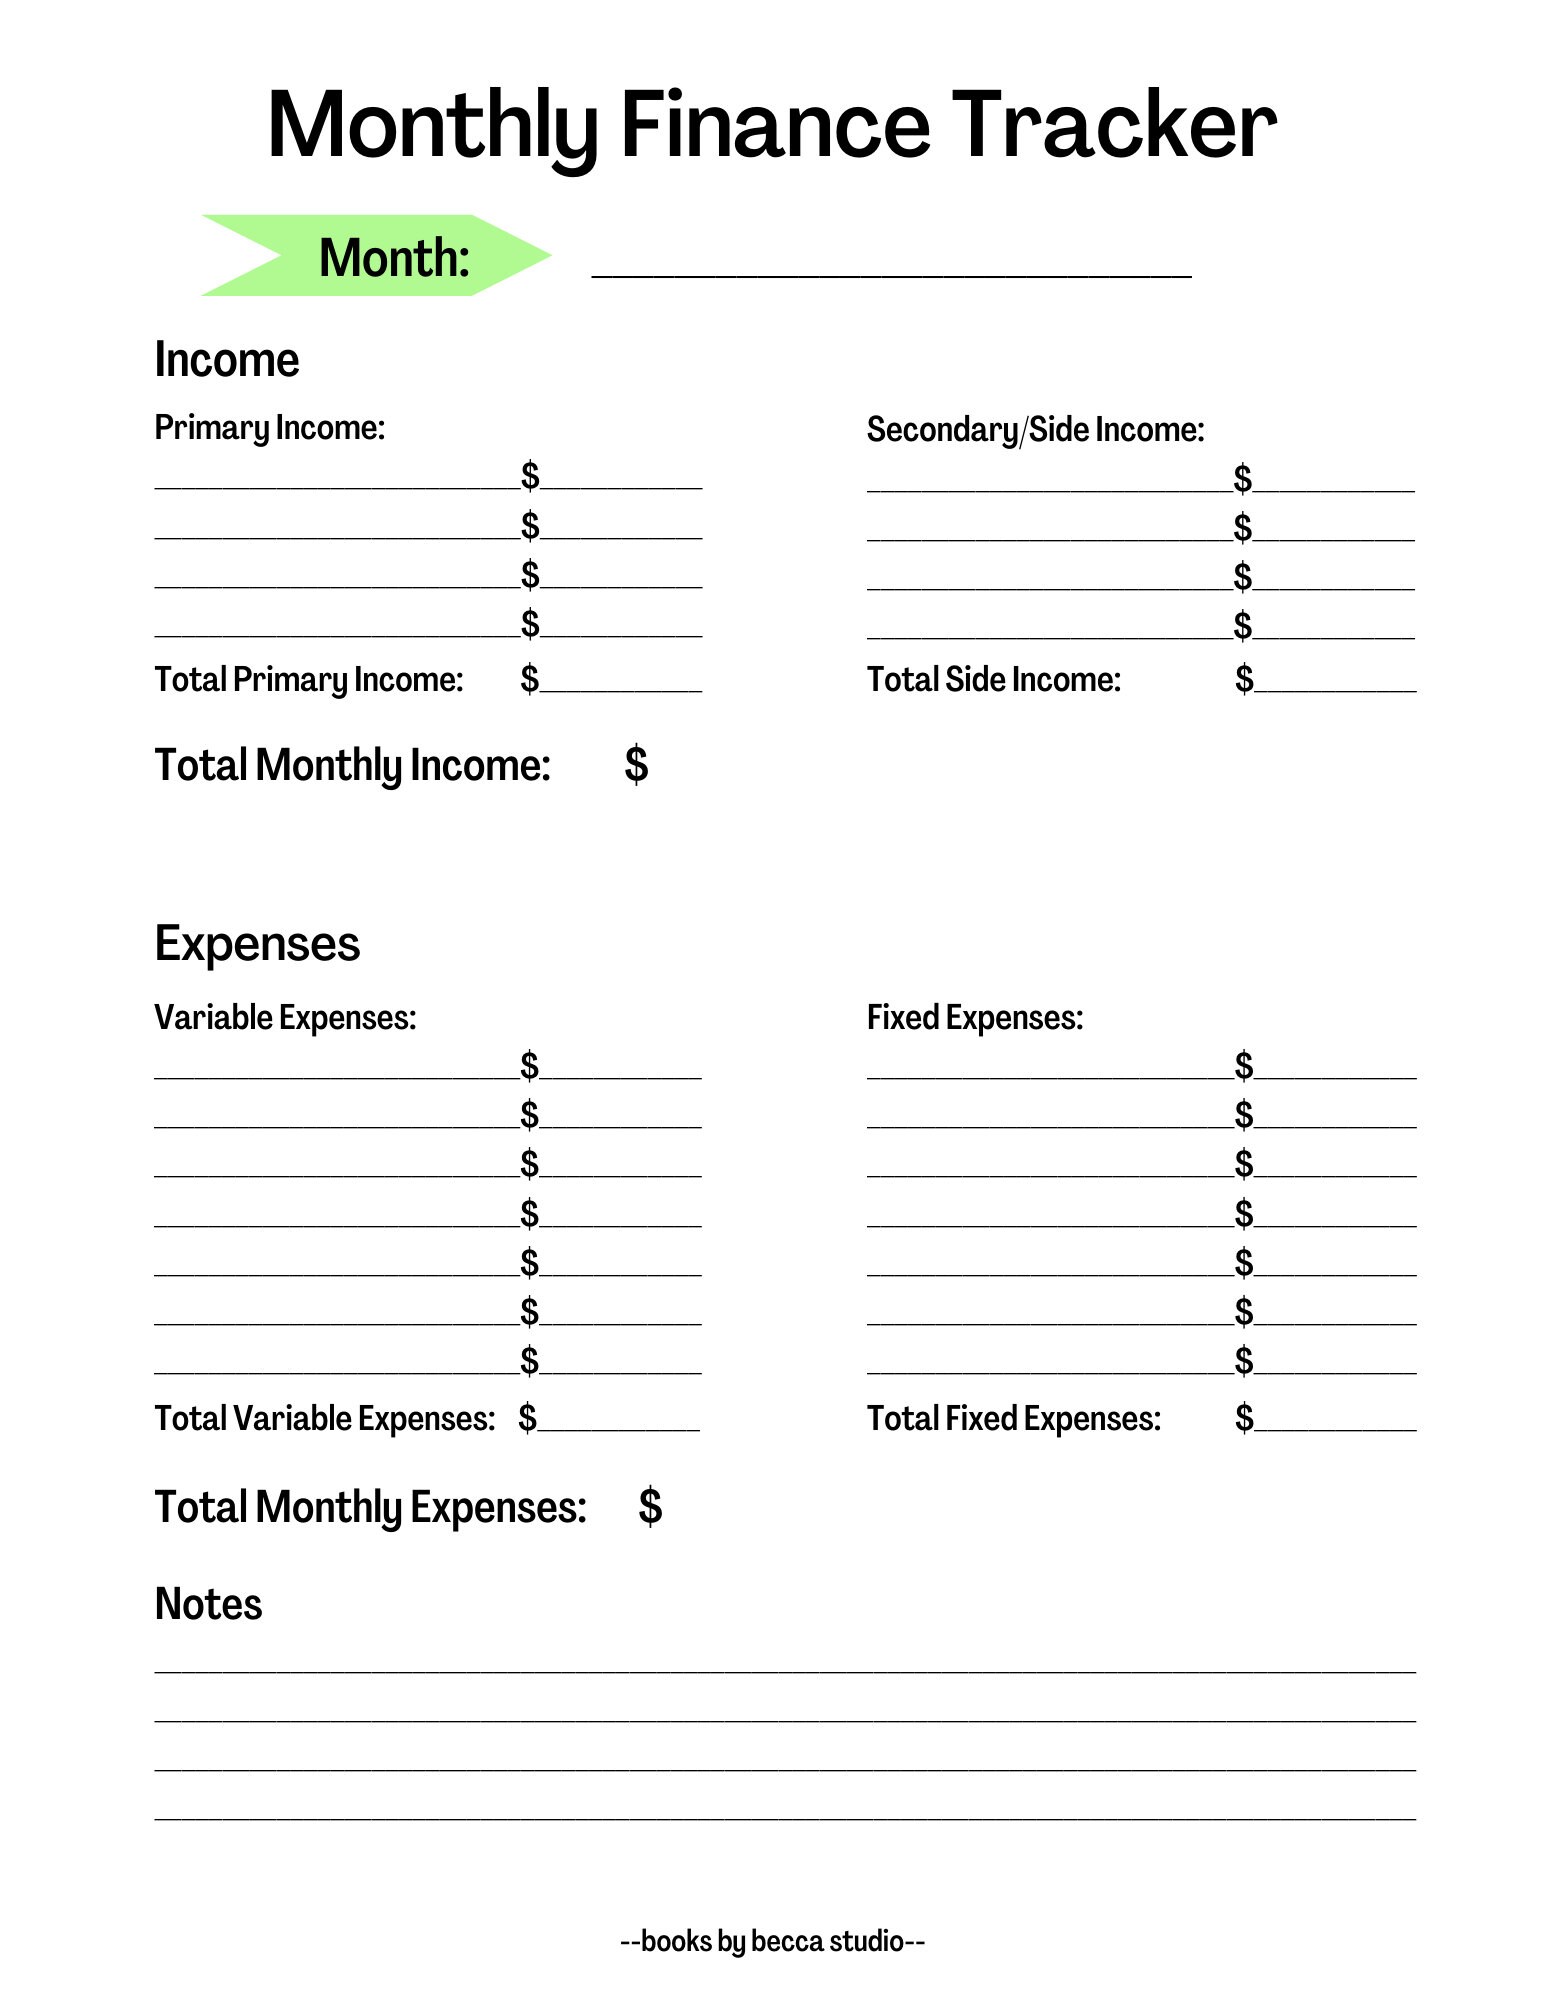
Monthly Finance is a personal budgeting framework and accompanying spreadsheet template that organizes your income, expenses, and savings into a monthly view. The free version gives you a complete set of sheets — income tracking, expense categories, a savings goal tracker, and a simple cash-flow summary. It's not software you install. You open the file, enter your numbers, and it recalculates everything automatically. I've used similar templates for years across different clients and personal projects. The free download version covers the basics well. It won't replace a full accounting package, but for most people managing their own household budget, it does exactly what it claims.
Monthly Finance Free Download — Where to Get It
The template is available directly from the creator's website at monthlyfinance.com/download. There's no email gate or paid upgrade required to access the base file. It comes in both Excel and Google Sheets formats. I prefer the Google Sheets version because it syncs across devices and lets you share access with a partner without sending files back and forth. The download is around 240KB. It opens immediately. No setup wizard, no configuration screen. Just a blank workbook with labeled tabs waiting for your data.
How It Actually Works in Practice
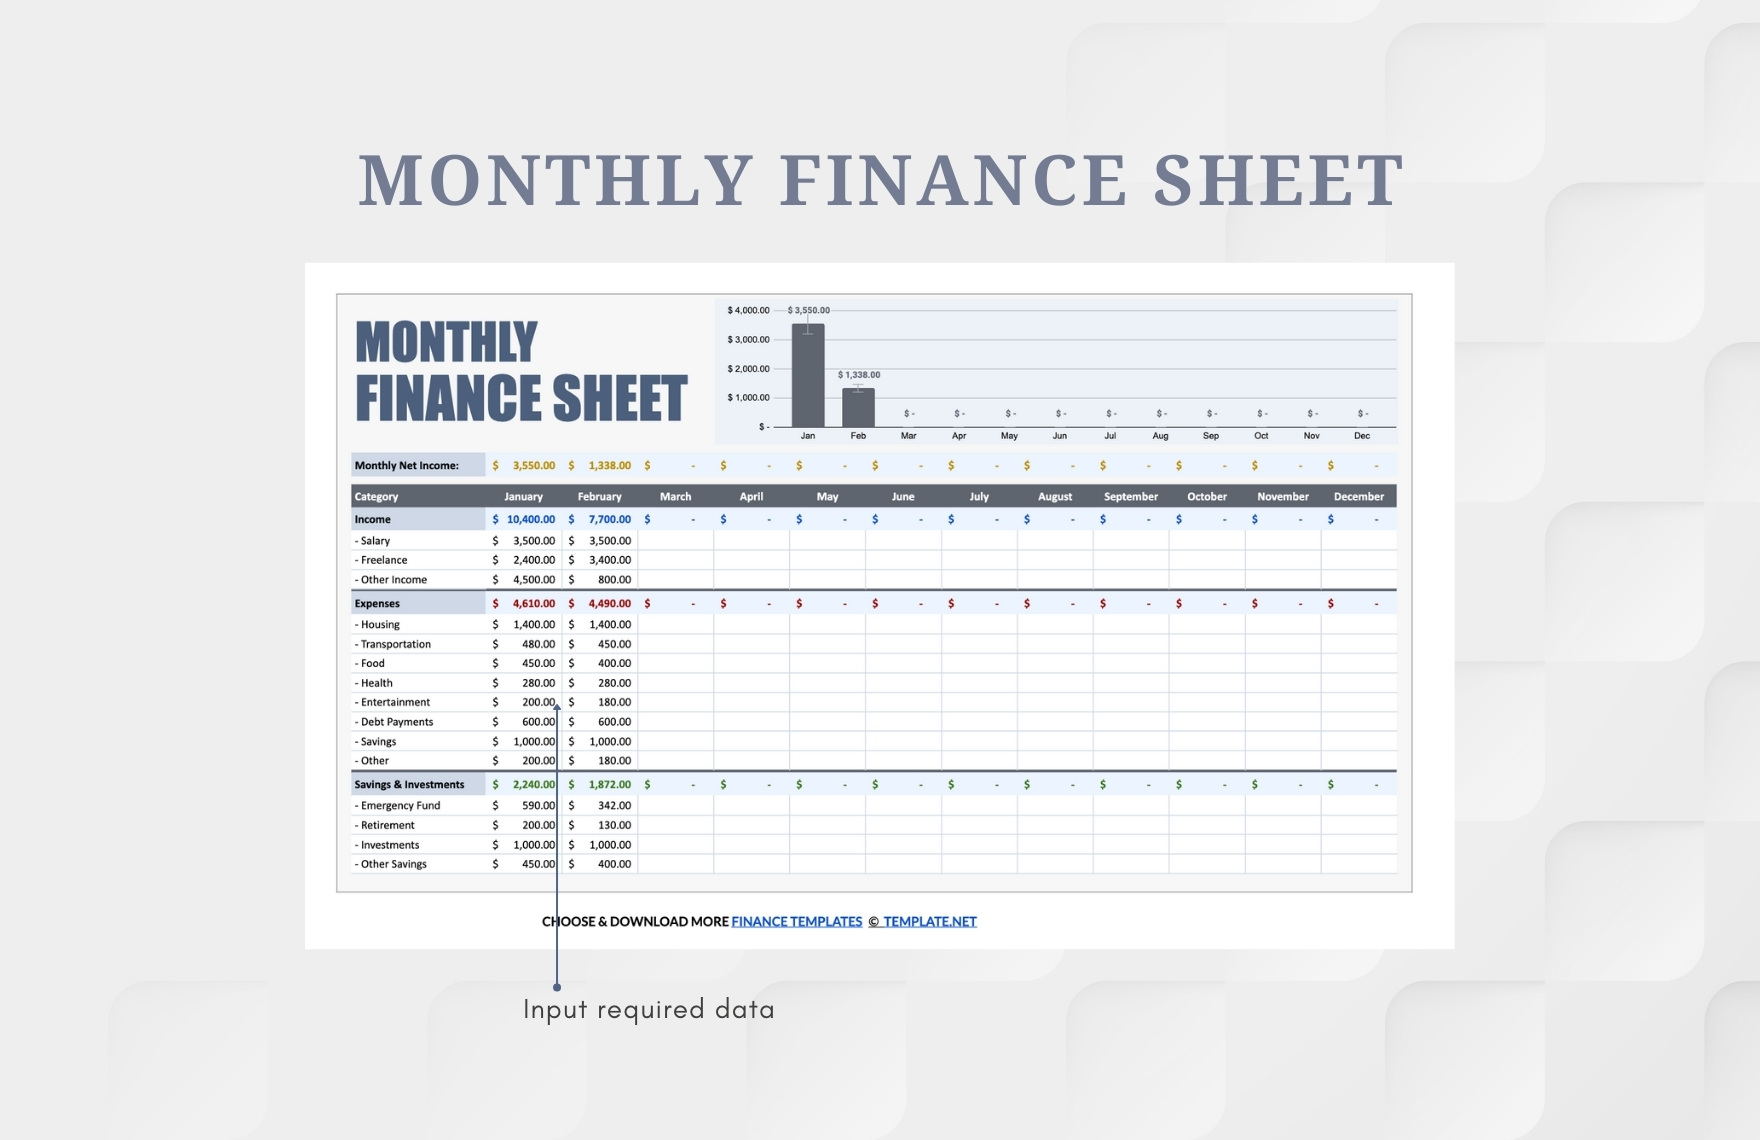
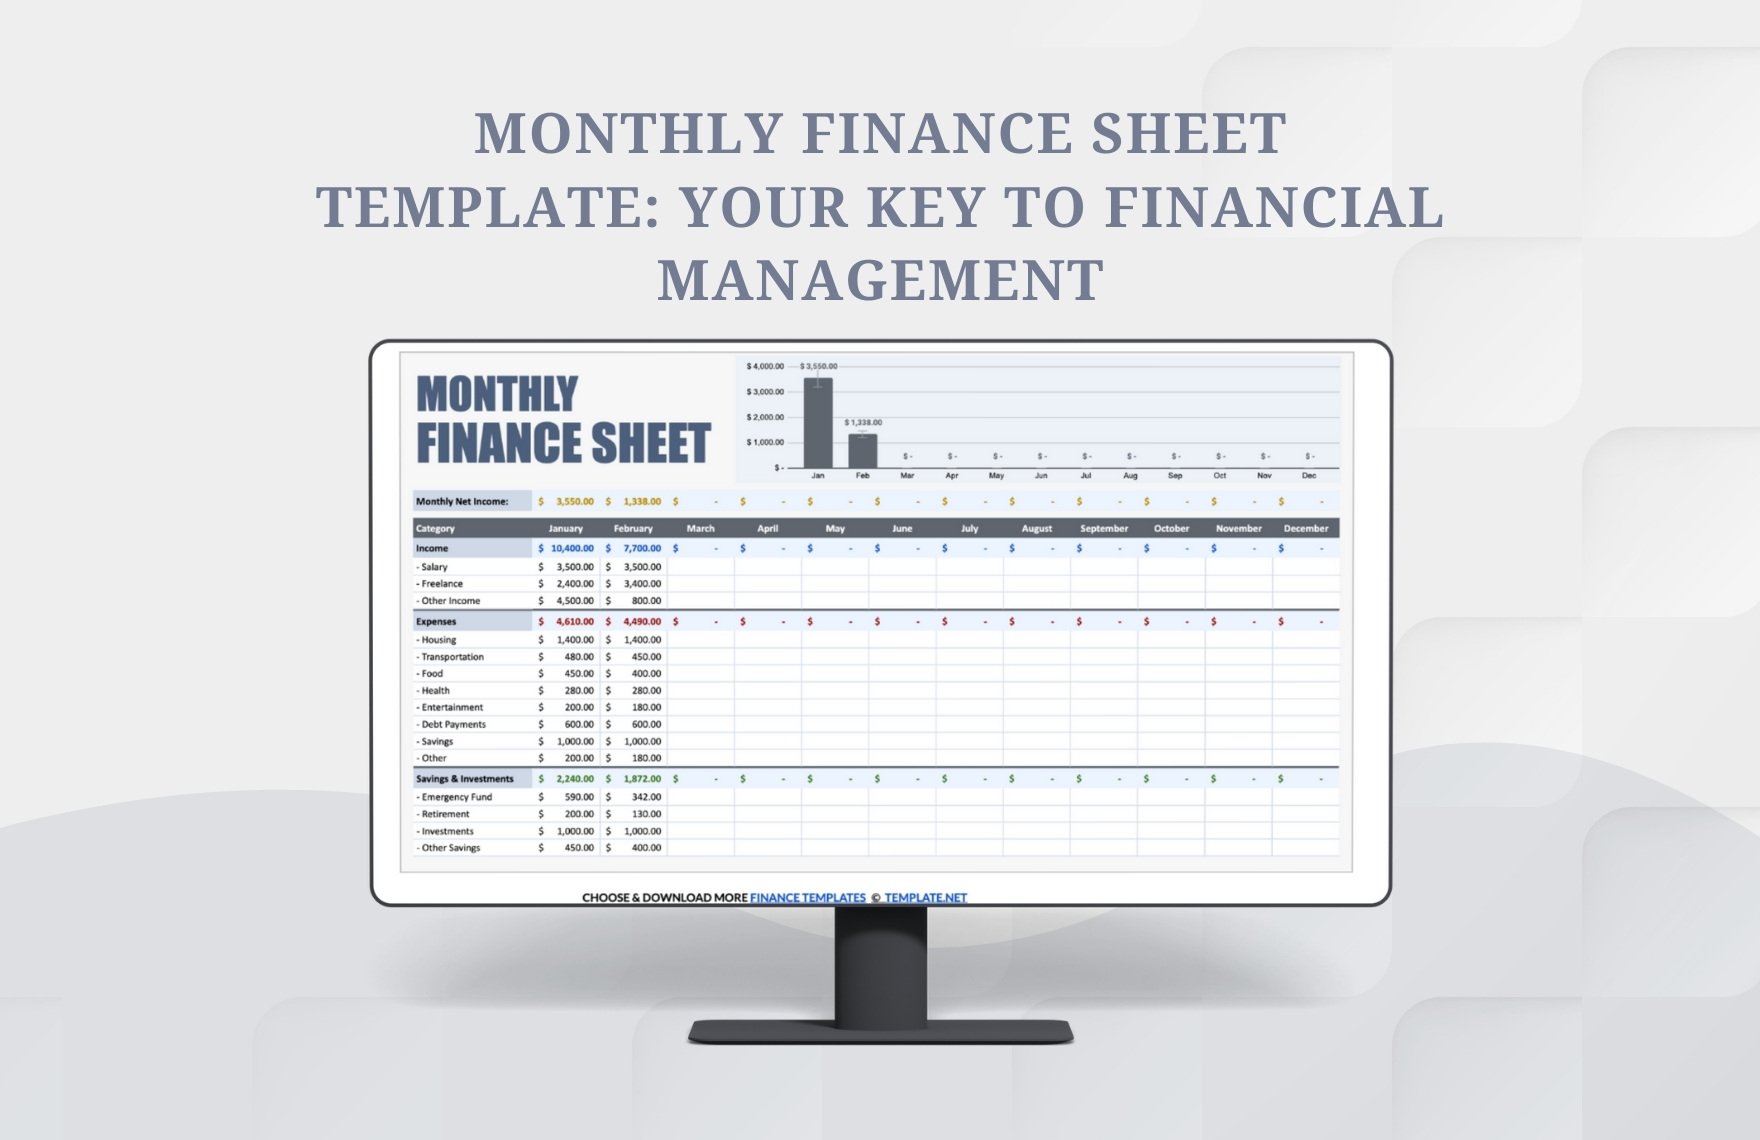
The template has four main sheets. The Dashboard sheet shows your monthly totals at a glance. The Income sheet tracks every source of money coming in — salary, freelance work, side gigs, whatever. The Expenses sheet is where most people spend their time, with preset categories for rent, utilities, groceries, transportation, debt payments, and discretionary spending. The Savings sheet tracks progress toward specific goals like an emergency fund, a vacation, or debt payoff. Everything is formula-driven. You type in your actual numbers and the rest calculates itself. The formulas are straightforward — sums, subtotals, and percentage calculations. There's nothing complex here. One thing the template handles well is the comparison feature. It tracks your actual spending against your planned budget each month and highlights overages in red. This is where it becomes genuinely useful. Most people have no idea they're overspending until the end of the month when the credit card statement arrives. This forces the comparison into real time.
Get the Full Details
A Real Problem I Ran Into
Early on I hit a snag with the expense categorization. The preset categories don't account for irregular or infrequent expenses well — things like annual subscriptions, quarterly insurance premiums, or occasional medical copays. If you try to fit these into monthly buckets, your numbers get distorted. A $1,200 annual insurance payment shows up as $1,200 in one month and zero the rest, which makes that month look catastrophic compared to the others. The workaround is simple and it's not documented anywhere in the template. I added a column called "Adjustment" to the Expenses sheet and entered negative values in months where I'd averaged in an irregular expense, then zeroed it out in the month the actual bill hit. So the insurance gets spread as $100 per month across all twelve, with a -$1,100 adjustment in the month it's actually paid. The monthly totals stay accurate and the yearly sum is still correct. It adds maybe five minutes of work each month but it makes the data honest.
Common Mistakes People Make
The biggest issue I see is people treating the template like it's a tracking tool rather than a planning tool. They fill it in after the fact — at the end of the month when they remember to open it. That defeats the purpose. The comparison feature only works if you enter your planned budget before the month starts, then update actual spending as it happens throughout the month. If you only enter data at month-end, you're just making a spreadsheet version of your bank statement with extra steps. Another problem is category bloat. The template gives you maybe fifteen expense categories to start. Some people create dozens more — "other miscellaneous," "random," "misc 2." When categories get too granular you lose the signal. You're spending more time maintaining the spreadsheet than learning anything from it. Keep it to the core categories and roll everything else into a single "other" bucket. There's also a limitation worth noting: the template doesn't connect to your bank. You have to enter every transaction manually. For some people that's fine. For others it's a non-starter. If you're the type who won't actually log transactions weekly, this tool will fail you regardless of how well-designed it is. In that case, a connected app like Mint or YNAB would be more practical, even though they cost money.
What It Doesn't Do
The free version has no investment tracking, no multi-account support beyond a basic cash summary, no receipt attachment capability, and no mobile app. It's a desktop-centric, single-purpose tool. If you need something that syncs to your bank automatically or sends you alerts when you go over budget, this isn't it. It also doesn't handle joint finances well out of the box. The template is built for individual use. If you're sharing it with a partner, you'll either need to maintain separate entries in the same file (which gets messy fast) or run two parallel copies and reconcile manually. Neither option is ideal. The formulas themselves are basic. There's no conditional formatting beyond the red overage highlighting, no charts beyond the summary bar, and no scenario planning. You can't run "what if" calculations like what happens if you increase your grocery budget by fifty dollars.
Whether It's Worth Your Time
For someone who already has the discipline to track spending weekly and just needs a clean, simple structure, this is solid. It's free, it doesn't require an account, and it runs entirely locally. No subscription, no data mining, no ads. That matters more than it should. For someone who already struggles to maintain any kind of budgeting habit, the manual entry requirement will likely cause this to gather digital dust within three months. The effort-to-insight ratio isn't favorable unless you're already motivated to look at your numbers regularly. The best use case I've found is combining it with a monthly review habit. Every Sunday, spend ten minutes entering the week's transactions. By the time the month ends, you already know where you stand. The template does the math. You just provide the input.