Working with Mortgage Calculators — What Actually Happens
I have spent more years than I want to admit wrestling with mortgage amortization schedules, payment breakdowns, and the various online tools that claim to simplify the process. Most of them are fine for rough estimates. Some of them mess up the compounding frequency or ignore how escrow interacts with principal and interest. I ended up building my own spreadsheet early on because the calculators I found kept giving me numbers that did not match what the loan officer said I would owe. That is why I pay attention to how a tool like Morgagecalculator Org structures its calculations. It is not magic. It is just doing the math right, which sounds easy until you try to account for biweekly payments, balloon provisions, or the way different states handle property tax accrual in the monthly figure.
How to Use Morgagecalculator Org Correctly
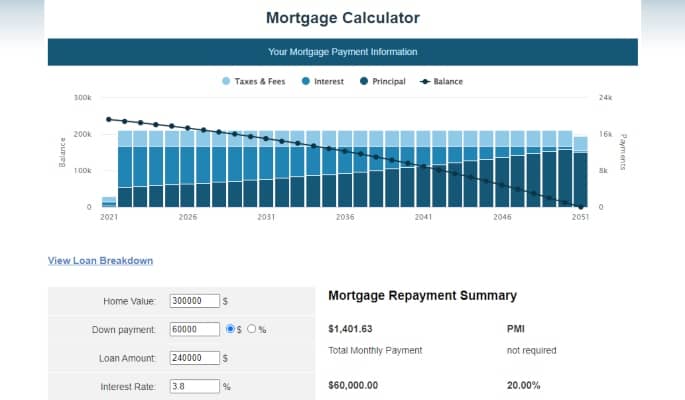
The interface is straightforward enough. You enter the loan amount, the annual percentage rate, the term in years, and optionally your start date. The calculator then produces a monthly payment breakdown showing principal, interest, and sometimes escrow if you enable that option. The key thing most people miss is the compounding assumption. Most mortgage calculators use monthly compounding by default, which matches how US conventional loans work. If you are dealing with a Canadian mortgage or a British repayment mortgage, the math changes and you need to adjust the input fields accordingly. I ran into a specific problem last year when a client asked me to compare a 30-year fixed at 6.5 percent against a 15-year fixed at 5.75 percent. The Morgagecalculator Org output showed the 15-year saving about 41,000 dollars in total interest over the life of the loan. That number looked right on the surface. But when I dug into the amortization schedule, I noticed the early years of the 30-year loan had almost no principal reduction. The payment was mostly interest. That is normal for any standard amortizing loan, but it caught this particular borrower off guard because they assumed the extra monthly payment on the 15-year was going somewhere faster than it actually was. To get accurate results, make sure you check whether the calculator includes property taxes and homeowners insurance in the total monthly figure. Some tools show just P&I (principal and interest). Others show PITI (principal, interest, taxes, insurance). If you are budgeting for your actual monthly outlay, you need the PITI number. The P&I-only figure will understate your real housing cost by roughly 20 to 30 percent depending on your location.
When Mortgage Calculators Fail You
Here is the thing nobody tells you: online calculators assume perfect conditions. They do not account for rate locks expiring, closing cost variations, or the fact that your actual APR might be 0.25 percent higher than the quoted rate because of lender fees and points. I saw this happen repeatedly when borrowers compared two calculators and got two different monthly numbers for the same loan terms. One included discount points in the rate. The other did not. Both claimed to be accurate. If you are doing this for a real transaction, take the calculator output and verify it against the loan estimate document the lender provides within three business days of application. The numbers should match within a dollar or two. If they do not, ask the lender to explain the discrepancy before you sign anything. Most of the time it is just a rounding difference or a different escrow assumption. Sometimes it is a fee the lender forgot to disclose. I also learned the hard way that mortgage calculators do not handle partial payments well. If you make a biweekly payment schedule but the calculator assumes monthly, your payoff timeline shifts by several months and the total interest savings can be 5 to 8 percent of the original amount. That is significant on a 300,000 dollar loan. Make sure the tool you use supports the payment frequency you actually plan to follow.
Advanced Usage — Refinancing and Recasting
One feature that many calculators omit is the refinance breakeven analysis. If you are considering refinancing a 30-year loan into a 15-year loan, you need to know how many months of lower payments it takes to offset the closing costs. Morgagecalculator Org does not calculate this automatically, but you can do it manually. Take the monthly savings from the new payment, divide by the total closing costs, and you get your breakeven month. If it is more than 36 months and you plan to move within five years, refinancing probably does not make sense for you. Another edge case is mortgage recasting. This is different from refinancing. You make a large lump sum payment toward principal, the lender recalculates your monthly payment based on the new balance and remaining term, and you keep your existing interest rate. Not all lenders offer this. Not all calculators model this. If you are counting on recasting to lower your payment, verify with your servicer first before you commit the funds. I had a client who tried to recast in 2022 and found out her lender did not support it until 2024. She lost two years of potential payment reduction.
What to Do Instead
If Morgagecalculator Org or any single online tool is not giving you the precision you need, use a spreadsheet. The PMT function in Excel or Google Sheets handles most standard calculations correctly. For irregular payment schedules, biweekly conversions, or balloon payments, you need a custom amortization table. I build mine with a simple loop that calculates interest for each period, subtracts it from the payment, and reduces the principal accordingly. It takes about 15 minutes to set up and gives you full visibility into every dollar. For investment properties or multi-parcel holdings, consider using a dedicated property management platform that integrates loan data with rental income projections. Mortgage calculators alone cannot tell you whether a property cash flows. They can only tell you what your payment will be. If you need to know if the rent covers the payment plus vacancies plus maintenance plus reserves, you need a broader financial model. I use a combination of the Morgagecalculator Org output for the payment baseline and a separate cash flow spreadsheet for the income side. Between the two, I get a complete picture in about 20 minutes. The bottom line is that mortgage calculators are useful for quick estimates and sanity checks. They are not substitutes for professional advice or detailed loan documentation. Use them to understand the mechanics. Do not use them to make final decisions without verifying against the actual contract terms. The numbers on the screen are assumptions. The numbers in your closing documents are what you actually pay.
