How Mortgage Payments Actually Work in Practice
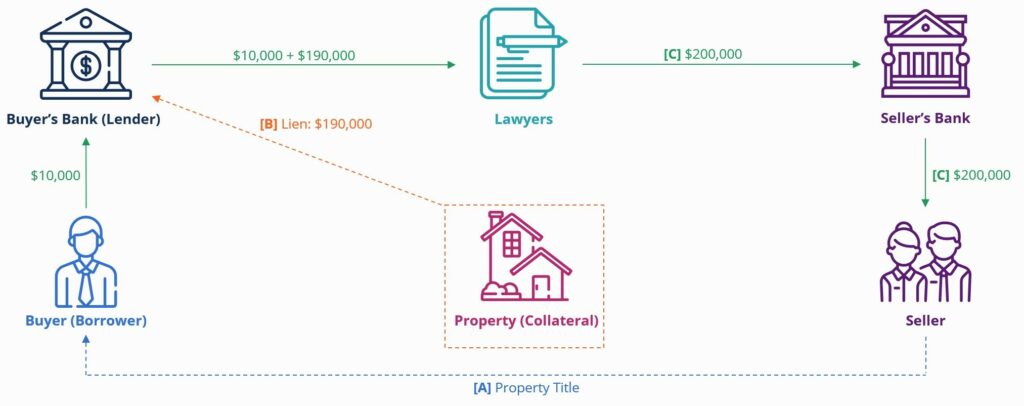
Most people think a Mortgage is just a loan. It is not. It is a complex debt instrument wrapped around real estate, governed by state law, and serviced by systems that have barely changed since the 1990s. The basic mechanics are simple enough — you borrow money, you pay it back with interest over time, and the house serves as collateral — but the details matter when you are actually dealing with one.What is a mortgage, technically? It is a secured loan. The promissory note represents your obligation to repay. The deed of trust or mortgage document gives the lender a lien on the property. If you default, the lender can initiate foreclosure. Two separate documents, two different legal instruments depending on your state. Some states use deeds of trust with a power of sale clause, which makes foreclosure faster and cheaper for the lender. Other states require judicial foreclosure through the court system. Know which one applies to you before you sign anything. When I was processing loans back when I actually did this, the standard timeline people quoted was 30 to 45 days from application to closing. That was the textbook answer. In reality, it was usually 45 to 75 days, and I can tell you exactly why. The gap is not in the underwriting. It is in the third-party services and the waiting periods between them. Here is what nobody tells you about the order of operations. The appraisal comes after the underwriting conditional approval, not before. You apply, you get pre-approved, then the appraiser shows up, then underwriting reviews everything including the appraisal, then conditions come back, then you clear conditions, then closing is scheduled. Each step has dependencies. If the appraisal comes in low, you are not just renegotiating the price — you are restarting parts of the underwriting review because the loan-to-value ratio has changed. That adds 5 to 10 days minimum.
I remember one file where the borrower had a self-employment history of exactly two years, which met the standard overlay requirement, but their 1040 schedules showed a deductible expense that the automated underwriter flagged as a potential income adjustment. The file sat in limbo for eleven days while the underwriter and the processor went back and forth trying to determine whether the expense was a legitimate business deduction or something that required an add-back. We resolved it by pulling the bank statements and showing the cash flow actually supported the income despite the deduction. Eleven days wasted on a question that should have been answerable on day one. This happens more often than you would think.
Breaking Down Your Monthly Payment
Your monthly payment is not just principal and interest. The standard PITI breakdown includes Principal, Interest, Taxes, and Insurance. The principal and interest portion goes toward paying down the loan balance and covering the lender's cost of funds. The taxes and insurance are held in an escrow account by the lender and paid out when they come due. This is not optional if your down payment is less than 20 percent. Lenders require escrow to protect their collateral. Property taxes and homeowner's insurance are priorities — if those go unpaid, the house can be lost to a tax sale or left uninsured after a storm, and the lender's security interest is compromised either way. Here is something most borrowers do not understand about how the interest is calculated. Mortgage interest is computed on a daily basis using a method called amortization with daily accrual. Your payment is applied on the first of the month, but the interest accumulates every single day from your last payment. This means the timing of your closing date relative to the first of the month has a real financial impact. If you close on the 28th instead of the 3rd, you are paying more in prepaids at closing but your first full payment does not come due until the following month, giving you a longer period between when you start owning the home and when your first real payment hits. Conversely, closing early in the month means you owe a larger partial-period interest charge upfront but your regular payments start sooner. The difference is usually a few hundred dollars in total, but it is something people debate in forums endlessly without understanding the math behind it. Another detail that gets glossed over — and I cannot stress this enough — is the relationship between your credit score and your rate class. Mortgage lenders do not price loans to the exact decimal of your credit score. They group scores into bands. Moving from a 680 to a 700 might drop you from one rate tier to another. Moving from 700 to 720 might do absolutely nothing. The brackets vary by lender and by loan type. An FHA loan has different credit score thresholds than a conventional conforming loan. A jumbo loan has its own. If you are working to improve your rate, check what the next threshold is rather than assuming linear improvement.
Get the Full Details

The Escrow Analysis Trap
Every year, your lender is required to perform an escrow analysis. They review what actually went out of the account versus what you have been paying into it. If the actual disbursements exceed what you contributed, you get shorted, and the lender will adjust your monthly payment upward to make up the difference. This is one of the most common sources of surprise for homeowners. Property tax assessments go up, insurance premiums go up, and your payment goes up with them. Sometimes the shortage is large enough that you also owe a lump sum to cover the deficit, capped at no more than a month's worth of payments depending on the servicer. I once worked a file where the borrower's annual escrow analysis showed a shortage of over $800. The reason was not rising taxes. It was that their homeowner's insurance premium had jumped because the property was located in a newly designated flood zone. FEMA had redrawn the flood maps, and the lender required flood insurance, which the borrower did not previously have. The monthly payment increased by roughly $60. The borrower was furious and confused because they had never been told about the flood zone change. This is the kind of thing that slips through cracks. When you close on a home, verify the flood zone status yourself rather than relying solely on the lender's determination. The lender's flood certification is a formality, not a guarantee that the zone is accurate.
Types of Mortgage Loans and What Actually Matters
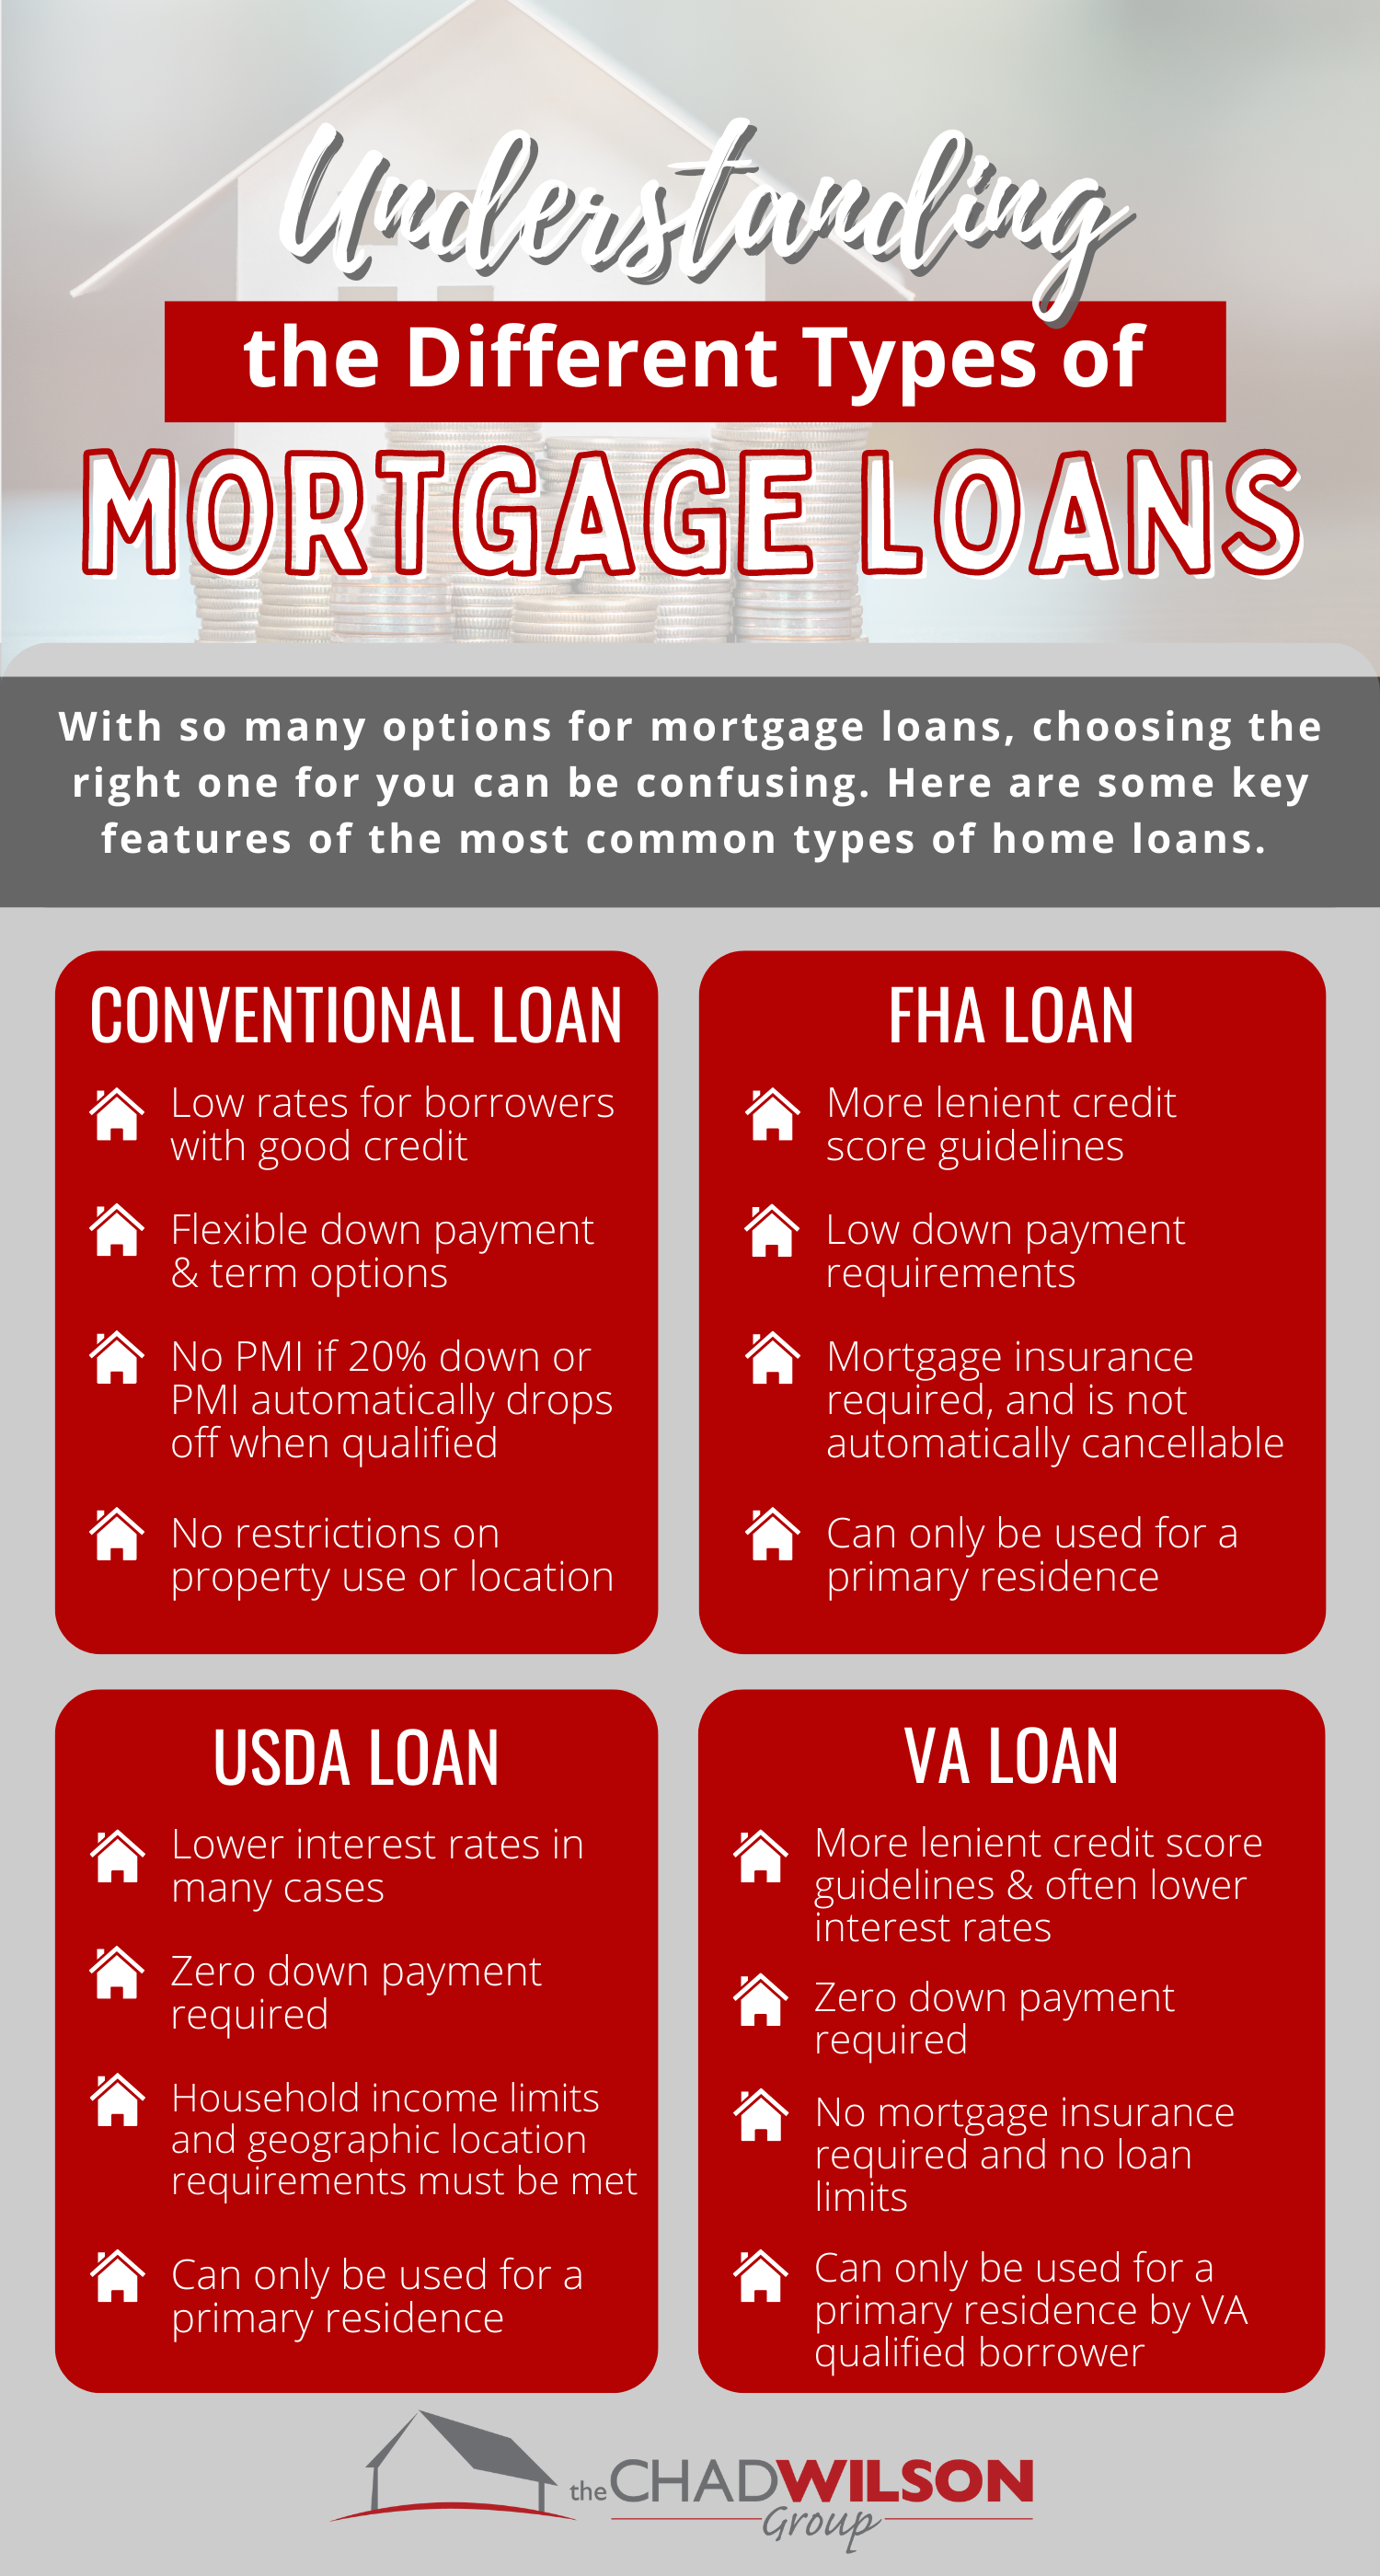
There are several categories, but the main ones you will encounter are Conventional, FHA, VA, and USDA. Conventional loans are not government-backed and follow Fannie Mae and Freddie Mac guidelines. FHA loans are insured by the Federal Housing Administration and require mortgage insurance premiums regardless of your down payment. VA loans are guaranteed by the Department of Veterans Affairs and require no down payment and no mortgage insurance for qualified veterans. USDA loans are for rural and suburban areas and also require no down payment, but come with income limits and geographic restrictions. The counter-intuitive part that most first-time buyers miss is that FHA is not always the worse deal even with the double mortgage insurance structure. An FHA 3.5 percent down payment loan might have a slightly higher interest rate than a conventional loan requiring 10 percent down, but the total monthly outlay can be lower because your required down payment is smaller. The monthly mortgage insurance premium on FHA is upfront (financed into the loan) plus an annual premium divided into monthly installments. On a conventional loan with less than 20 percent down, private mortgage insurance is required but drops off automatically once you reach 22 percent equity based on the original amortization schedule, or earlier if you request cancellation at 20 percent. FHA mortgage insurance lasts for the life of the loan if you put less than 10 percent down, or for 11 years if you put 10 percent or more. That longevity is a significant cost difference over a 30-year term that does not show up in a side-by-side rate quote. ARMs, or adjustable-rate mortgages, deserve a more honest assessment than they typically get. A 5/1 ARM means the rate is fixed for five years, then adjusts once per year thereafter. The initial rate is almost always lower than a comparable 30-year fixed. For people who plan to sell or refinance within five years, an ARM can save meaningful money. The problem is that most borrowers who take out an ARM do not actually plan to move in five years. They assume they will just ride it out. When rates rise, your payment increases. I have seen monthly payments jump by $400 to $600 on a $400,000 loan after the first adjustment in a rising rate environment. That is not theoretical. It happened in 2022 and 2023 to a significant number of ARM holders.
Locking Your Rate
Rate locks are not set-and-forget. When you lock a rate, the lock is valid only for a specified period, usually 30, 45, or 60 days. If your closing is delayed beyond that period, the lock expires and you either re-lock at the current rate or go float. Re-locking at a higher rate is a genuine risk, especially during volatile markets. Some lenders offer lock extensions, but they charge a fee. I have seen extensions run anywhere from 0.25 to 0.5 percent of the loan amount, which on a $350,000 loan is $875 to $1,750. There is a strategy most people do not know about called a float-down option. Some lenders offer this as part of your rate lock. If you lock a rate and then market rates drop before closing, you can request a new, lower rate. The trade-off is that the initial lock rate might be slightly higher than the standard lock to compensate the lender for this flexibility. It is worth asking about if you are concerned about rate movement during your closing window. If rates fall and you do not have a float-down, you are stuck. If you do have it and rates stay flat or rise, you paid a small premium for nothing. Use it only if you think there is a real chance of rates moving in your favor.
When Things Go Wrong
Loan denials happen, and the reasons are rarely what people expect. The most common denial reasons are debt-to-income ratio, insufficient reserve funds, and employment verification gaps. But the weird ones are the ones that derail files unexpectedly. A borrower might have a perfectly clean application and then get denied because a recent hard inquiry appeared on their credit report, pushing their debt utilization slightly above the threshold. Or their bank statement shows a large deposit that cannot be properly documented as a gift, and without gift documentation, the underwriter treats it as undisclosed income and questions the source of every similar deposit, which balloons the review timeline. Here is the practical workaround for the deposit issue that actually works. Before you apply, pull your bank statements for the most recent 60 to 90 days and highlight any deposit over $500. Do not wait for the underwriter to ask. Proactively provide a paper trail for those deposits — a gift letter from the donor, a canceled check showing the transfer, a settlement statement from a prior home sale. A gift letter needs to include the donor's name, address, relationship to you, the amount of the gift, and a statement that the funds are not a loan. Your lender will provide a template, but having the information ready before they ask speeds things up considerably. The other practical issue that is worth addressing head-on is the appraisal gap. If the appraisal comes in below the contract price, the lender will only loan based on the appraised value. That means your down payment requirement increases because the loan amount is now smaller relative to the purchase price. You have three options: renegotiate the price with the seller, bring additional cash to closing to cover the gap, or walk away if you have an appraisal contingency. The third option is the safest but not always available if the market is competitive and the seller will not budge on price.
A Note on What Mortgage Will Not Do for You
Mortgages are often presented as the primary tool for building wealth through homeownership. They are a tool, but they are not a wealth-building strategy in isolation. The cost of borrowing, transaction costs like closing costs typically running 2 to 5 percent of the loan amount, and the time value of money mean that buying and selling a home repeatedly is expensive. Every transaction eats into your equity. Property taxes, maintenance, and insurance are ongoing costs that do not disappear. The classic rule of thumb that buying is better than renting long-term is statistically true but depends heavily on how long you stay in the property and local market conditions. In markets where prices stagnate or decline, the math reverses. I have seen it happen in several Sun Belt cities between 2020 and 2023 where rapid price appreciation was followed by corrections that left owners underwater for extended periods. If you are shopping for a Mortgage, the single most important thing you can do is get multiple quotes from at least three different types of lenders — a national bank, a credit union, and a local mortgage broker or regional lender. The rate differences between lenders on the same loan program can be 0.25 to 0.75 percent or more, and that translates to thousands of dollars over the life of the loan. Do not assume the bank where you already have a checking account is your best option. Do not assume the broker quote is always lower. Compare the Loan Estimate forms line by line, not just the interest rate. Points, origination fees, and other lender credits can distort the apparent rate. Look at the total closing cost column and the annual percentage rate, which factors in more of the true cost than the nominal interest rate alone.