How Mortgage Acceleration Actually Works (Before You Trust Any Tool)
A mortgage acceleration strategy is simple on paper: you make extra payments that are applied directly to principal, which reduces the interest that accumulates over time, which in turn lets you pay off the loan faster. The math is basic compound interest. The problem is that most people who try this either don't understand how their servicer applies payments, or they use a tool that gives them false confidence because it ignores real-world frictions. I spent about three years running these calculations for clients before I stopped trusting most of the online calculators I found. Here is what actually matters.
Mortgage Acceleration Calculator: How to Use One Without Getting Misled
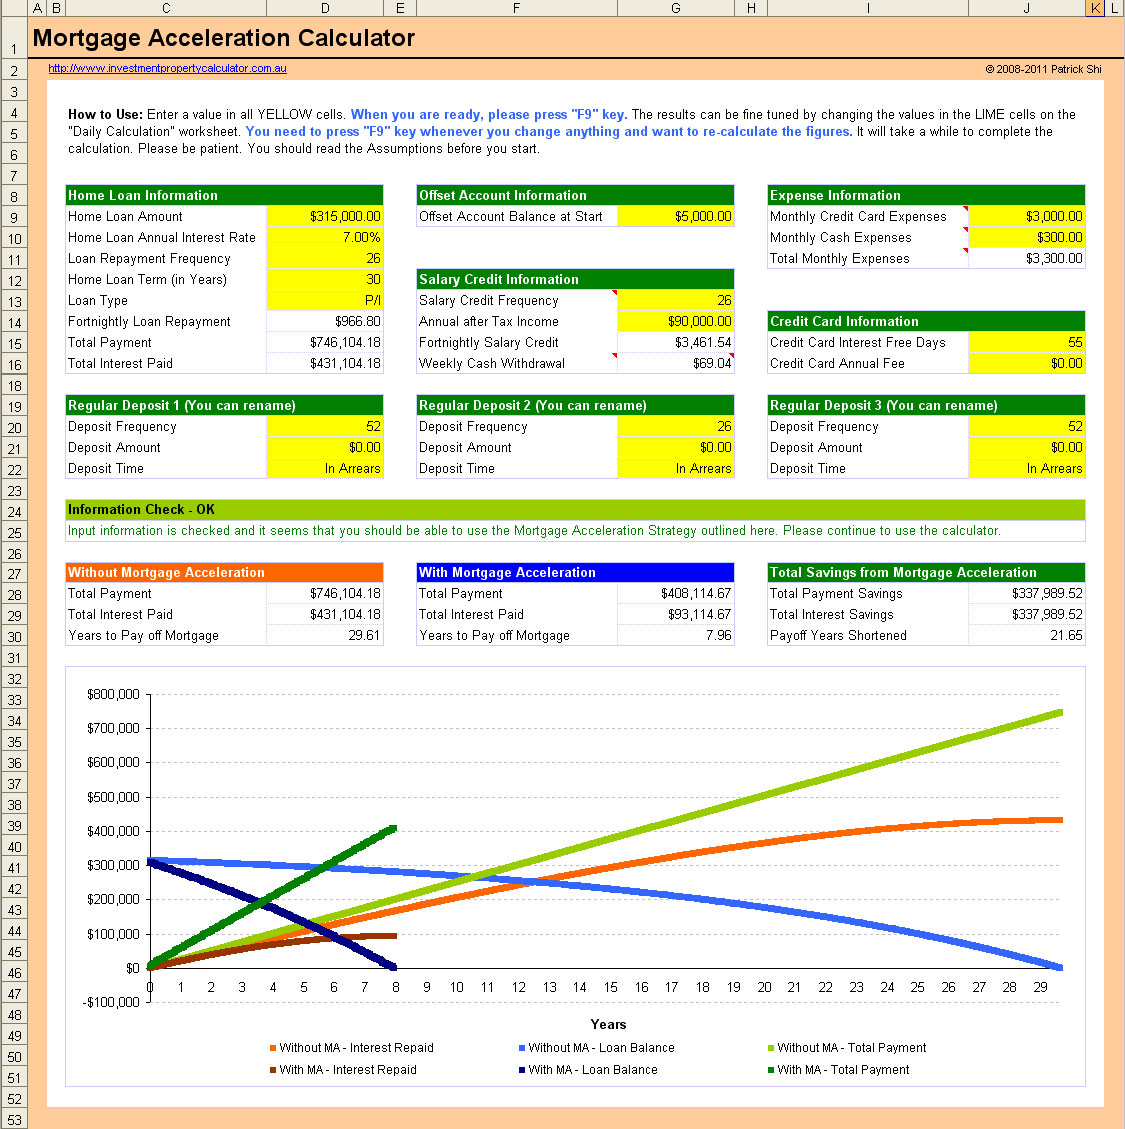
The basic inputs are your remaining balance, your interest rate, your current monthly payment, and the extra amount you want to apply each month. A proper calculator will then show you the new payoff date and total interest savings. Most of them stop there, which is where things go wrong. What most calculators omit: whether your loan actually allows extra principal payments without a prepayment penalty, how your servicer processes biweekly versus monthly extra payments, and whether your loan has an ARM that could reset your rate before you see any meaningful acceleration. I had a client last year who ran the numbers on a free calculator and committed to paying an extra $400 monthly. His loan had a 2% prepayment penalty on the first five years, which erased roughly $3,200 of the projected savings almost instantly. He found out when his servicer sent him a revised statement. The workaround was straightforward. Before running any acceleration plan, pull your original promissory note and look for a prepayment clause. If it says anything about penalties or yield-maintenance fees, factor that into your calculation manually. Free calculators will not do this for you.
Another thing to verify: does your servicer actually apply extra payments to principal on the same day, or do they hold them in suspense until your next due date? I have seen this happen repeatedly with portfolio servicers. If your extra payment sits in limbo for twelve days, it is not accelerating anything during that window. You can call your servicer and ask specifically how they apply surplus payments. If they give you a vague answer, assume the worst and plan accordingly.
Get the Full Details

The Mechanics Behind the Numbers
Here is the core mechanic that beginners miss. When you make an extra principal payment, the interest for that month is recalculated on the new, lower balance. The next month's interest charge drops. That is the acceleration. But the reduction is front-loaded and decays over time because you are always paying interest on whatever balance remains. This means the early years of a 30-year loan at 6.5% are where extra payments hit hardest. Paying extra in year 20 does very little compared to year 3. Biweekly payment programs, which are heavily marketed, work on the same principle but add a structural quirk. Instead of twelve monthly payments, you make twenty-six half-payments per year, which equals twelve full payments plus one extra payment annually. The math checks out. The problem is that many biweekly programs charge a setup fee of $200 to $500 and a monthly processing fee of $5 to $15, which can eat into your savings for the first two or three years. Doing this yourself by splitting your payment in half and paying every two weeks on your own schedule costs nothing extra and produces the identical result. There is also the issue of rounding. Some servicers round your interest calculation to the nearest cent at each cycle, which creates tiny discrepancies over decades. A well-built calculator accounts for daily interest accrual, which is how most servicers actually compute charges. If your calculator uses monthly compounding only, its projections will be slightly optimistic. Not wrong enough to matter much, but wrong enough to note.
When a Mortgage Acceleration Calculator Is Useless
These tools break down in a few specific scenarios. If you have a government-backed loan with a VA or FHA streamlining refinance option, the calculator cannot account for the closing cost tradeoff of refinancing to a shorter term. Running extra payments against a 30-year while qualifying for a 15-year refinance at a significantly lower rate is almost always the better move, but no standard acceleration calculator will tell you that. You have to compare it yourself. Another edge case: loans with escrow shortages or insurance premiums that creep upward. Your total monthly outlay might stay the same while a growing chunk goes toward escrow instead of principal, silently undermining your acceleration. I saw this with a client in Ohio whose homeowners insurance jumped from $1,200 a year to $2,800 in three years. His escrow shortage ate up what he thought was an extra $200 going toward principal. The calculator showed one thing. His actual statement showed another. ARM loans are the third scenario where calculators fail you. An initial rate period followed by adjustments means your payment can change in year 7 or year 10 regardless of what you throw at principal. An acceleration calculator assuming a fixed rate for the full term will dramatically overstate your savings on an adjustable product.
Building a Reasonable Projection Yourself
If you want to avoid trusting a random website with your financial data, you can build this in a spreadsheet. Set up columns for payment number, beginning balance, interest portion, principal portion, extra payment, and ending balance. Use the formula =PPMT for the principal portion and =IPMT for the interest portion, both based on your rate divided by twelve and your total number of payments. Add your extra payment to the principal column each month. Copy the formula down. You will see the balance drop faster in the early years and slower toward the end, which matches reality. This approach takes about twenty minutes for someone who has never built an amortization schedule, and about five minutes after the second one. It also forces you to enter every variable yourself, which means you cannot accidentally skip the prepayment penalty question or the escrow adjustment. A downloaded template does the same thing but saves you the assembly time. Look for one that uses daily interest accrual rather than simple monthly compounding, and one that lets you add a column for irregular extra payments since life does not always allow the same amount every month.
The Honest Bottom Line
Mortgage acceleration works. It is mathematically sound and it saves money. But it is not a strategy that benefits everyone equally, and the tools that claim to guide you are often incomplete. The people who get the best results are the ones who verify their loan terms first, build or choose a calculator that accounts for real-world details, and understand that the biggest gains come from acting early and staying consistent. If your rate is above 7%, accelerating is almost always worth it. Below 4%, the opportunity cost of tying up cash in home equity becomes a real question that a calculator alone cannot answer.