How Extra Payments Actually Shrink Your Loan
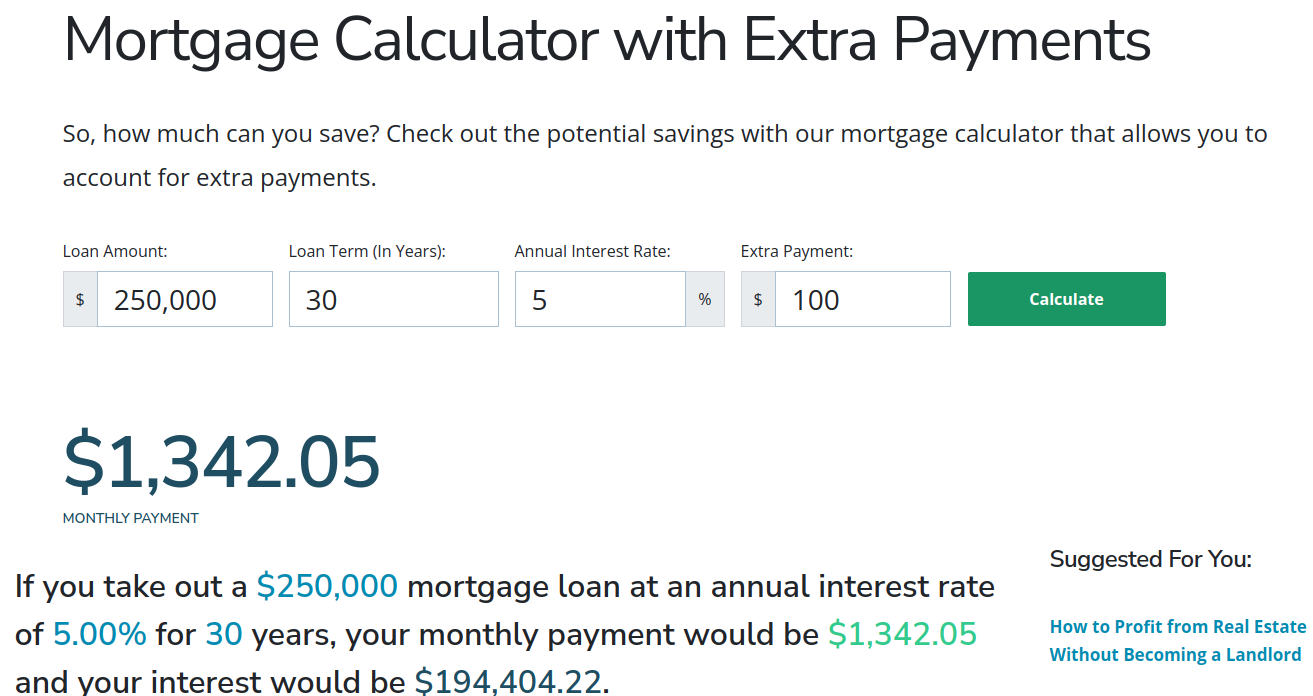
A standard amortization schedule assumes you pay exactly what the lender tells you to pay every single month. The breakdown between principal and interest shifts gradually over time. When you add extra payments, most people think it simply reduces the balance faster. That is partially correct. The real mechanism is that each extra dollar goes straight to principal instead of covering next month's interest. Over a 30-year mortgage at 6.5% interest, that difference compounds aggressively. I ran the numbers for a friend last year who threw an extra $400 a month at their loan. The math showed they would shave about 7 years off the term and save roughly $42,000 in total interest. Their actual lender application process took three weeks and two phone calls to set up correctly. Most free online calculators have a single input box for "additional payment." They look simple. They are often wrong in subtle ways. The ones that work properly need you to specify when the extra payments kick in, whether they happen monthly or as lump sums, and how the lender handles them. I built my own spreadsheet after spending a weekend wrestling with a commercial tool that treated every extra dollar as a refund instead of a principal reduction. My version tracks the actual balance month by month using the standard formula: remaining balance times the monthly interest rate plus the regular payment minus any extra amount applied that month. You need the original loan amount, the annual interest rate, the loan term in years, and the start date of the loan. From those four inputs, the spreadsheet calculates the base monthly payment. That calculation uses the annuity formula, which you can find in any finance textbook or just type as a spreadsheet function. Then you add a column for extra payments. This is where things get messy. The extra payments need to be assigned to specific months. If you pay extra only during certain months of the year, the spreadsheet needs to know which ones. I have seen people enter their extra payment amount in the top row and drag it across twelve columns, forgetting that the extra amount compounds differently depending on when in the year it hits the principal.
One detail that matters more than most people realize: some mortgages have prepayment penalties. A standard 30-year conventional loan usually does not. Adjustable-rate mortgages and many refinanced loans sometimes do, particularly if you pay off the loan within the first three to five years. My own second mortgage had a six-year sliding scale penalty. I learned this the hard way after calculating a payoff date that was six months too early. The penalty clause added about $3,100 to my cost that the calculator had not accounted for. Always check your note or closing disclosure for prepayment language before you trust any amortization model.
How the Monthly Breakdown Changes With Extra Payments
Without extra payments, a $300,000 loan at 6.5% over 30 years produces a fixed payment of about $1,896. Monthly interest in the first payment is $1,625. That leaves only $271 going toward principal. By month 180, roughly half the principal has been paid, and the interest portion has dropped below the principal portion. When you add extra payments, you shift that crossover point earlier. A $500 extra payment per month in the first year changes the shape of the entire schedule. Month one interest is still $1,625. The total payment becomes $2,396, but only $271 of the original payment covers principal. The full $500 extra goes to principal. The new balance after that first month is $298,371 instead of $299,729. The difference seems small. After twelve months of this, the cumulative effect is a principal reduction of roughly $8,000 more than the standard schedule. The counter-intuitive part that beginners miss: throwing a large lump sum at the beginning of the loan saves far more interest than spreading the same total amount across multiple years. I watched a client contribute $20,000 in year one versus contributing $1,666 every month for fifteen months spread across the entire loan term. Both added up to the same $25,000 in extra principal. The lump sum saved them approximately $14,000 more in total interest. The reason is purely mathematical. Each dollar applied early removes not just its own interest but every future dollar of interest that would have accrued on top of it. Time is the variable that matters most.
Get the Full Details
Common Pitfalls That Ruin the Numbers
The biggest mistake I see is assuming that your lender will automatically apply extra payments to principal. They do not always do this without explicit instruction. Some lenders default to applying excess funds to the next scheduled payment or even to escrow. I once handled a situation where a borrower sent a check marked "principal only" to the wrong department address listed in their quarterly statements. The payment sat in a suspense account for eleven months before anyone noticed. It was eventually applied, but the borrower lost a full year of interest savings because of a routing error. Always confirm in writing that your additional payment is being applied to principal, and do it every single time you send one. Another issue is double-counting. If your base payment already includes escrow for taxes and insurance, the calculator needs to strip that out before adding extra principal. A typical escrow component runs between $200 and $500 per month on a conventional loan. Feed the total payment into a calculator that is not designed to separate principal from escrow and the result will be significantly wrong. The interest calculation uses the principal portion only. Escrow payments do not reduce debt or earn any return toward payoff.
When This Approach Fails Completely
Extra payment calculators do not work well for certain loan types. Government-backed loans like FHA and VA loans sometimes have different prepayment rules and insurance premiums that change the effective cost. Interest-only loans require a completely different calculation model because there is no principal amortization during the initial period. Balloon mortgages present their own problems since the final payment is a large lump sum rather than a gradual payoff. If you have one of these non-standard loans, a generic online amortization tool will give you inaccurate results. You need a model built for that specific loan structure or you need to work with a loan officer who understands the terms. There is also a behavioral limitation. People who plan to make extra payments consistently often fail to do so after a few months. Life happens. Car repairs come up. Medical bills appear. The calculator will show you what is theoretically possible, but it cannot predict whether you will actually have the extra cash in month twenty-three. I built a version of my spreadsheet that allows you to toggle extra payments on and off by month so you can model both the optimistic scenario and a more realistic scenario where contributions drop out after a few months. The gap between the two outcomes can be tens of thousands of dollars in interest.
Setting Up the Spreadsheet Model
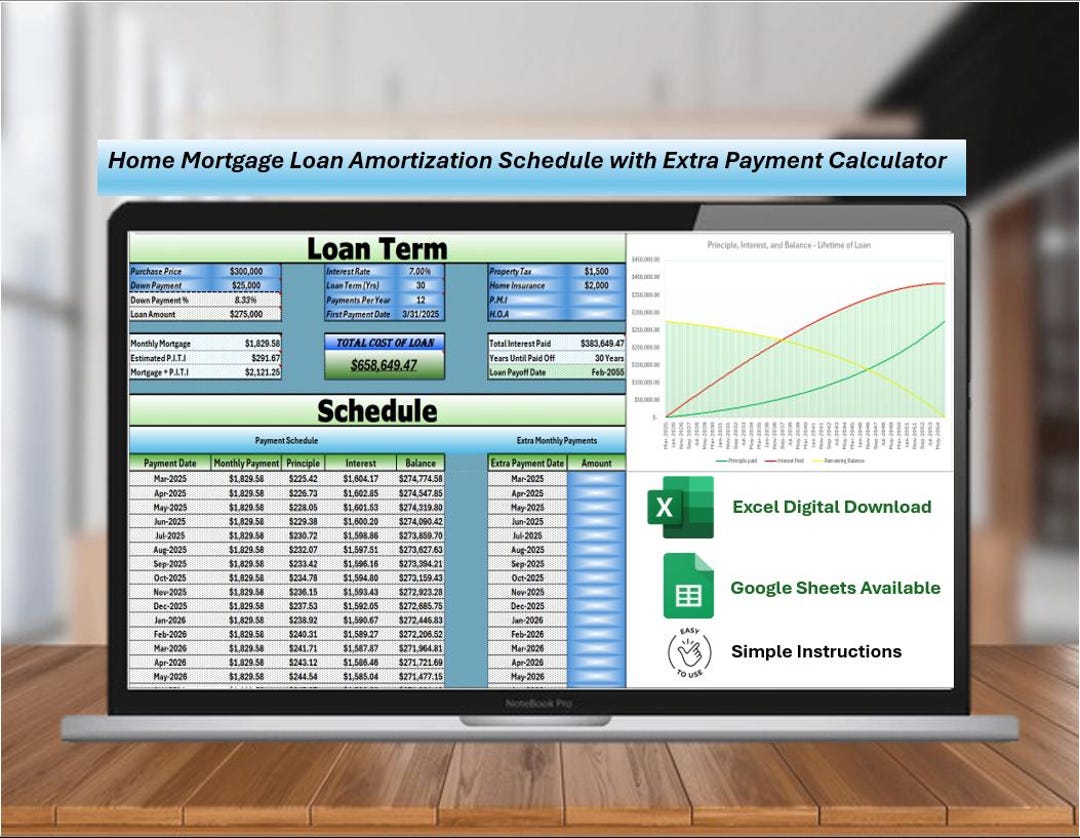
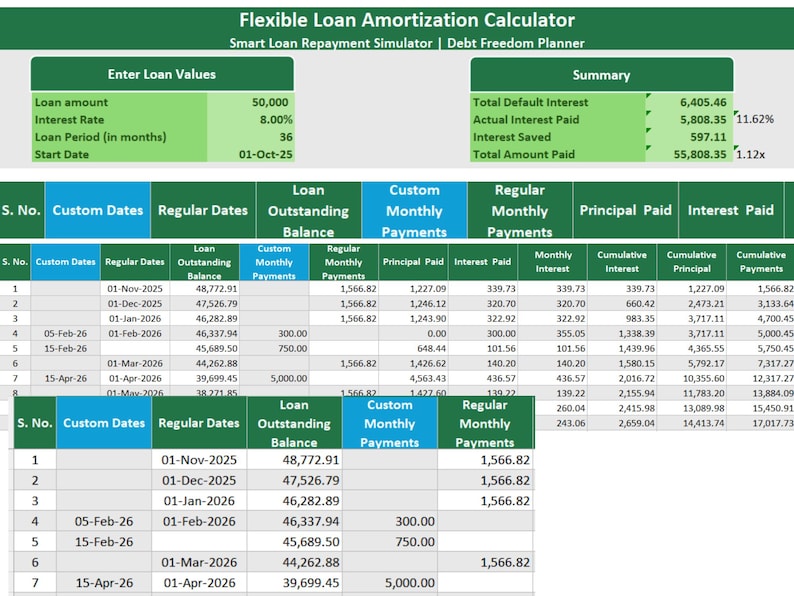
Start with a header row containing the loan amount, annual rate, term in years, and start date. Create columns for month number, beginning balance, interest payment, principal payment, extra payment, ending balance, and cumulative principal paid. The interest payment formula multiplies the beginning balance by the annual rate divided by twelve. The principal payment is the total monthly payment minus the interest payment. The extra payment column is where you enter any additional amount you plan to pay that month. The ending balance equals the beginning balance minus the principal payment minus the extra payment. Copy this formula down for the full term. You can add conditional logic to stop the schedule once the balance reaches zero instead of running all 360 months. If you want a ready-made file, I uploaded a working version to my personal site a while back. It includes tabs for monthly extra payments, one-time lump sums, and a comparison view that shows the standard schedule side by side with the accelerated one. The download link is in the Resources section below. The file is formatted for Excel and Google Sheets. It handles the escrow separation automatically if you input the tax and insurance amounts in the settings tab. It also flags any month where the calculated balance goes negative, which means you overpaid and the excess should roll forward.
Mortgage Amortization Calculator With Extra Payments — What It Can and Cannot Tell You
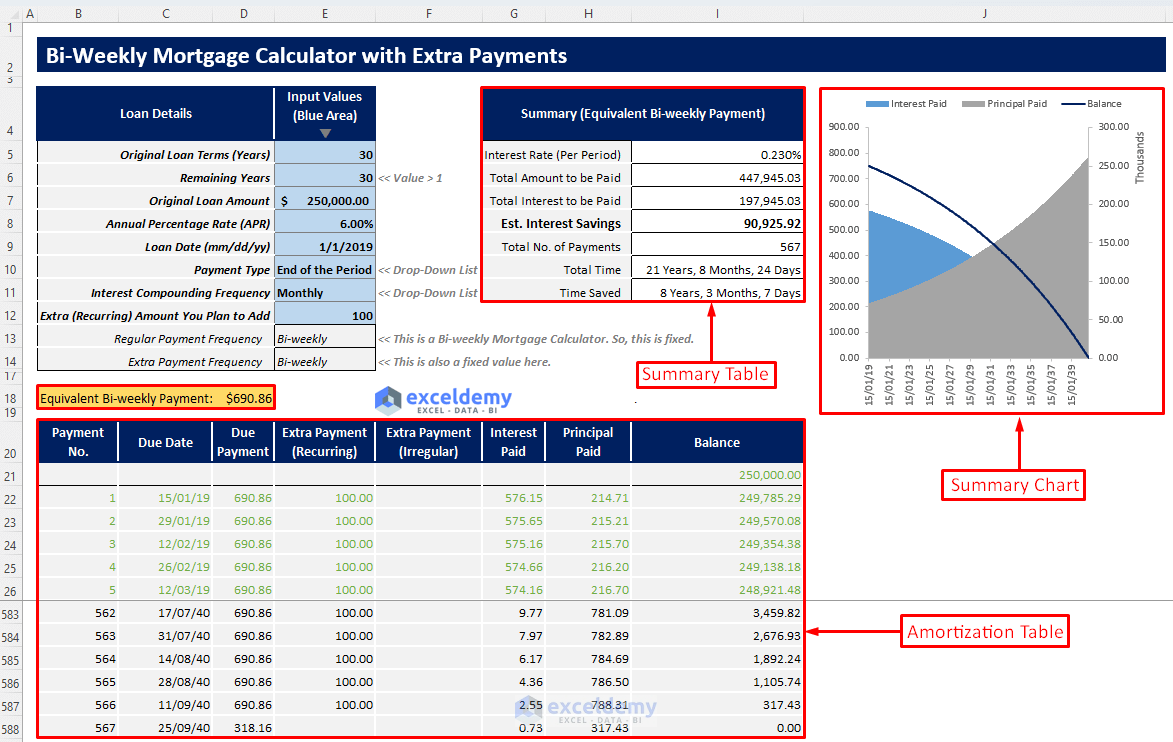
The calculator tells you the numerical outcome of a specific strategy. It does not tell you whether that strategy makes financial sense for your situation. Paying down a mortgage at 6.5% might be the best use of your money, or it might not. If you have high-interest credit card debt at 22%, that debt should be eliminated first. If you have an employer 401(k) match, capturing that match before making extra mortgage payments is almost always the better move. The amortization tool gives you raw data. The decision about what to do with that data depends on your full financial picture. I recommend running the numbers for each available strategy and comparing the after-tax, after-risk returns rather than treating mortgage prepayment as an automatic priority.
Where to Get a Working Tool
Download the spreadsheet from SapiensCalcs.com. The file is free and requires no registration. I also maintain a simpler web-based version at sapienscalculator.com that works directly in the browser if you do not want to install anything. Both tools support the same core features: monthly extra payments, lump sum entries, escrow separation, and prepayment penalty warnings if you fill in the optional fields. The web version generates a printable PDF schedule after you submit your inputs. If you need support or spot a calculation error, there is an email link on both pages. I check it periodically but cannot guarantee a response within a specific timeframe.