How To Build A Mortgage Amortization Schedule With Additional Principal Payments
Most spreadsheets people use for mortgages assume you only make the scheduled payment every month. That is fine if you never want to pay extra. The moment you start throwing extra principal at the loan, everything shifts. Your regular payment stays the same but the interest portion shrinks faster and the payoff date moves forward. Here is how to handle it without spending six hours wrestling with Excel formulas.Setting Up The Base Schedule
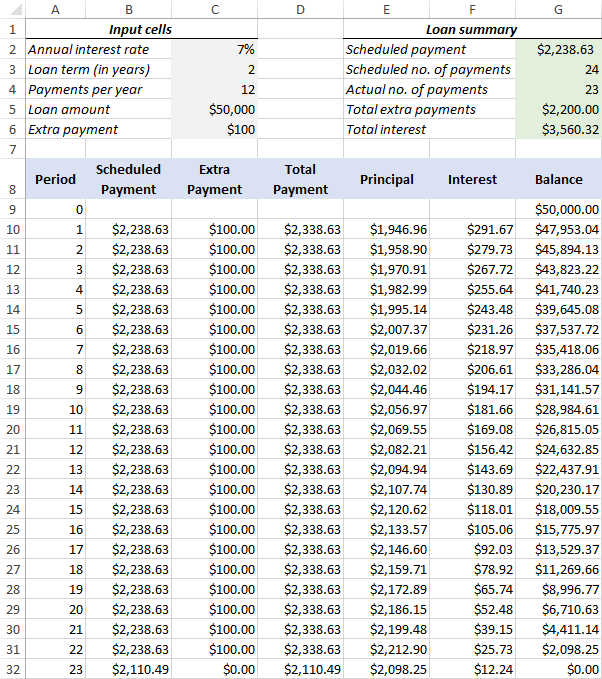
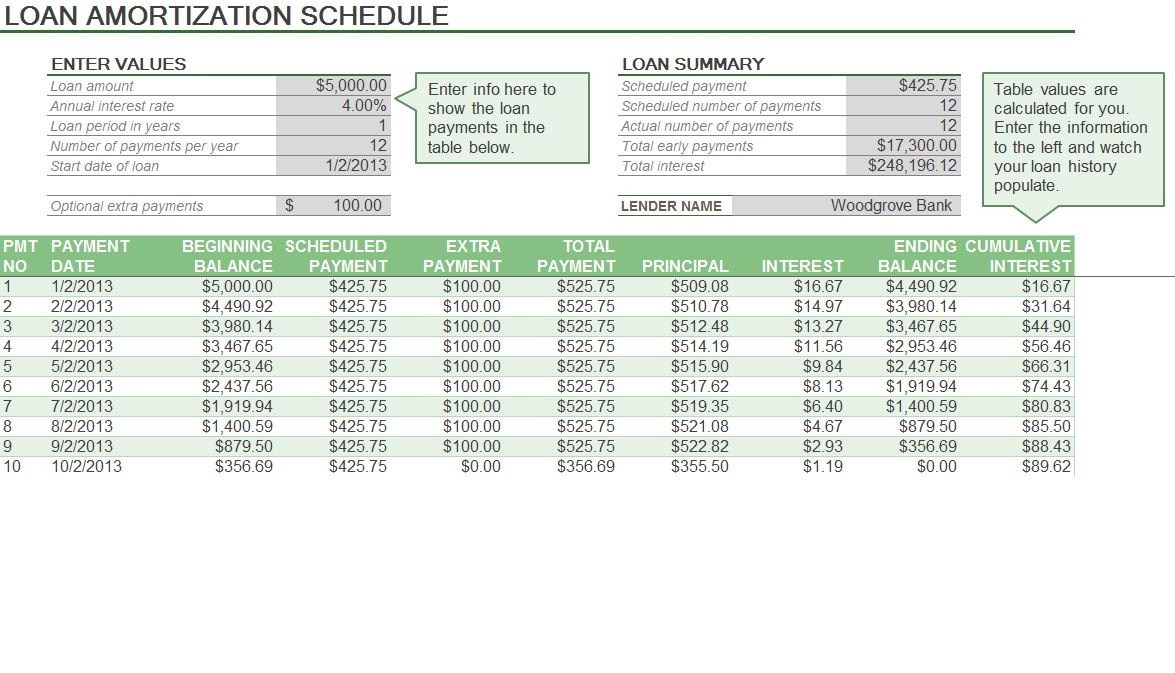
Start with a standard amortization table. You need these columns: payment number, beginning balance, total payment, interest portion, principal portion, and ending balance. The interest portion for any given month is simply the beginning balance multiplied by the monthly interest rate. The monthly rate is your annual rate divided by 12. Subtract the interest from your total payment and what remains is the principal portion. Subtract that principal portion from the beginning balance and you get the ending balance. Repeat for every month until the balance hits zero. I spent an afternoon once building this from scratch for a client who wanted to model different prepayment strategies. I kept coming back to the same issue: the monthly interest calculation keeps rounding differently depending on whether you use the daily balance method or the standard monthly method. Most servicers use a daily balance method, which means a 30-year fixed at 6.5 percent doesn't actually charge exactly 6.5/12 each month. It varies slightly based on how many days are in the billing cycle. If you are doing this for a real loan comparison, account for that. If it is just a rough estimate, the monthly method is close enough and saves you a lot of setup time.
Adding Extra Principal Payments
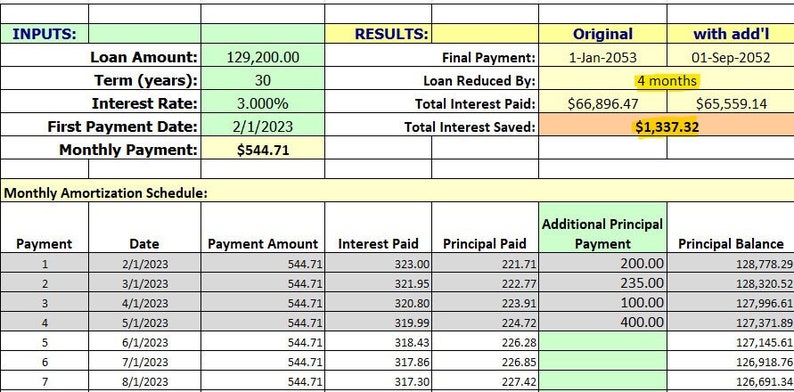
Once your base schedule is working, add columns for extra principal and the revised ending balance. When a payment includes extra principal, the next month's interest is calculated on the lower balance. The payment amount itself does not change unless you are recasting the loan, which is a separate process entirely. The extra money just eats into the principal faster. Each month after an extra payment, your interest drops a little more and your principal payoff accelerates. One thing that trips people up is the difference between making an extra payment each month versus making one large extra payment once a year. Both reduce the total interest paid, but the mechanics are different. A monthly extra payment creates a compounding effect because the balance drops every single month. A single annual extra payment has a bigger impact on the total interest saved, but the month-to-month cash flow pressure is less consistent. In practice, I have seen borrowers who commit to an extra $200 a month end up paying roughly the same total interest as someone who makes one $2,400 lump sum payment, but the monthly approach feels easier to justify budget-wise.
A Real Example
Take a $300,000 loan at 6.75 percent for 30 years. The regular monthly payment is about $1,946. Without any extra payments, you pay roughly $400,562 in total interest over the life of the loan. If you add just $100 toward principal every month, your total interest drops to about $351,000 and you pay off the loan roughly four years early. Add $500 a month and you cut about seven years off and save nearly $100,000 in interest. The numbers are straightforward. The trick is tracking them accurately across whatever irregular prepayment pattern your borrower actually follows. Here is where it gets messy. I once worked with a borrower who had a qualifying ratio issue on a refinance. Their debt-to-income ratio was too high on paper because the monthly mortgage payment included the full principal and interest with no extra principal column accounted for in the lender's underwriting software. The lender saw the higher scheduled payment and denied the application. The workaround was to provide a custom amortization schedule showing the actual reduced payment if the extra principal were treated as an escrow override or included in a modified payment structure. Some lenders will accept a manual calculation. Others will not budge. Always check with the underwriter first before you spend time building a schedule they will ignore. Another common problem is loan programs that have prepayment penalties. Not all mortgages allow you to throw extra money at the balance without a cost. Fixed-rate conforming loans generally do not, but some adjustable-rate mortgages and certain government-backed loans do carry prepayment penalty clauses, especially in the first few years. If you are building a schedule for a loan with a prepayment penalty, factor it in or the whole calculation becomes misleading. Check the note before you build the model.
Get the Full Details
Pitfalls To Watch For
Some people confuse extra principal payments with recasting. They are not the same. Recasting involves paying a large lump sum and then having the lender reamortize the loan at the same interest rate but with a lower monthly payment over the remaining term. Extra principal payments leave your monthly payment unchanged. They just shorten the loan. If a borrower thinks they are recasting when they are actually just making additional principal payments, they will be confused when their payment amount does not drop. Clarify this distinction early. It saves time later. Annuity calculations can also go wrong if your spreadsheet uses the PMT function with the wrong day-count convention. Excel's PMT function assumes a standard monthly period. If your loan has a biweekly payment structure or if the first payment is a short period, the function will drift from the actual amortization. I have seen schedules that looked correct at a glance but were off by several hundred dollars in the final years because of this. Validate your model against the lender's official amortization schedule whenever you can. If they differ by more than a dollar or two per payment, your day-count or period assumption is likely wrong.
What This Approach Does Not Do Well
Extra principal payments only help if you actually make them. A schedule that shows massive interest savings is useless if the borrower stops paying extra after three months because their emergency fund runs dry. I have seen this happen repeatedly. The math is real but the behavior is not guaranteed. Also, if the borrower has higher-interest debt elsewhere, like credit cards at 18 to 22 percent, paying extra on a mortgage at 6 percent may not be the smartest financial move. The amortization schedule will look great but the overall net worth impact could be worse. Always run a parallel calculation for competing debt before recommending extra principal prepayments. If you need a tool that handles all of this automatically, there are mortgage calculators online that support extra payments. The problem with most of them is that they ignore the daily balance method and prepayment penalties. For rough planning, they are acceptable. For actual loan comparisons or underwriting support, build your own schedule and validate it against the lender's terms. It takes longer but the result is accurate. The best approach is to build a flexible spreadsheet where you can input any prepayment pattern and see the resulting interest savings and payoff date in real time. Once the model works, you can test multiple scenarios quickly. Set up data validation so the borrower or advisor can switch between no extra payments, a fixed monthly extra amount, and irregular lump sums without breaking the formulas. It is a bit of setup work up front but it pays off the moment you need to answer a question like whether it makes sense to throw a $15,000 bonus at the loan or put it toward something else. The schedule tells you exactly what each choice costs or saves over the life of the loan.