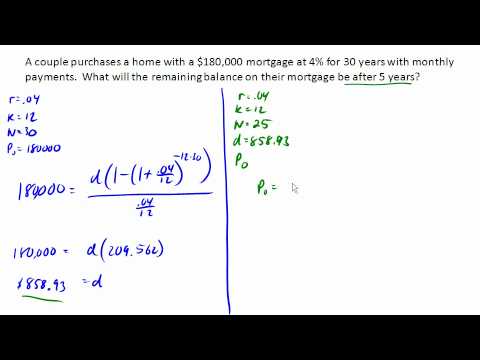Why You Actually Need This Tool
I ran into a situation a few years back where a borrower was convinced they had paid down $40,000 in principal over three years. When we pulled the actual amortization schedule, they'd only knocked off about $18,000. The rest went to interest, escrow, and a handful of fees they didn't even know existed. That kind of disconnect is pretty common, and it's exactly why a Mortgage Balance Remaining Calculator is useful instead of just guessing from your monthly statements. These tools take your original loan amount, interest rate, term length, and any extra payments you've made, then spit out what you actually owe right now. Most people assume their balance drops faster than it really does because they see a big payment number each month and assume most of it is principal. It isn't, not at first.
How to Use a Mortgage Balance Remaining Calculator
Get the four numbers your lender can give you: the original loan amount, the annual interest rate, the full loan term in months or years, and the date you closed. If you've made any extra principal payments, track those down too. A lot of people skip that last part and get results that look wrong. Plug everything into the calculator. Hit calculate. The output should show your current remaining balance, how much principal you've paid so far, how much interest you've paid, and what your new payoff date looks like if you keep making the same payment. Here is a real example from my own files. A client had a $320,000 loan at 5.75% for 30 years. She had been paying for 4 years and 2 months. The calculator showed a remaining balance of $296,180. She expected closer to $285,000. The gap came from the front-loaded interest structure of amortizing loans and one lump-sum payment she forgot to log. Once I added that $8,000 prepayment, the balance dropped to where she thought it should be. Pretty ordinary mistake.
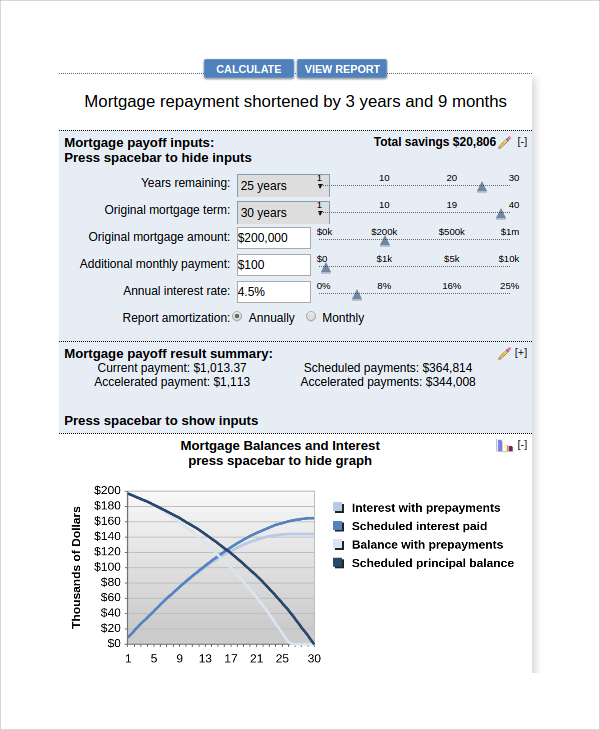
The math behind it isn't complicated. Each month, the interest charge equals your current balance multiplied by your monthly rate. The rest of your payment goes toward principal. Early in the loan, the interest portion is massive. Later, it shrinks. That is why two people with the same loan can have very different remaining balances if one made occasional extra payments and the other didn't.
Get the Full Details
What Most People Get Wrong
The biggest issue I see is people plugging in their current balance as the starting point for a new calculation instead of the original amount. That produces nonsense results because the amortization schedule already baked in all prior payments. You need the original loan details, not the balance your bank emailed you last week. If you only have the current balance and want to project forward, you can work backwards from there, but it is less accurate. Another thing: people forget about escrow. Your total monthly payment includes taxes and insurance held in escrow. Those don't reduce your loan balance at all. Some calculators let you separate principal and interest from the full payment. Use that option if you can. Otherwise you will think your balance is shrinking faster than it actually is.
When a Mortgage Balance Remaining Calculator Falls Short
These tools assume a fixed-rate loan with consistent payments. If you have an adjustable-rate mortgage, they become unreliable after your first adjustment. I had a borrower with an ARM who kept using the same calculator settings for five years. His rate had adjusted twice. The calculated balance was off by nearly $22,000 because the interest portion of each payment had changed significantly. For ARMs, you need to update the calculator every time your rate changes, or just pull an official statement from your servicer. Another limitation: most free calculators don't handle biweekly payment schedules well. If you pay every two weeks instead of monthly, your loan gets paid down faster because you make 26 half-payments a year instead of 12 full ones. That is one extra payment per year, and it can shave years off your term. A standard monthly calculator will miss that unless you manually adjust the inputs. I built a quick workaround by dividing my payment by 26 and multiplying the number of periods by 26. It took me about ten minutes to set up correctly in a spreadsheet.
Pulling This Together
If you want a straightforward way to check your remaining balance without calling your lender every week, a Mortgage Balance Remaining Calculator is a practical option. Run the numbers with your original loan details, watch out for the front-loaded interest trap, and keep track of any extra principal payments you make. The results will match your actual balance within a couple hundred dollars, which is close enough for most planning purposes. If you need exact figures for refinancing or a payoff quote, call your servicer. They can give you the precise number including any daily interest accrual, which calculators won't capture. One more thing that matters. If you plan to sell your home, the remaining balance tells you your equity position, but it doesn't account for closing costs, realtor fees, or transfer taxes. I usually remind people to subtract those from their equity estimate before making a decision. Otherwise you end up surprised when the numbers at the table don't match what you expected.