How a Mortgage Break Even Calculator Actually Works in Practice
Most people find this tool when they're trying to figure out whether buying points on a refinance is worth it or whether an old adjustable rate is eating them alive. The calculator does one job: it tells you how long you need to stay in the home before the monthly savings outweigh the upfront costs. It's not fancy. It's arithmetic. But getting the numbers right matters because one wrong input can shift your break-even from 18 months to 47, and that changes everything about whether you pull the trigger.
Mortgage Break Even Calculator Setup
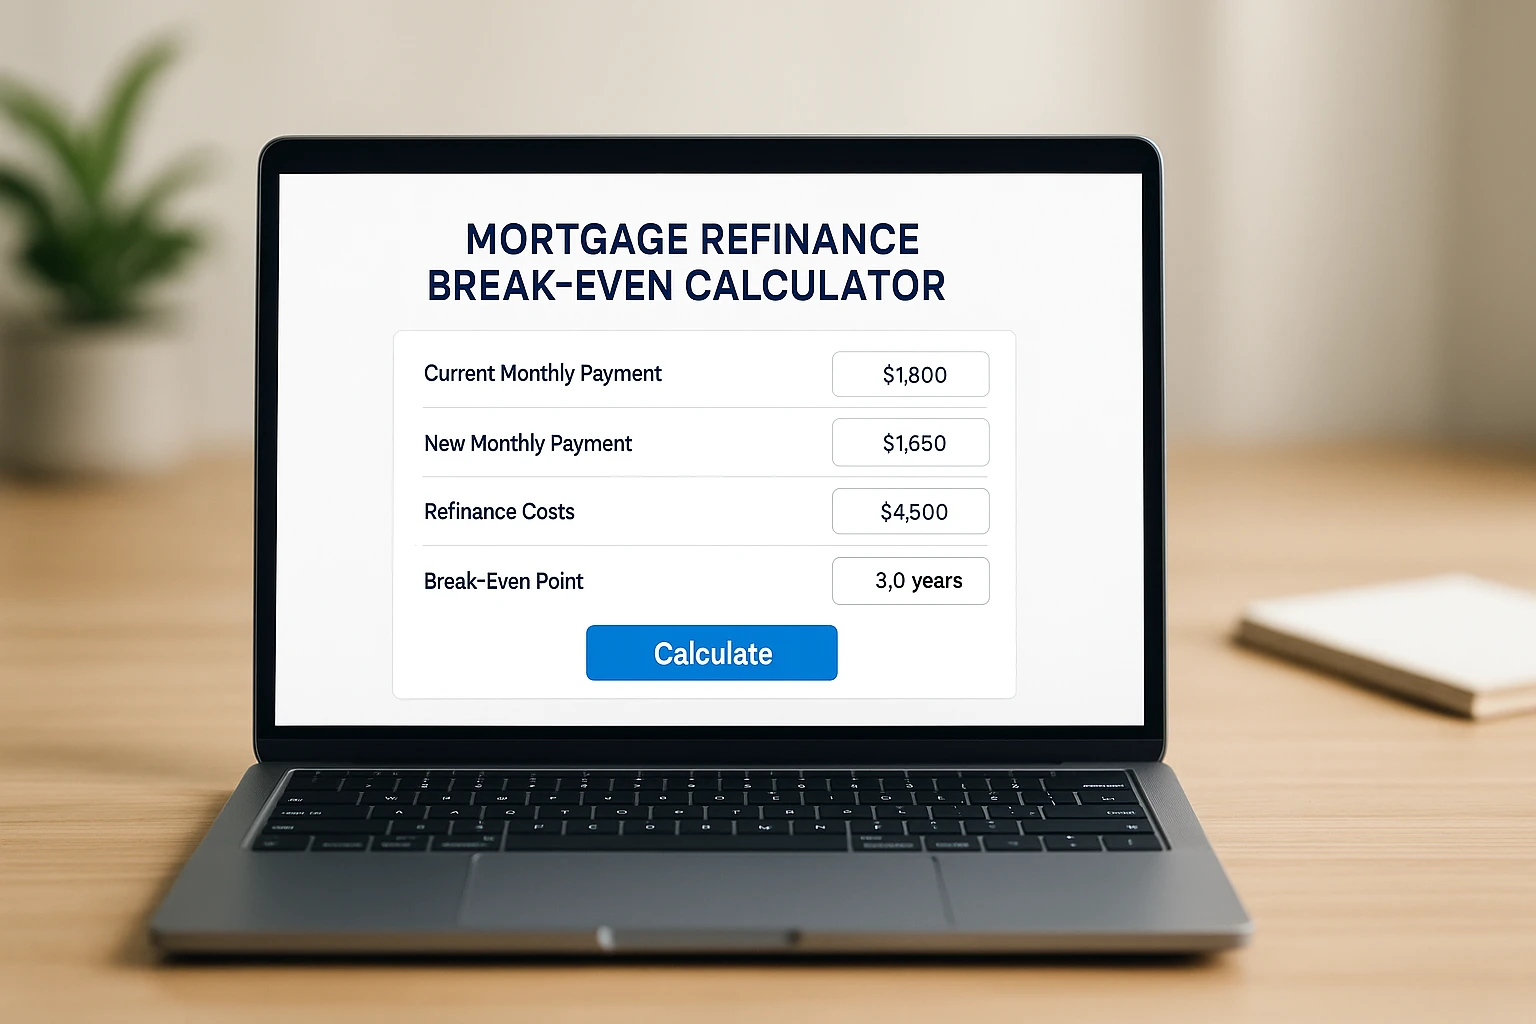
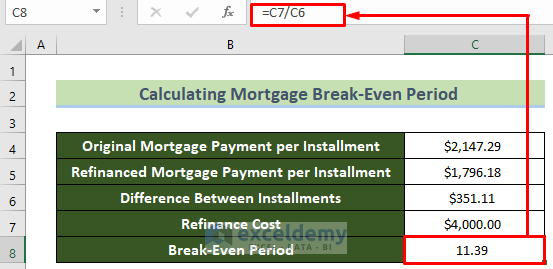
You need four inputs. Current monthly payment with your existing loan. New monthly payment after refinancing or after buying points. Total closing costs you'll pay out of pocket. And the monthly savings, which is just the difference between those two payments. Divide closing costs by the monthly savings and you get the break-even in months. That's literally it. Everything else is noise.
In practice, I've seen people skip step three or miscalculate the monthly savings because they forget to factor in escrow changes. Lenders will show you a new payment that looks almost identical to your old one and then bury the real difference somewhere in the fine print. You have to look at principal and interest specifically, not the total PITI payment, because escrow doesn't change based on your rate. It changes based on taxes and insurance. If your property taxes go up $200 a year, that shows up in the payment but it has nothing to do with your refinancing decision.
Here's where I ran into the edge case that still bugs me. A client of mine was refinancing from a 6.5 percent ARM to a fixed rate and the calculator showed a break-even of 14 months. Looked good. I dug into the amortization schedule the broker provided and noticed the new loan had an upfront mortgage insurance premium rolled into the closing costs but the lender wasn't listing it separately. It was sitting inside the "origination charges" line item. Once I pulled that out and added it back to the true cost, the break-even shifted to 31 months. The calculator hadn't been wrong. The input data had been wrong. This happens more often than you'd think because loan estimates group a lot of line items together and the real breakdown doesn't arrive until closing disclosure, which comes five days before you sign.
A lot of people using this calculator also miss the compounding effect of staying beyond the break-even point. Say your break-even is 24 months and you planned to move in 30. That extra six months of savings isn't just six months of savings, it's also the opportunity cost of the money you tied up in closing costs. If you'd kept that $6,000 in a high-yield account at 4.5 percent, you'd have roughly $180 in interest by month 30. Small, but the bigger issue is that most homeowners don't actually know how long they'll stay. The calculator gives you a number, but it doesn't answer the harder question, which is whether your life circumstances are likely to change in the next three to five years.
Another thing nobody explains well about the tool is how prepayment penalties affect the math. If your current loan has a yield maintenance clause or a hard prepayment penalty, that cost belongs in the denominator of your calculation. I've seen people calculate a break-even of 11 months and then discover they'd need to pay a $4,200 penalty to exit the loan, which pushes the break-even past the point where moving or selling becomes feasible. Add it in or it's not a useful calculation.
The calculator also breaks down if your new loan has a balloon payment or is structured as an interest-only period. The monthly savings will look massive in years one through three, which makes the break-even date look incredibly attractive, but once the payment resets or comes due, the whole premise falls apart. You need to calculate a secondary break-even for the post-reset scenario if that's what you're dealing with. I stopped recommending the simple version of this tool to anyone with an interest-only or negative amortization loan years ago. It misleads people who haven't read the contract terms carefully.
One more realistic limitation. The calculator assumes your saved money goes into something, even if it's just sitting in a checking account. If you're the type to spend the extra cash flow rather than save or invest it, the break-even is purely theoretical. The math is correct, but the personal outcome isn't guaranteed. This isn't a criticism of the tool, it's a criticism of how people use it as a substitute for having a financial plan. The tool tells you when you've recouped your costs. It doesn't tell you what to do with the money after that point.
If you're going to use this yourself, get the full closing disclosure before you plug in the numbers. Use the actual figures, not the loan estimate, because the estimate can be off by several thousand dollars depending on your lender and market conditions. The closer your input data is to reality, the more useful the output is. And don't treat the break-even month as a deadline. It's an information point. Whether you refinance depends on your actual plans, your risk tolerance, and whether you have other opportunities for that capital that would outperform your rate drop.
Gallery Mortgage Break Even Calculator
Mortgage Points Break-Even Calculator Excel at Olivia Brewster blog
Mortgage Refinance Break-Even Calculator - Freelandt Caldwell Reilly, LLP
Refinance Break-Even Calculator Template - Free Mortgage Calculator ...
Mortgage Break-Even Analysis in Excel (with Easy Steps)
When to Refinance Mortgage: Calculate Break-Even & Save [2025]