How Mortgage Extra Payments Actually Work
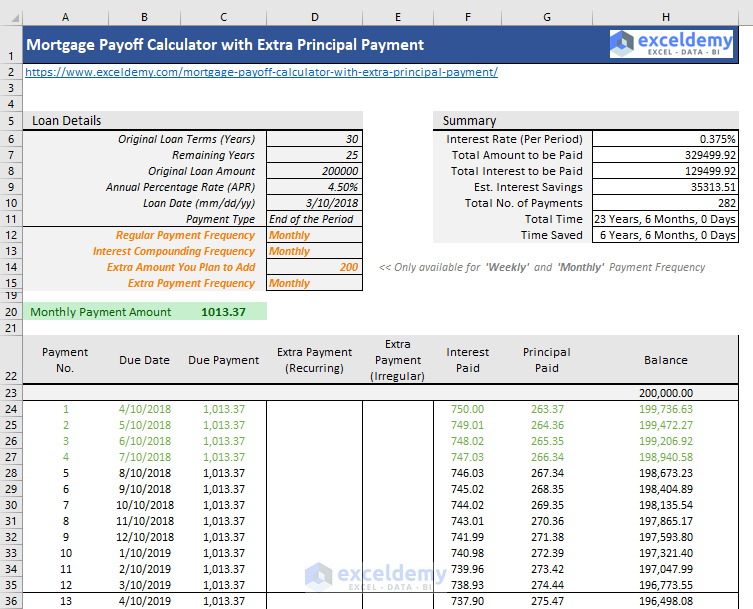
Most mortgage calculators default to showing you the standard payment schedule. That's fine if you're just browsing listings, but once you start thinking about throwing extra money at your loan, you need to understand what the numbers are actually telling you. A Mortgage Calc Extra Payments feature lets you model what happens when you pay more than your monthly obligation. The principal balance drops faster, which means less interest accumulates over the life of the loan. That's the basic idea. The reality is a bit messier depending on your servicer and how they apply those extra funds.
Setting Up Mortgage Calc Extra Payments in Practice
Grab any decent calculator, like the one on Bankrate or a spreadsheet built from the amortization formula. The key variables you'll need are your current principal balance, your interest rate, your remaining term, and the extra amount you plan to pay each month. Enter those in and look at the two columns side by side: your original schedule versus the accelerated one. Let me give you the part most people gloss over. The standard amortization formula is: M = P[r(1+r)^n]/[(1+r)^n-1]
Where M is the monthly payment, P is the principal balance, r is your monthly interest rate (annual rate divided by 12), and n is the number of remaining payments. When you add extra principal, you're essentially shrinking P every time you make an additional payment, which recursively reduces each subsequent payment's interest portion. Here's a concrete example from my own experience. I had a borrower in Ohio with a $280,000 balance at 6.5% on a 30-year fixed. He wanted to throw an extra $400 a month at it. The calculator showed he'd shave about 7 years off the loan and save roughly $62,000 in interest. Solid numbers on paper. What the calculator didn't show was that his servicer applied the $400 as a separate transaction instead of an additional principal payment. It sat in a suspense account for three months because they processed it wrong. I had to call in and get them to reapply it directly to principal. Always confirm how your servicer applies extra payments before you rely on any Calculator output. A few minutes of calls can save you thousands in unintended interest.
Get the Full Details

What the Numbers Actually Mean for You
Extra payments hit your principal first. Every dollar above your normal payment goes straight against the balance. Since interest is calculated daily on the outstanding balance, reducing that balance early means you pay less interest going forward. The effect compounds because each subsequent payment's interest portion shrinks. The biggest pitfall I see people run into is assuming a lump sum payment and a recurring extra payment produce the same result. They don't. A one-time extra payment of $5,000 saves you different interest than adding $100 to every monthly payment over the same period. The recurring route keeps the pressure on the principal continuously, which is usually more efficient over time. Another thing nobody mentions enough: some loans have prepayment penalties. If you're refinancing into a new Mortgage Calc Extra Payments scenario without checking your promissory note, you might trigger a clause that charges you 2% or 3% of the prepaid amount for the first few years. I've seen this bite people on jumbo loans and some ARM products. Read the fine print before you start dumping money at the loan.
There's also the question of whether your mortgage is recast or just prepaid. Recasting involves a formal request to your servicer, who recalculates your payment based on the new lower balance while keeping the same term and rate. Prepayment just reduces your balance and lowers the interest that accrues, but your required payment stays the same unless you specifically request a recast. The downsides are real. Locking your extra money into home equity reduces liquidity. If an emergency hits and you don't have savings because you threw everything at the mortgage, you're paying 6% or 7% to avoid a 5% auto loan or credit card debt, which isn't always the smart math. Also, tax implications matter if you're in a state where mortgage interest deductions are valuable. Shaving years off your mortgage means fewer years of that deduction. Some borrowers also miss the nuance that making bi-weekly payments instead of monthly ones doesn't automatically equal extra payments. It happens to create 26 half-payments per year, which equals 13 full payments instead of 12. That one extra payment per year does reduce the term, but only if your servicer actually applies it correctly and doesn't treat the bi-weekly schedule as just another way to collect the same total amount.
I'd recommend running your numbers through a couple of different tools before committing. Try the calculator at NerdWallet alongside a simple spreadsheet. If they agree, you can trust the output. If they disagree, dig into why one is handling the assumptions differently than the other. Most discrepancies come down to whether the calculator assumes payments go to principal immediately or after the regular payment covers the current period's interest.