Understanding the 5-Year Balloon Mortgage Calculator
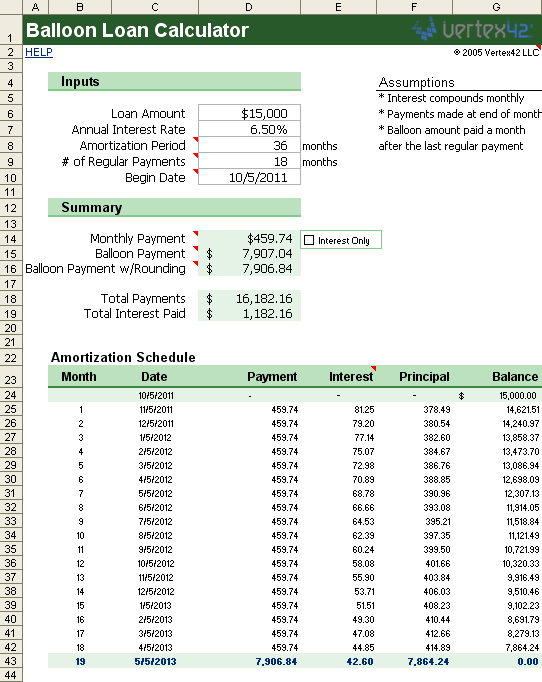
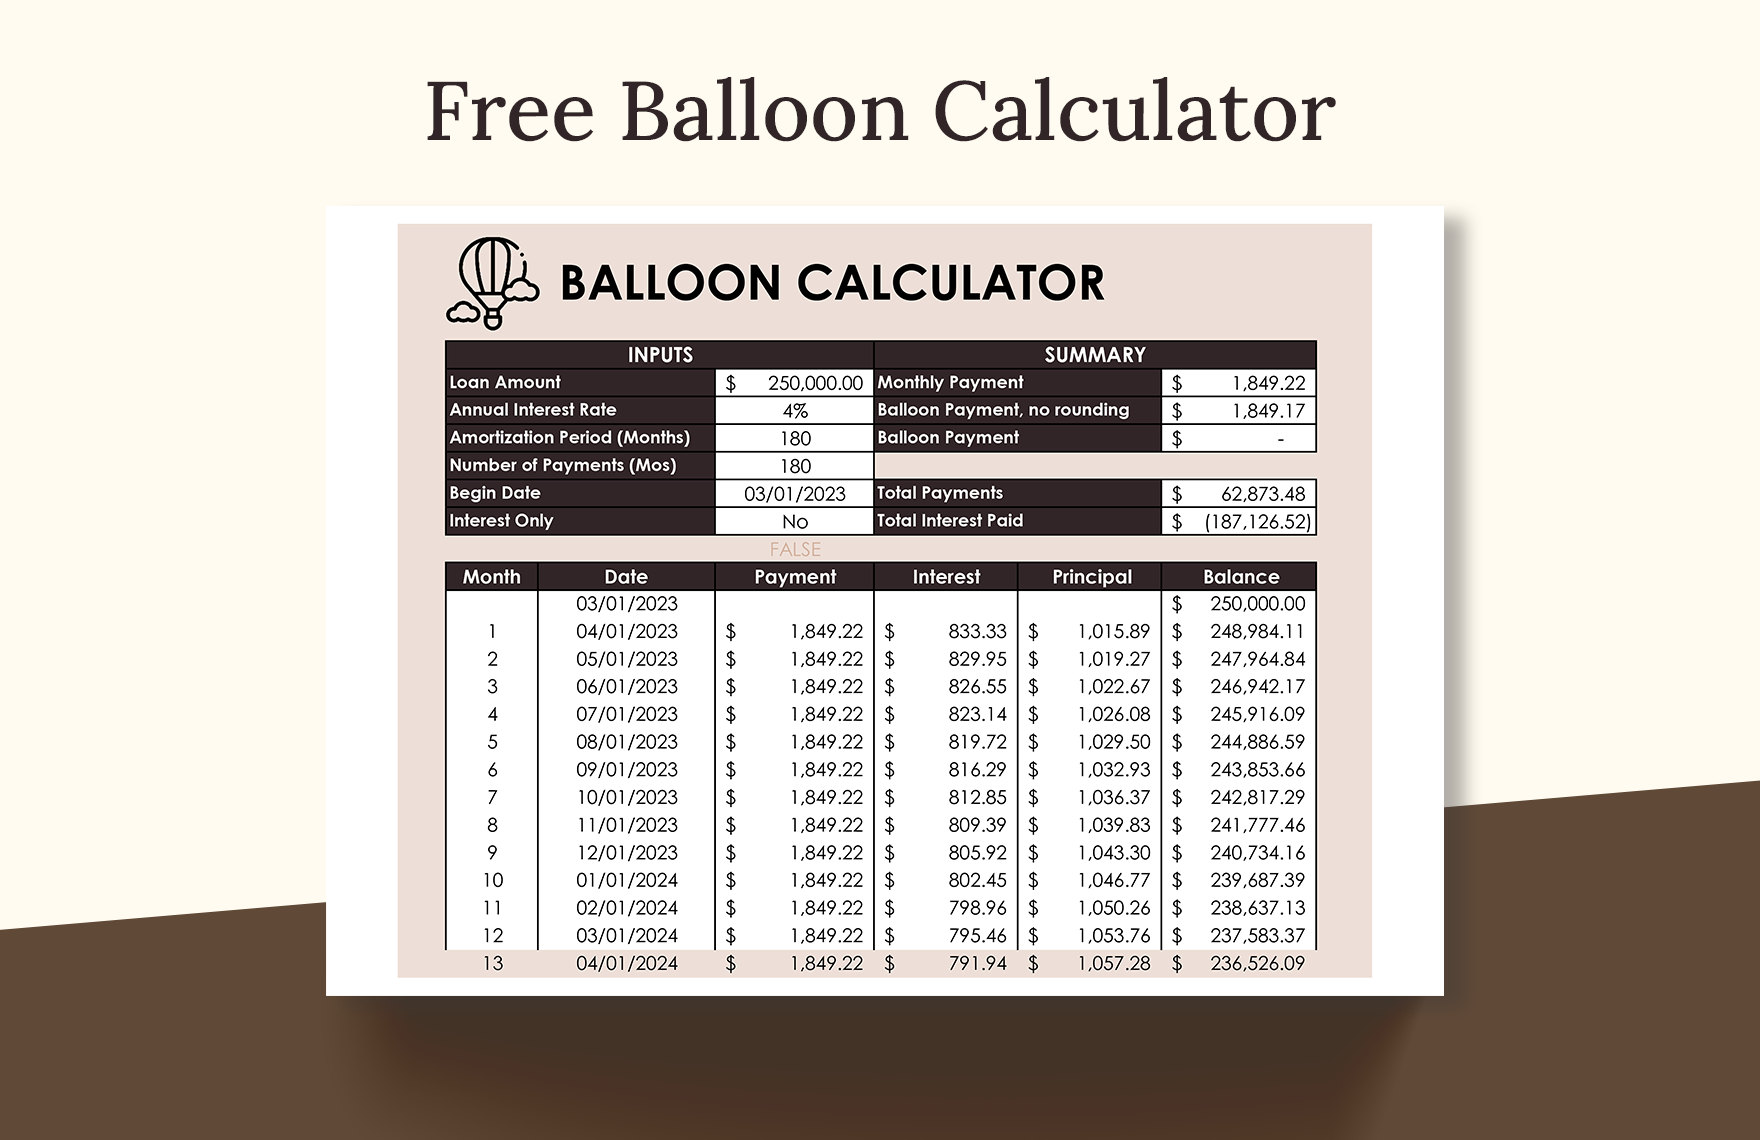
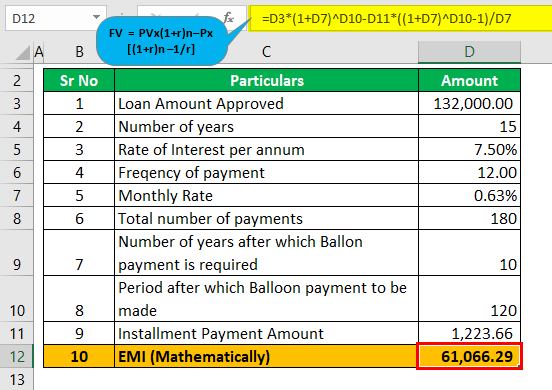
Most people look at a balloon mortgage and assume it is just a regular loan with a weird name. It is not. A 5-year balloon works as a significantly longer amortization schedule, usually 20 or 30 years, but the entire remaining balance comes due after exactly 5 years. The monthly payment is calculated based on those 20 or 30 years, which makes the payment look deceptively small. Then at year 5, you owe every dollar that was never paid down.I spent years working with commercial and residential investors who kept running into the same problem: they would calculate their monthly payment correctly but then completely forget to factor in the lump sum that was coming due. The calculator gives you the payment, sure, but it does not automatically warn you about the balloon. You have to build that awareness into your own process. I usually tell people to skip the generic online calculators and use something like Excel with the PMT function for the monthly payment and the FV function for the remaining balance. The FV function takes the rate per period, the number of periods paid, the payment amount, and zero future value, and spits out exactly what is still owed at the balloon date. It took me about ten minutes to build my own spreadsheet after I realized I was relying on three different web tools that all gave slightly different answers. That inconsistency mattered when someone had to refinance or sell on tight margins. One edge case I ran into repeatedly involved properties with points or closing costs rolled into the loan amount. A lot of people forget to include those in the principal when they run the calculator. I had a borrower who put 3 percent in points on a $400,000 loan and calculated everything based on $400,000. The actual financed amount was $412,000. The monthly payment looked fine at first glance, but the balloon balance at year 5 was about $8,000 higher than he expected, which turned a comfortable refinance into a situation where he had to pull cash from a retirement account to cover the gap. I now always add a field for financed costs before running any balloon calculation.
Why This Tool Exists and Who Actually Uses It
Balloon mortgages are not really for primary residences anymore. They show up mostly in investment properties, construction loans, and situations where the borrower expects to sell or refinance within a few years. The appeal is the lower monthly payment during those five years, which improves cash flow while you are renovating or stabilizing occupancy. The tradeoff is the enormous risk at the end if your exit strategy fails.A 5-year balloon on a $350,000 loan at 6.5 percent amortized over 30 years produces a monthly payment of roughly $2,210. The total amount paid over 60 months is $132,600. But the remaining balance at the balloon date is about $326,000. You have only reduced the principal by roughly $24,000 in five years, which is less than 7 percent of the loan. Most people do not realize that until they are staring at the balloon payment and the refinancing market has tightened. The deeper problem is that balloon mortgages often come with prepayment penalties or lock-in clauses that make refinancing expensive right when you need to refinance most. I have seen lenders charge 2 percent of the outstanding balance as a yield maintenance fee or a defeasance cost. On a $326,000 balance, that is $6,520 just to exit the loan early. A Mortgage Calculator 5 Year Balloon tool will not show you any of those fees because they are negotiation-level items that vary by lender and state. You have to look at the promissory note and the deed of trust to find them.
Common Mistakes That Destroy the Math
The biggest error I see is confusing the balloon term with the amortization term. People enter 5 years into the amortization field instead of the balloon term field, which gives them a wildly incorrect payment. Some calculators label these fields poorly, and the distinction is not always obvious. Always double-check what the input fields actually represent before you click calculate.Another mistake is ignoring the difference between simple interest and compound interest structures. Most consumer mortgages are simple interest, meaning your daily interest accrues based on the remaining principal. If you make a payment 5 days late, you pay extra interest compared to an on-time payment. Over 60 months, that can add hundreds of dollars to the final balance. Commercial balloon loans sometimes use 360-day year calculations or even interest reserves that distort the payment further. I once worked with a borrower whose balloon payment was 4 percent higher than my spreadsheet predicted because the lender was using a 360-day basis and I was using 365. The calculator he found online also assumed 365, so he had no idea where the discrepancy came from until the closing documents arrived. You also need to think about what happens after year 5 in your planning, not just the calculation itself. If you are counting on refinancing, check current rate trends and your projected credit profile at that future date. A 5-year balloon assumes you can refinance at acceptable terms, and that assumption can break if rates spike or if the property underperforms during the ramp-up period. The calculator gives you a snapshot, not a guarantee.
Get the Full Details
When a Balloon Mortgage Makes Sense and When It Does Not
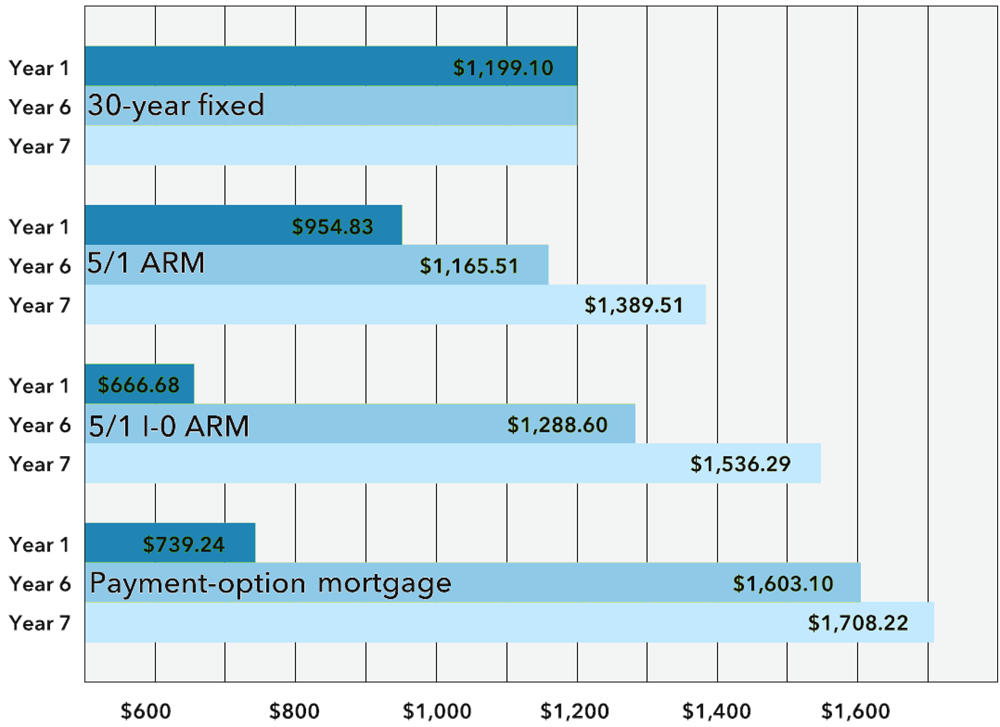
A balloon mortgage is reasonable when you have a clear exit strategy, solid equity in the property, and a realistic timeline for either selling or refinancing. Fix-and-flip investors sometimes use short-term balloon structures to keep payments low during renovation. Landlords buying value-add properties use them to improve debt service coverage ratios before refinancing into a conventional loan. The common thread is that the borrower has control over the timeline.It is a bad fit when your income is unstable, when the property market in your area is stagnant, or when you cannot qualify for a traditional mortgage for any reason. The risk is not hypothetical. I had a client who took a 5-year balloon on a rental property in 2021 when rates were near 3 percent. By 2024, rates had climbed past 7 percent, and refinancing the $326,000 balloon payment would have increased his monthly obligation by nearly $900. He ended up selling the property at a loss because he could not carry the new payment. The calculator he used in 2021 had shown a comfortable payment, but it could not predict interest rate movement five years out. For most borrowers, a standard 30-year fixed mortgage or a 15-year fixed is the safer choice, even if the monthly payment is higher. The balloon structure trades payment relief for tail risk, and that risk is real. If you are set on a 5-year balloon, treat the balloon payment as a deadline, not a maybe. Build the payoff into your budget now, and run sensitivity scenarios at different interest rate environments so you know what refinancing will actually cost when the time comes.