What an ARM Mortgage Calculator Actually Does
A Mortgage Calculator Arm takes your loan amount, interest rate, term length, and adjustment schedule and projects what your monthly payment will look like over the life of the loan. The tricky part is that ARM stands for Adjustable Rate Mortgage, and those payments don't stay flat. They shift at set intervals based on a benchmark index plus a margin. The calculator's job is to show you each potential shift before you commit to the note. I built and maintained a spreadsheet-based ARM calculator for a small community bank back in 2014 through 2018. We processed roughly sixty to eighty ARMs per year, mostly 5/1 and 7/1 hybrids. Most people assumed the calculator just compounded a single rate forward. It doesn't. The actual math involves compounding adjustments, payment recalculation at each reset, and caps that limit how much the rate or payment can move in a given period. Skip any of those pieces and your projection is wrong, sometimes by thousands over the loan life.
Using a Mortgage Calculator Arm Step by Step
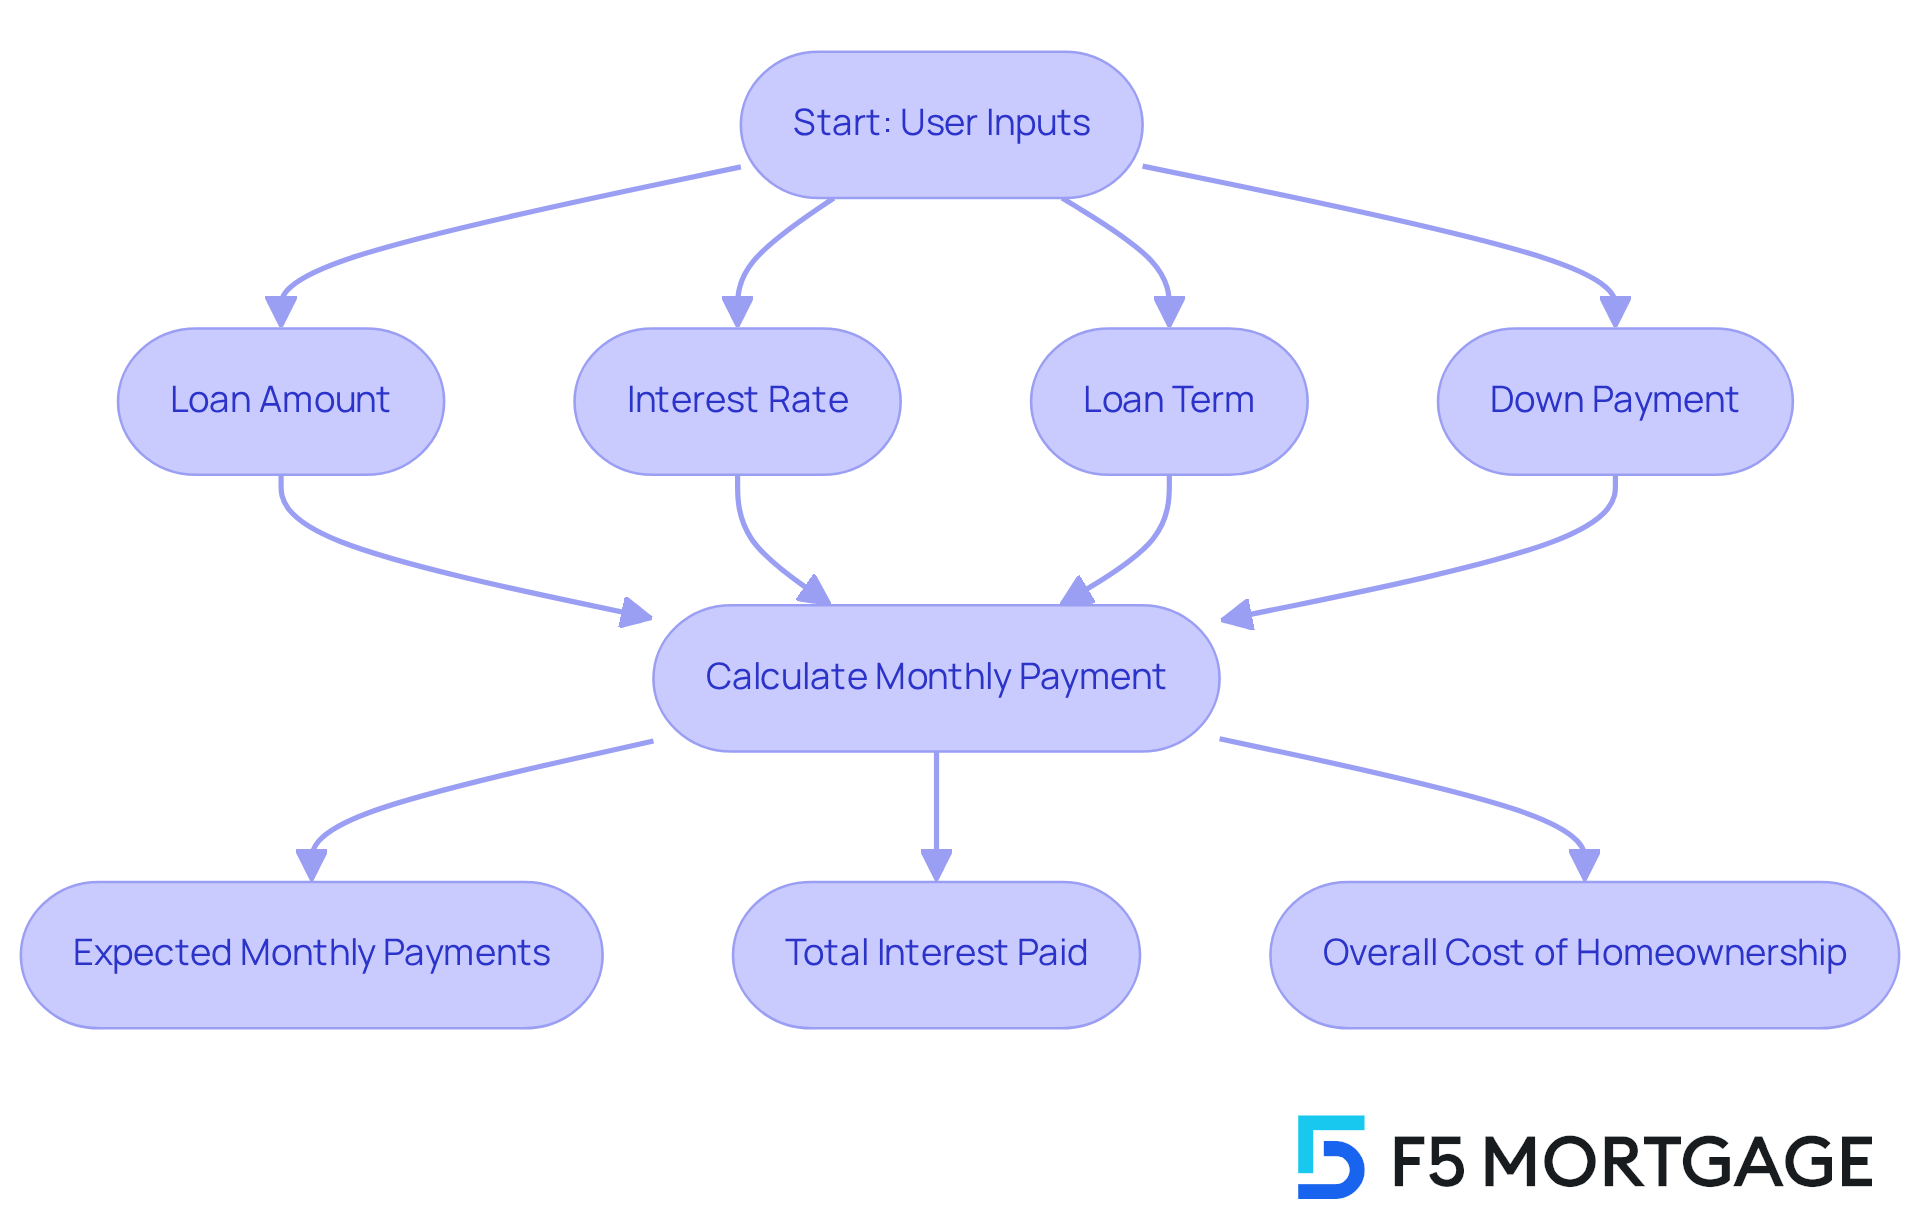
Here is how I would walk through a real calculation without any fluff. You need five inputs, minimum. The loan amount. The initial fixed period rate. The index and margin that drive future adjustments. The adjustment frequency, meaning how often the rate changes after the initial period ends. And the caps, both periodic and lifetime. Start with the amortization schedule for the initial period. Calculate the monthly payment using the standard formula: M equals P times r times (1 plus r) to the n, divided by (1 plus r) to the n minus one. P is the principal. r is your monthly interest rate. n is total number of payments during that fixed phase. Run that out to the last payment of the initial period, then roll the remaining balance into the next phase. At the first adjustment date, look up the current index value, add the margin, and you get the new fully indexed rate. Apply the periodic cap to determine how much the rate can actually move. That new rate replaces the old one. Recalculate the payment using the remaining balance and the remaining number of payments. Repeat for each adjustment period until the loan matures or converts to a fixed rate if the product allows it.
The output should be a month-by-month table showing the rate, payment, principal portion, interest portion, and remaining balance for every phase. Any calculator that gives you a single average payment number is lying to you by omission.
Get the Full Details
Where Most Calculators Get It Wrong
I have seen dozens of free online ARM calculators online and most of them make the same errors. They assume the rate resets to the fully indexed rate immediately at the first adjustment, ignoring the periodic cap. They do not re-amortize the remaining balance correctly, which throws off every payment after the first reset. Some of them treat the margin as a one-time addition rather than a permanent component of the rate. A few even calculate caps on the payment instead of on the rate, which produces wildly different numbers. Here is a concrete example from my own work. A borrower came in with a 5/1 ARM at 3.125 percent initial rate, 2.25 percent margin, indexed to the One-Year Constant Maturity Treasury. The loan was three hundred eighty-five thousand dollars, thirty-year term. The periodic cap was two percent and the lifetime cap was five percent above the initial rate. The CMT had been climbing steadily for about eighteen months. My calculator showed the first adjustment would be capped at five and one-eighths percent, not the fully indexed six point something. That changed the payment by roughly forty-two dollars compared to what a naive calculator would show. Over the remaining twenty-five years, that difference compounded into nearly four thousand dollars in total interest paid during the early years alone.
The Counter-Intuitive Part Nobody Talks About
The biggest misunderstanding I see is around the relationship between the index and your actual payment. People think the payment is locked in once they close. It is not. But here is the part most calculators and loan officers gloss over: your payment at reset depends on the index level at reset AND the remaining amortization schedule at that exact moment. If rates jump but you are early in the loan, the payment shock is smaller than it would be later because you have more principal to amortize over more remaining periods. Conversely, if you refinance into an ARM with only five years of payments left, a modest rate increase can still create a large payment bump because there is very little amortization tail to absorb it. Another thing people miss is that negative amortization is technically possible with certain ARM structures, though it is rare in conforming loans. If the periodic payment cap is lower than the interest due, the shortfall gets added to the principal. A good calculator flags this explicitly. A bad one silently includes it and reports a payment that cannot possibly cover the accrued interest.
Practical Limitations of These Calculators
ARM calculators cannot predict the index. No software can. They can only model scenarios based on your assumptions about future index levels. If you plug in a static rate and call it a projection, you are not doing a calculation, you are doing wishful thinking. The only reliable approach is to run multiple scenarios: current index, historical highs, historical lows, and a moderate upward path. Compare the worst-case payment against your actual budget ceiling, not your current comfortable number. There is also the issue of borrower-specific factors that no public calculator handles. Your loan could have an introductory buydown that expires mid-period. It might have a conversion option that changes the entire structure. Government loans like FHA ARM products have their own cap rules that differ from conventional ARMs. Commercial ARMs follow completely different adjustment mechanics. A generic calculator will not account for any of this without manual overrides, and those overrides are where most people make mistakes.

What I Use Instead of Generic Online Tools
For actual lending decisions, I do not rely on free web calculators. I use a custom Excel model with separate worksheets for each adjustment period, hard-coded cap logic, and scenario analysis built in. The model takes about twenty minutes to set up for a new loan product once you have the template. After that, each new calculation takes roughly five minutes. The output includes a summary dashboard showing maximum possible payment at each adjustment date, total interest across all scenarios, and a breakeven comparison against a fixed-rate alternative. If you want something simpler but still accurate enough for personal planning, a well-built Google Sheets template with explicit periodic and lifetime cap formulas will get you ninety percent of the way there. The key is verifying that the payment recalculation at each reset uses the remaining balance and remaining term, not the original loan amount and original term. That single error appears in far too many free tools and it makes the entire projection meaningless after the first adjustment. The bottom line is that an ARM calculator is only as useful as its assumptions and its treatment of caps. Run the scenarios. Check the math at each reset point. And do not let a single-number payment projection convince you that the rate will stay predictable. It will not.