How Chicago's mortgage math breaks the standard calculator
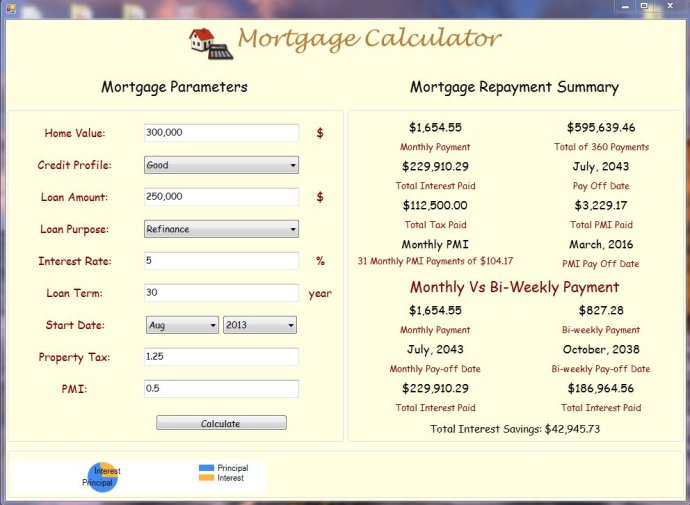
Most online mortgage calculators will give you a number that's $200 to $600 per month below what you'll actually pay. They treat property tax as a uniform percentage, assume insurance is the same everywhere, and completely ignore the extra fees Chicago adds to the stack. I built a workaround because clients kept showing up at closings confused about their escrow shortfall. The real tool you need isn't a single website. It's a spreadsheet or a calculator where you can manually enter the three variables that Chicago inflates above the national average: property tax rate, homeowners insurance, and association fees. The national median property tax rate sits around 1.07 percent. Cook County averages closer to 2.1 to 2.3 percent depending on your assessment ratio. That alone doubles the tax component of your payment compared to what a generic calculator shows. I keep a simple Google Sheet open alongside any standard calculator. Here's what I put into it. Purchase price, down payment, interest rate, loan term. Then I add separate rows for annual property tax, annual insurance, PMI if the down payment is under 20 percent, and HOA or condo fees if applicable. I divide each annual figure by 12 to get the monthly amount and add it to the principal and interest payment. The result matches what the lender's Closing Disclosure will actually show.
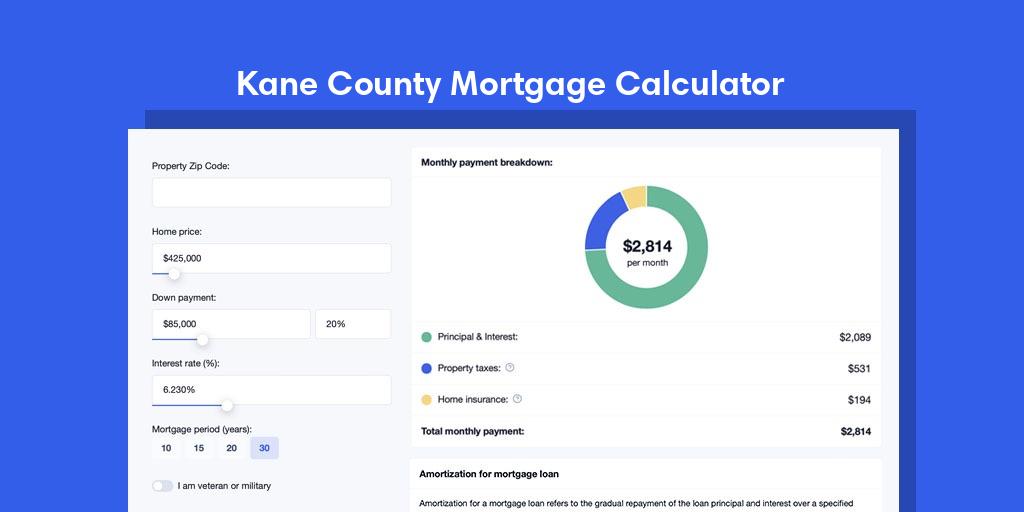
One client tried using a free online calculator for a $425,000 condo in Lincoln Park. The tool quoted a monthly payment of roughly $2,680. When I ran the numbers with the actual county tax rate for that zip code, current insurance premiums in Cook County, and a $340 monthly HOA fee, the real payment came out to $3,190. A five hundred dollar gap. That client nearly walked away from a good deal because the first number looked affordable and the second didn't. The calculator didn't lie, but it was incomplete for Chicago.
What most people miss about Chicago-specific costs
The biggest blind spot is the assessment ratio. Cook County doesn't assess property at full market value. Residential properties are assessed at roughly 10 percent of fair market value, and the tax rate is applied to that assessed value. So when you see a listing price, you can't just slap a flat tax percentage on it. You have to work backward through the assessment. A $500,000 home might have an assessed value closer to $50,000, and the effective tax bill ends up being somewhere in the $8,000 to $10,000 range depending on the district and any exemptions. Homestead exemptions matter a lot here. The standard $10,000 Homestead Exemption reduces the taxable assessed value. Some school districts and municipalities offer additional exemptions that stack. If you're a first-time buyer, a senior, or disabled, there may be freeze programs that cap the assessed increase. A calculator that doesn't factor in which exemptions you qualify for will overstate your taxes, sometimes by $400 to $800 a month. Insurance is another layer that varies wildly by neighborhood and building type. A fourth-floor walk-up in Avondale costs significantly less to insure than a ground-floor unit in a older brick building near the floodplain. Several Chicago neighborhoods fall partially or fully within FEMA flood zones, and flood insurance is a separate mandatory expense that no standard mortgage calculator includes. I've seen buyers discover a $1,200 annual flood insurance premium at closing and have it reclassified their budget entirely.
Get the Full Details
Where the approach falls apart
This manual method requires accurate data. If you don't know the exact assessed value, the current tax rate for your specific parcel, and your insurance quotes before you run the numbers, the output is just a guess with more steps. Chicago property tax bills also come with payment options. You can pay semi-annually or quarterly, and late payments carry penalties. A monthly calculator won't show you the discount for paying early or the penalty for missing the November due date. Another limitation: these calculators don't account for special assessments. If your street gets repaved or your building's heating system is replaced, the municipality or co-op board can levy a special charge that gets added to your tax bill. This happens more often in Chicago than people expect, and it can add hundreds to your annual payment with no warning. No standard calculator or spreadsheet predicts this. If you want something closer to a turnkey solution, the Cook County Assessor's website has a property search tool where you can pull the exact assessed value and tax amount for any parcel. Cross-reference that with your lender's rate quote and an insurance estimate from a local agent, and you'll get a number that's within fifty dollars of your actual payment. Anything less and you're working with an estimate dressed up as a fact.