The Math Behind Monthly Payments
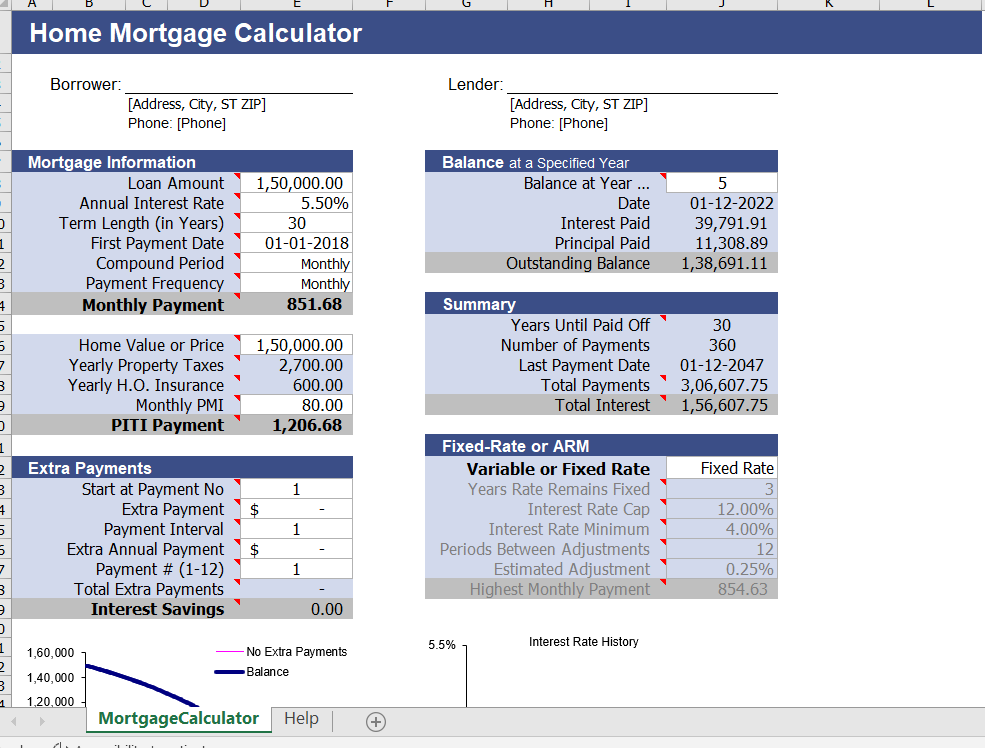
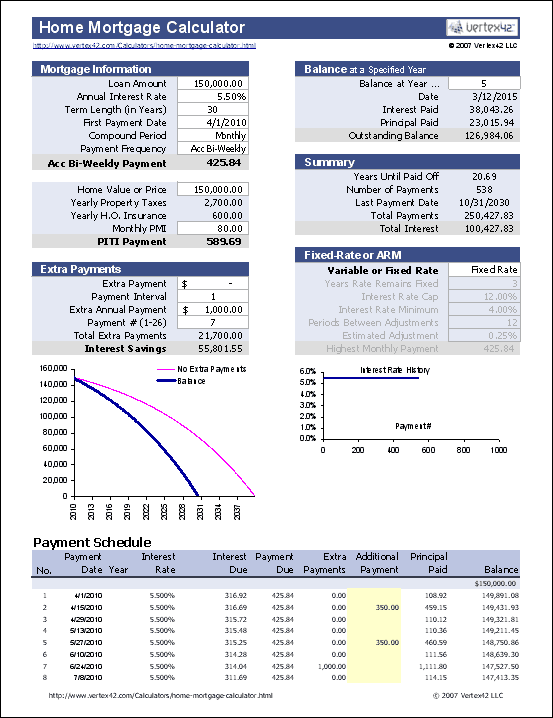
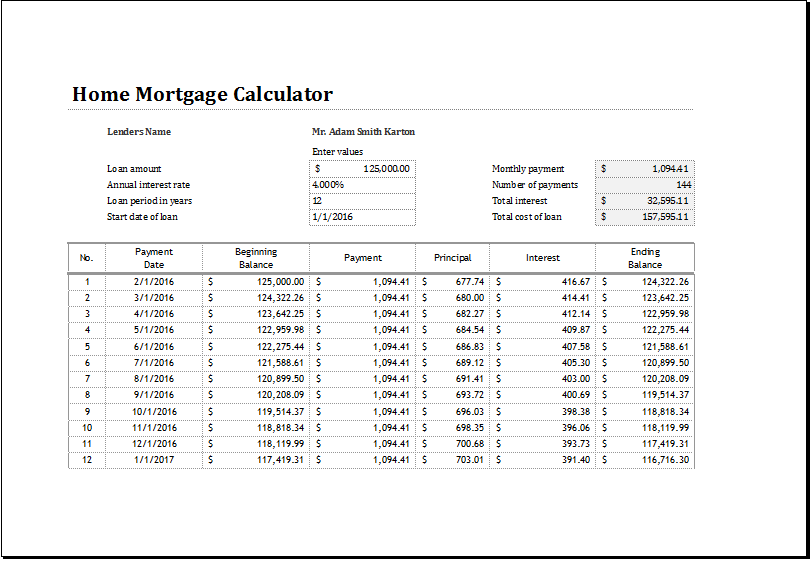
A mortgage payment isn't just interest divided by twelve. It uses an amortization formula that most people gloss over until they see the actual spreadsheet. The core calculation is M = P × [r(1+r)^n] / [(1+r)^n - 1], where P is the principal loan amount, r is your monthly interest rate (annual rate divided by 12), and n is the total number of payments over the loan term. That means a $300,000 loan at 6.5% annual rate over 30 years gives you a monthly rate of 0.005417 and 360 total payments. Running those numbers produces a principal and interest payment of roughly $1,896 per month. This is the number everyone focuses on, but it's only one piece of the total housing cost. The reason this formula matters is that it reveals something most first-time buyers miss: in the early years of a mortgage, the vast majority of your payment goes toward interest, not principal. On that same $300,000 loan at 6.5%, your first monthly payment of $1,896 contains about $1,625 in interest and only $271 in principal reduction. After five years, you'll have paid roughly $113,000 in total but only reduced the balance by about $30,000. This front-loading of interest is exactly why refinancing or making extra payments early on has such a dramatic impact on your total cost of borrowing.
Using a Mortgage Calculator For Home Realistically
When I built my own mortgage calculator tool, I learned pretty quickly that the standard input fields — loan amount, interest rate, term length — only get you so far. The real world introduces complications that most generic calculators ignore completely. Property taxes vary by county and reassess periodically. Homeowners insurance premiums depend on your location, construction type, and claims history. Private mortgage insurance kicks in when your down payment is below 20%, and it typically costs between 0.5% and 1% of the loan amount annually until you reach that 20% equity threshold. Here's the specific edge case that trips up virtually everyone: rate locks and loan origination fees. When you're shopping for a mortgage, the quoted interest rate is usually only valid for 30 to 60 days. During that window, points — prepaid interest paid upfront to buy down your rate — can materially change your effective cost. One point equals 1% of the loan amount and typically drops your rate by about 0.25%. I once had a client who ran her numbers through an online calculator that didn't factor in two discount points she'd agreed to pay. The difference between the quoted payment and her actual payment was $47 per month, which sounds small until you multiply it across 360 payments. That's a $16,920 discrepancy that a proper Mortgage Calculator For Home should surface before you sign anything. Another counter-intuitive detail most people overlook involves how your escrow account gets calculated. Lenders typically require you to pay 1/12th of your annual property tax bill and 1/12th of your annual insurance premium each month, bundled into your total payment. But these amounts aren't static. Property taxes in my county reassess every three years, and the escrow shortfall analysis that follows can increase your monthly payment by $100 or more with little warning. A well-designed calculator lets you model these adjustments by building in a percentage escalation assumption, usually 2% to 4% annually for taxes and 3% to 6% for insurance.
The biggest limitation any mortgage calculator shares is that it can't account for your specific lender's overlay requirements or program nuances. Some loans include lender credits that offset closing costs but carry a slightly higher rate. Adjustable-rate mortgages have complex adjustment caps, periodic floors, and lifetime caps that no simple calculator captures accurately. FHA loans carry an upfront mortgage insurance premium of 1.75% of the base loan amount plus monthly MIP that lasts the life of the loan if you put less than 10% down. VA loans have a funding fee ranging from 1.4% to 3.6% depending on your service status and down payment size. Each of these programs distorts the clean mathematical model that a standard calculator produces. If you're working with a mortgage amount over $766,550 in 2024, you're dealing with a conforming loan limit that varies by county, and jumbo loan programs apply entirely different pricing structures. These loans don't conform to Fannie Mae or Freddie Mac guidelines, and the interest rates are typically 0.25% to 0.75% higher than conforming products. A Mortgage Calculator For Home will still produce a payment figure for jumbo loans, but it won't reflect the actual rate your lender will quote you because jumbo pricing is negotiated on a case-by-case basis. The most practical approach I've found is to use a calculator as a first-order estimation tool, then validate every number against your actual Loan Estimate document from your lender. The three-day waiting period between receiving your Loan Estimate and closing is specifically designed to give you time to compare the disclosed terms against your calculations. If your calculator shows $1,896 and your Loan Estimate shows $2,047, that $151 gap deserves an explanation before you proceed. Common culprits include lender fees, third-party settlement charges, prepaid items like property taxes and insurance that the calculator didn't include, andHOA dues if the property has a homeowners association.
Get the Full Details
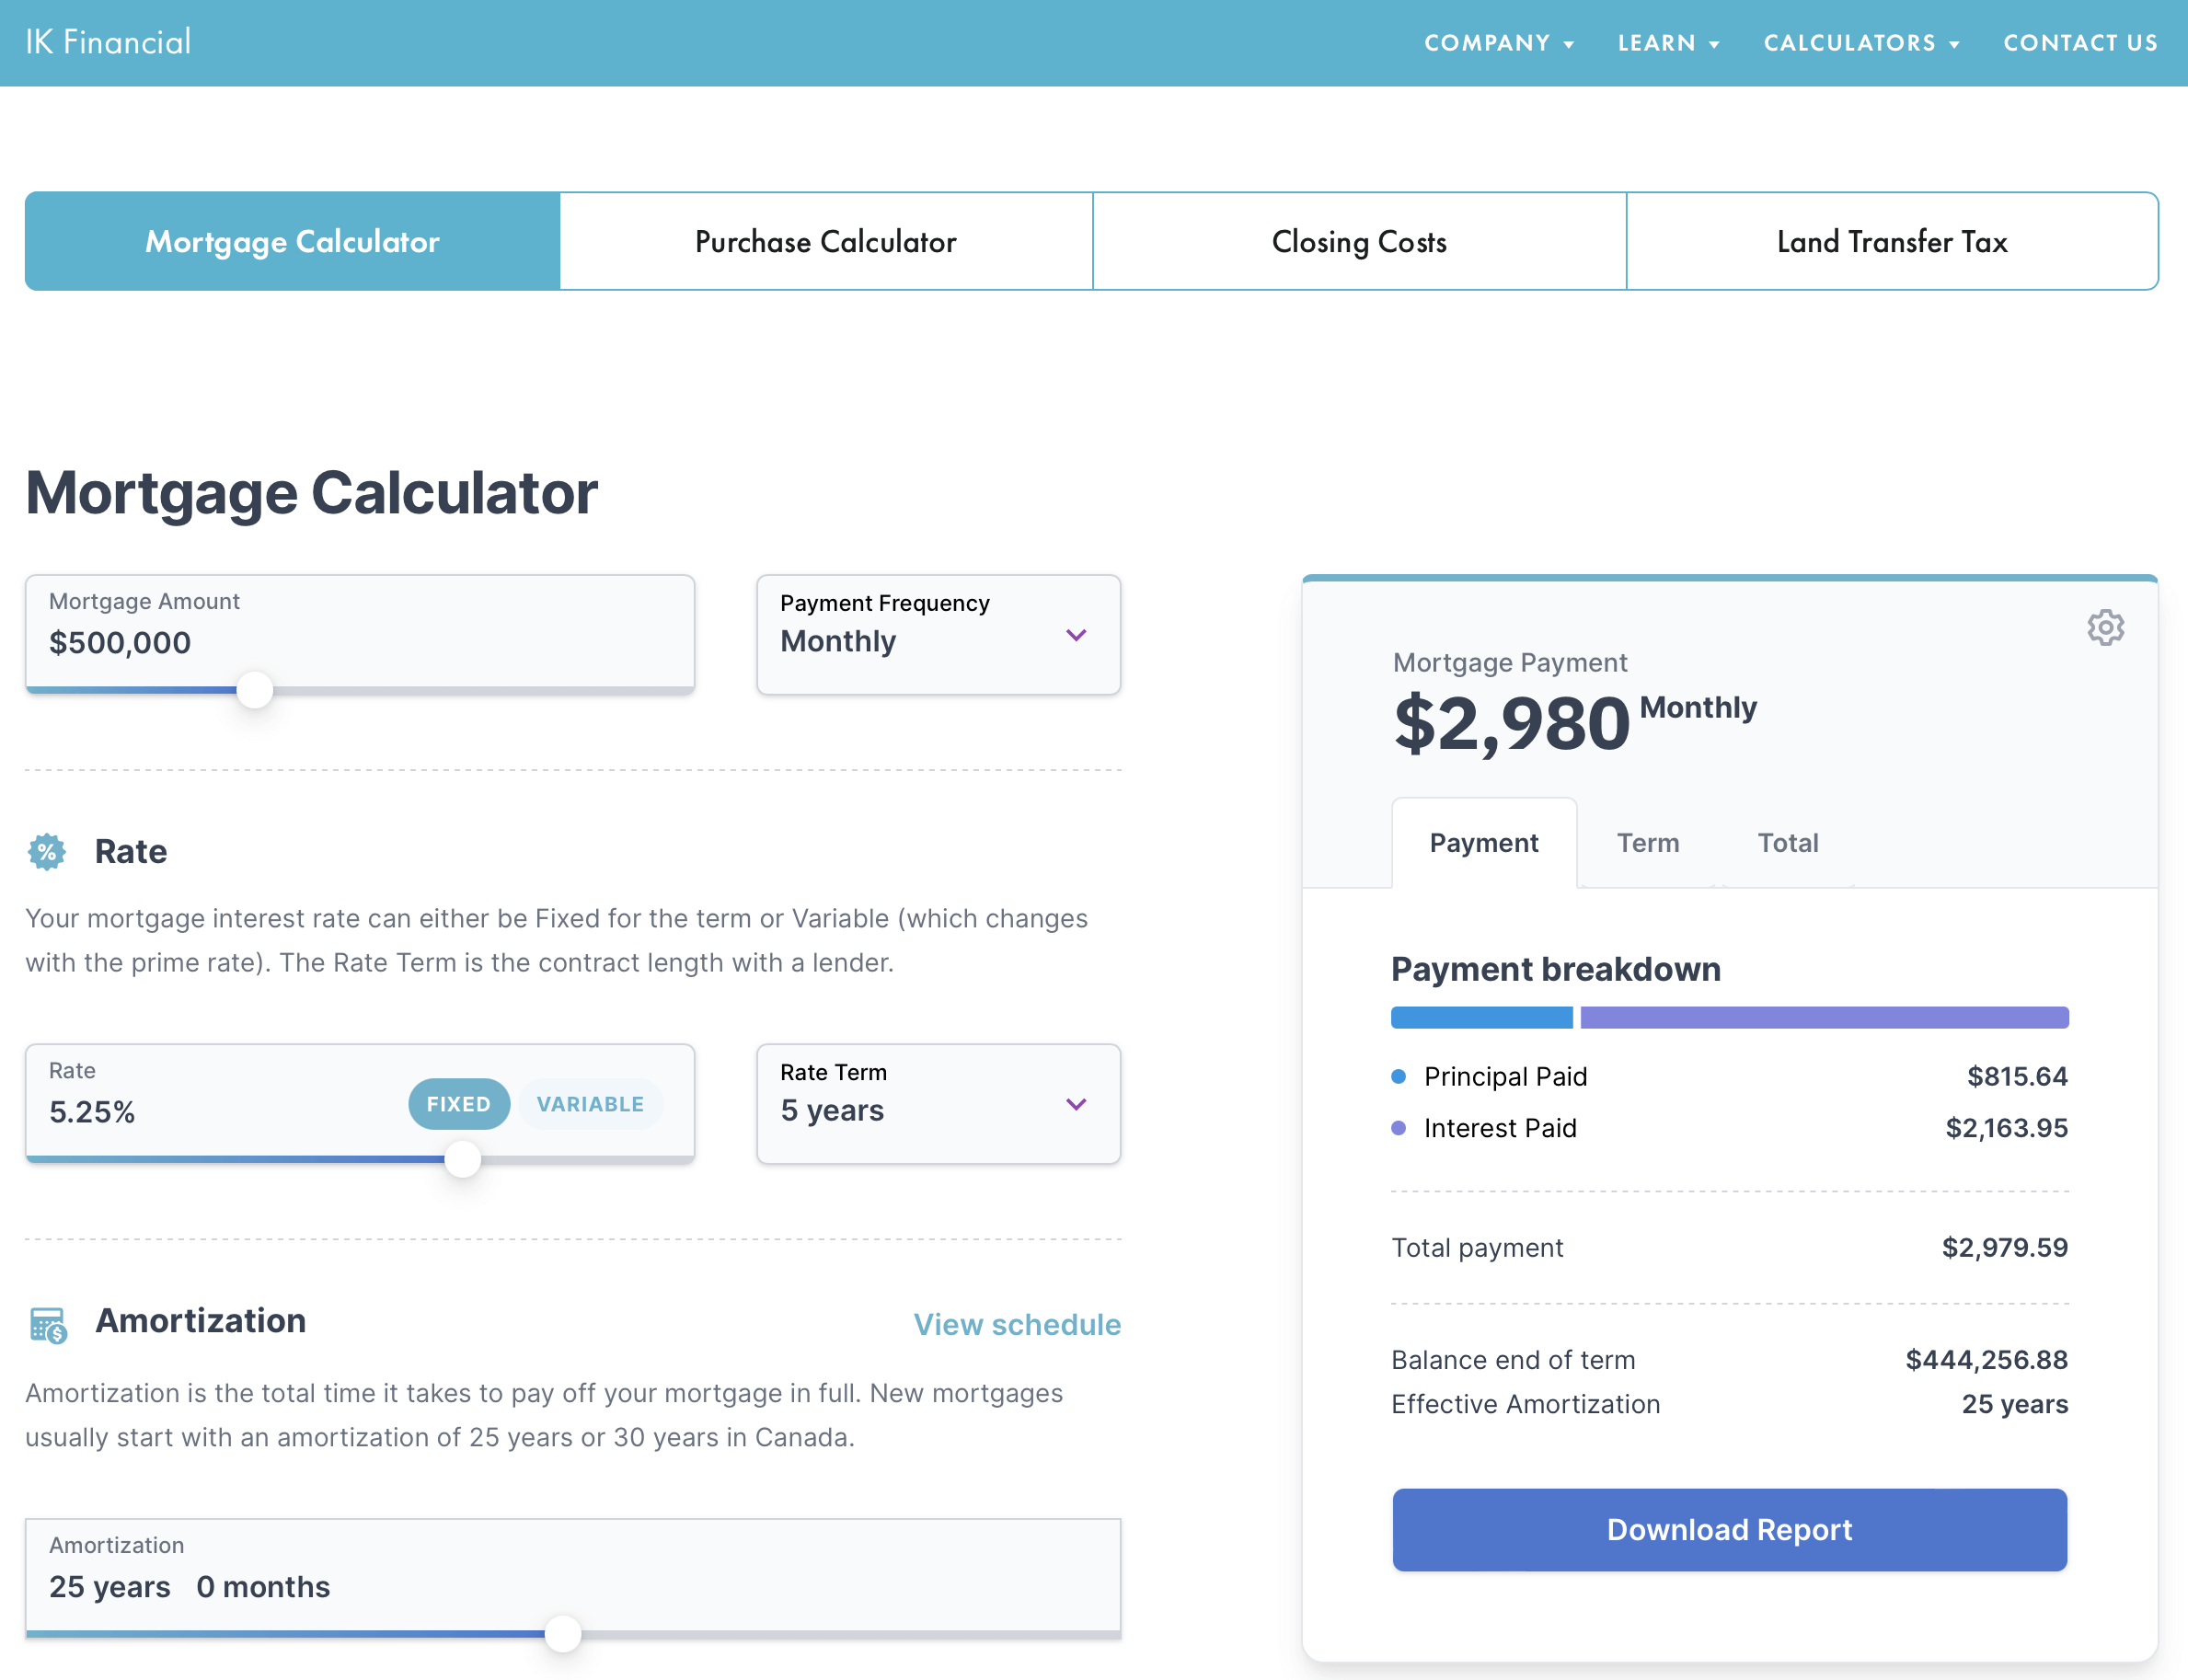
I keep a simple spreadsheet with separate tabs for property tax estimates, insurance premiums, PMI calculations, and HOA fees. The property tax tab pulls the most recent assessed value from my county's public records and applies the local millage rate. The insurance tab tracks quotes from three carriers and adjusts for deductible changes. The PMI tab automatically removes the line item once your loan balance drops below 78% of the original appraised value, which is when most lenders are required to cancel it without a formal request. The HOA tab is just a running log of monthly dues with any scheduled increases noted. For people comparing different loan scenarios, the marginal impact of an extra half-point in interest rate is often underestimated. Going from 6.5% to 7% on a $300,000, 30-year loan increases your monthly payment from $1,896 to $1,996 — exactly $100 more per month, or $36,000 over the life of the loan. That $100 difference is the same amount many people budget for a streaming subscription or a daily coffee habit. The calculation itself takes about 30 seconds in any basic Mortgage Calculator For Home, but the decision about whether to accept a slightly higher rate in exchange for lower closing costs requires understanding the break-even timeline between the two options.