Building a Mortgage Calculator G A M E from Scratch
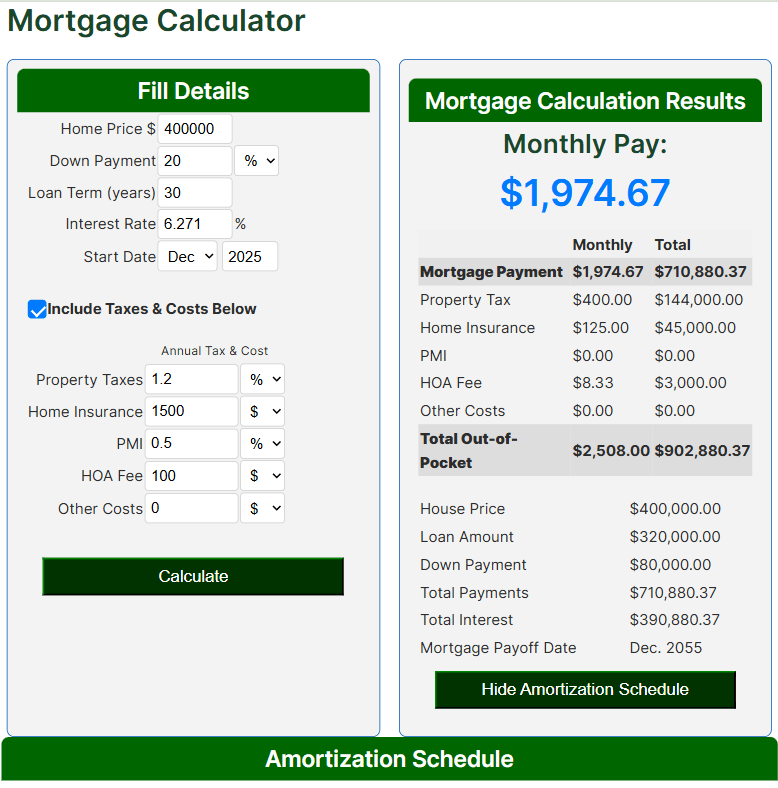
Most people treat mortgage calculators as a black box, type in a few numbers and get a monthly payment. That approach works until your loan has an ARM adjustment, property taxes that include a special assessment district, or PMI that phases out at a certain LTV. The simple version falls apart there. What follows is how I actually build a working calculator, and where the traps are. At its core it simulates a loan over its full term, month by month. You feed it principal, rate, and term. It returns monthly principal and interest, then optionally breaks out taxes, insurance, HOA, and PMI. The "game" part usually means users can tweak variables and immediately see how changes ripple through the total cost. That feedback loop is useful, but it is also where most implementations go wrong. The basic P&I calculation uses the standard amortization formula. Monthly payment equals principal times the monthly rate, divided by one minus one plus the monthly rate all raised to the negative number of payments. In code that looks like a straightforward function call. In practice the edge cases matter more than the formula itself. Rates quoted as annual percentages need to be divided by twelve. Loans with odd closing dates require a short first period. Both break naive implementations in predictable ways.
Inputs and Outputs You Should Build For
Get this part right or the rest is noise. Required fields are purchase price or current balance, down payment, interest rate, loan term, and loan type. Fixed 30-year and 15-year cover most requests. But 3/1, 5/1, 7/1 and 10/1 ARMs show up constantly in real workflows, and most lightweight calculators ignore them entirely. Add an option for hybrid inputs: user enters purchase price and LTV, then the tool derives the loan amount and suggests PMI based on that LTV. That is closer to how people actually experience a mortgage. Outputs should include monthly payment, total interest paid, total cost over the life of the loan, and an amortization schedule if the user opts in. If you add a side-by-side comparison feature, give them cumulative interest and equity graphs. Users trust what they can visualize. A bare table of numbers feels hollow after thirty seconds.
Common Pitfalls That Sink These Tools
Rounding error is the quiet killer. When you round each monthly principal and interest figure to the nearest cent inside a loop, the final payment often ends up off by three or four dollars. The fix is to calculate every month without rounding, then round only the displayed values. Adjust the last payment by whatever remains. It takes one extra line of logic and saves a dozen support tickets. PMI handling is another weak spot. Some calculators just slap on a flat 0.5 percent of the original loan amount every month until the loan hits 80 percent LTV. Real PMI can be annuity or cancellation based, can vary by credit tier, and sometimes drops automatically at 78 percent. The difference between a simplified model and a realistic one shows up as hundreds of dollars over five years. Use a tiered approach: start with a default rate, allow manual override, and optionally pull lender-specific data if your tool has access to it.
Get the Full Details

My Own Edge Case from a Recent Build
I was working on a calculator that needed to handle a loan with an odd day count. The borrower closed on the 18th of the month, and the first payment was due six days later. A standard 30-day cycle assumption broke the schedule immediately. The accrued interest for that short period was wrong, and the amortization table drifted from there. I resolved it by computing the first period as a simple interest accrual over the actual calendar days, then letting the regular formula take over from month two. I also added a toggle for user-entered closing date versus a clean first-of-month start. That toggle caught the majority of edge cases without complicating the main flow. Keep the interface responsive. If a user drags a slider for interest rate, the monthly payment should update within a frame, not after a debounce delay. Users notice lag even when they do not consciously register it. Cache the amortization schedule if you expect repeated calculations on the same parameters. Regenerating a 360-row table from scratch every time a slider moves adds up to visible stutter on modest devices. Data validation matters more than you might think. Reject negative inputs silently. Flag impossible combinations like a zero percent rate on an ARM or a down payment exceeding the purchase price. Show clear error messages, not console warnings that nobody reads. The goal is to prevent garbage output, not to impress someone with a stack trace.
Alternatives When a Custom Build Is Not Worth It
If you need something reliable fast and do not want to maintain the logic yourself, consider wrapping an existing open-source library or embedding a reputable third-party widget. The trade-off is less control over edge cases and branding, but you avoid reinventing validation, rounding, and schedule generation. For internal tools or high-traffic consumer sites, a custom build pays for itself once you account for accuracy requirements and brand consistency. The bottom line is that a mortgage calculator is only as good as the assumptions it encodes. The formula is simple. The implementation is where mistakes hide. Build carefully, test against known loan statements, and do not trust any result until you have verified it against at least one real amortization schedule.