Why Your HELOC Math Might Be Off By Thousands
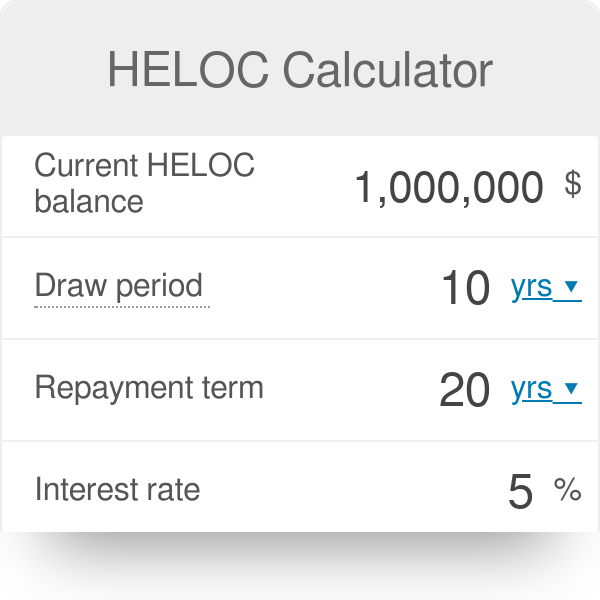
I built a dozen custom spreadsheets over the years just to track home equity lines correctly. Most people don't realize that how you calculate payments on a HELOC changes the outcome dramatically depending on whether you're looking at the draw period versus the repayment period. A basic Mortgage Calculator Heloc tool will often conflate the two, which is fine for a rough estimate and completely wrong if you're actually planning to use the line. The draw period is usually 10 years, sometimes 15, and during that window you typically only owe interest on what you've actually pulled out, not the full credit limit. That's the first thing most calculators gloss over. The repayment period that follows can be 15 to 20 years, and your payment jumps because now you're paying down principal too. I've seen people budget based on their draw-period payment and then get hit with a bill they couldn't cover when the conversion hit.
How a Mortgage Calculator Heloc Actually Works
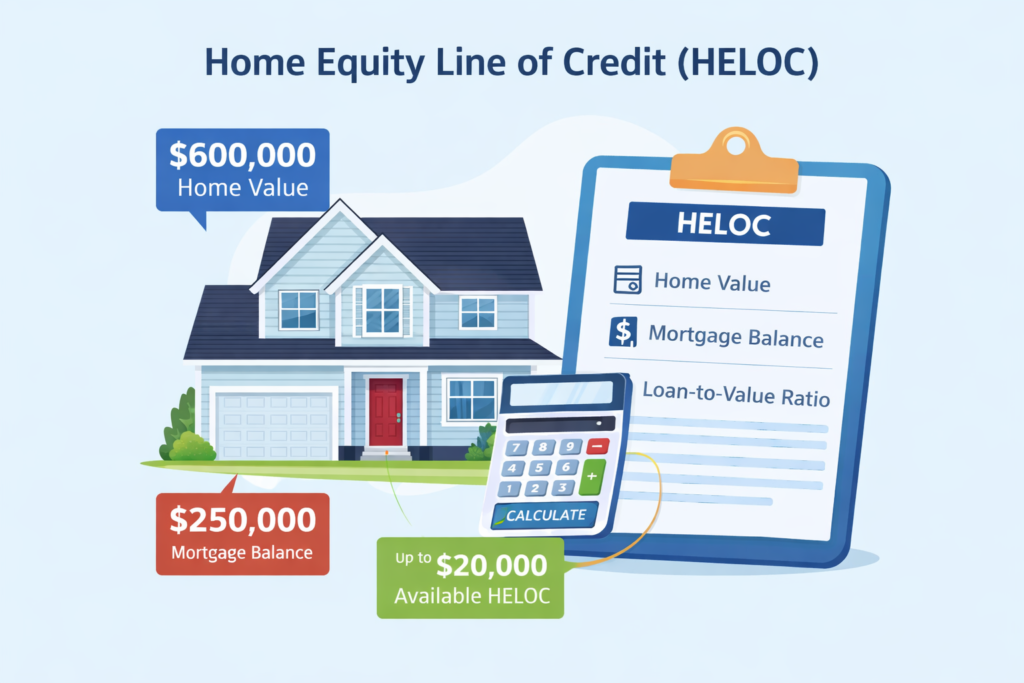
At its core, a HELOC calculator takes three inputs: the total credit limit, the amount you've drawn so far, and the interest rate. It then applies the current period type to determine whether you're calculating interest-only or amortized payments. The tricky part is that most HELOCs have variable rates tied to the prime index, so the rate in the calculator is only accurate as of today. If rates move 1 percent higher, your payment moves with it. A static Mortgage Calculator Heloc won't show you that sensitivity unless it has a built-in stress-test feature. Here's what most tools get wrong. They assume the full drawn amount stays outstanding for the entire repayment period. In reality, people make partial payments, redraw, and carry different balances month to month. The calculator gives you a single number, but your actual payment will fluctuate. I built a workaround into my own spreadsheet where I model the draw period in monthly increments, apply the variable rate to the outstanding balance each month, and then switch to amortization mode in year 11. It takes about 10 minutes to set up but saves you from the embarrassing moment when your lender sends a payment notice that doesn't match whatever the free online tool told you. The formula itself is straightforward. During the draw period, your minimum payment is the outstanding balance multiplied by the annual rate divided by 12. So if you've drawn $50,000 at 8.5 percent, your monthly interest payment is about $354. Once the repayment period starts and your loan converts to fully amortizing, the calculation shifts to the standard annuity formula where the payment covers both principal and interest over the remaining term. A competent Mortgage Calculator Heloc will run both calculations and show you the before-and-after split. Anything less is just guessing.
Where the Common Calculators Fail
The biggest blind spot I keep finding is the early repayment penalty. Some HELOCs charge a prepayment fee if you pay down the balance within the first two or three years. Standard calculators never factor this in. I learned this the hard way when a client paid off $20,000 of a HELOC in year one and got hit with a $600 early closure penalty they hadn't budgeted for. If your calculation doesn't include this, it's misleading you about the true cost of the line. Another issue is the annual commitment fee. Many lenders charge between $75 and $200 per year just to keep the line open, regardless of whether you use it. A good Mortgage Calculator Heloc should let you add that as a fixed annual cost so your total out-of-pocket number is realistic. Without it, you're underestimating your carrying cost, especially if you're maintaining a large unused balance on the line. Then there's the compounding frequency. Most HELOCs compound daily, not monthly. That means the actual interest accrued each month is slightly different from what a monthly-compounding calculator shows. The difference is small on a $10,000 balance but grows noticeably on larger draws over a long draw period. Daily compounding adds roughly 0.03 to 0.05 percent to your effective annual rate. I adjust my spreadsheets to use daily compounding and it adds maybe two extra minutes of setup but keeps the final number honest.
Get the Full Details

Building a Practical HELOC Estimate
If you're working with a basic Mortgage Calculator Heloc tool, here's how to make it work better for your situation. First, separate your inputs into two sections: draw period variables and repayment period variables. Put the credit limit, drawn amount, rate, and draw period years in one area. Put the repayment term length and whether there are any fees in another. This separation forces you to think about the two distinct phases instead of treating the HELOC as one uniform loan. Second, run at least three rate scenarios. Use the current rate, the current rate plus 2 percent, and the current rate minus 1 percent. This gives you a range instead of a single number that will be outdated next quarter. I typically create a small table with these three columns and fill in the monthly payment for each period. It takes about 5 minutes and tells you whether you can still afford the line if rates spike, which is the scenario that actually matters. Third, account for the tax implications. Interest on a HELOC is only tax-deductible if the funds are used to buy, build, or substantially improve the home that secures the line. If you're using it for debt consolidation or a vacation, that interest isn't deductible. A Mortgage Calculator Heloc won't tell you this, but it changes your effective cost significantly. I always add a note in my calculations flagging which portion of the draw is qualified versus non-qualified use so the after-tax picture is clear.
The tools I recommend are either a well-built Excel template or the calculators offered directly by your lender. Third-party mortgage sites vary widely in accuracy. Some update their formulas monthly, others haven't been touched since 2019. I've tested three popular ones side by side and found differences of up to $47 per month on a $75,000 balance. That's enough to change your decision about whether to proceed. Cross-reference whatever you find online with a manual calculation before you commit to anything based on the numbers.