How Mortgage Calculators Actually Work in Practice
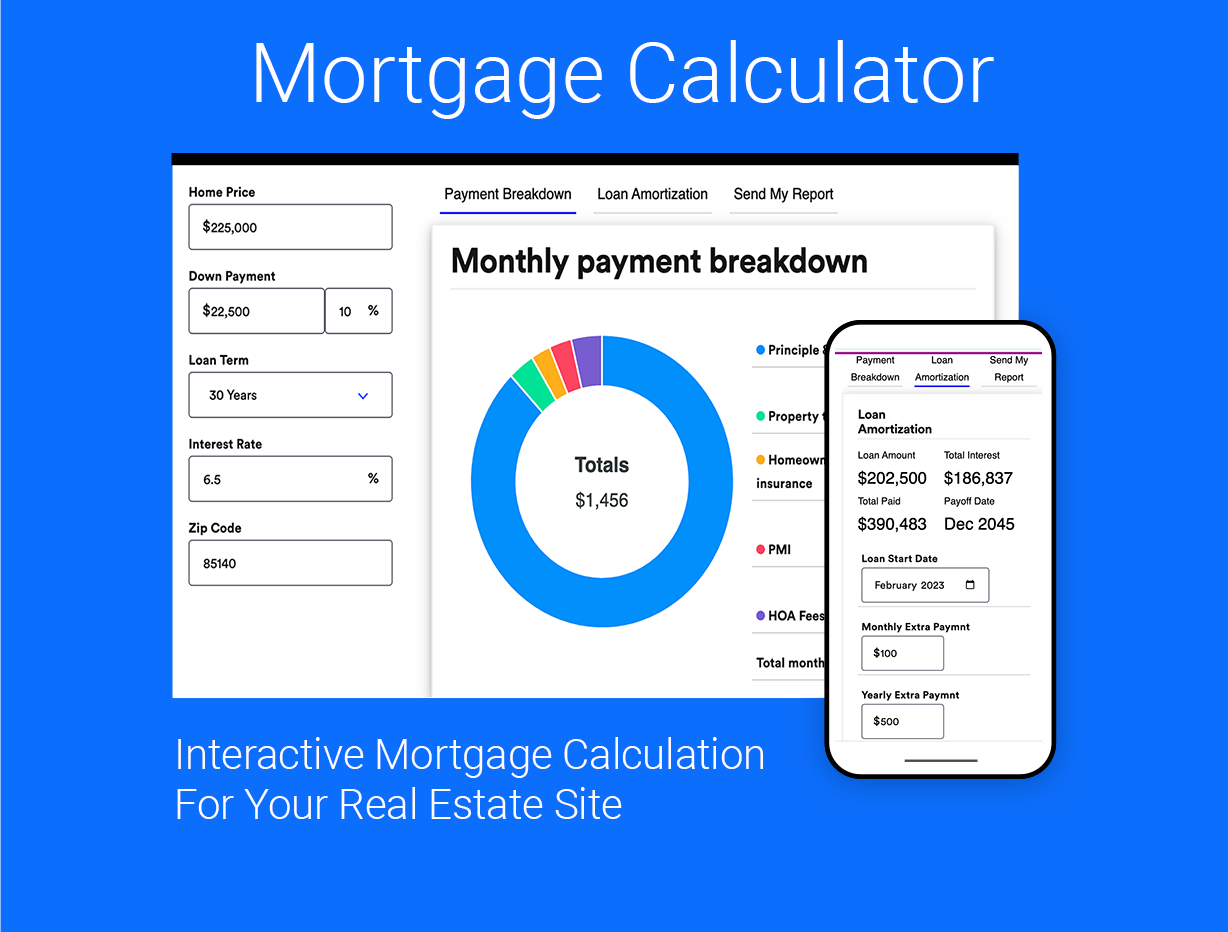
Most people grab a mortgage calculator and type in their numbers without thinking about what comes next. That is fine for a rough estimate. The real problem starts when the calculator output does not match what the lender quotes you, and you are left wondering where the discrepancy came from. I have seen this happen repeatedly in Houston, and it usually traces back to one of three things: property tax assumptions, insurance estimates, or HOA fees that the default calculator does not account for. A mortgage calculator is fundamentally a mathematical tool. It takes your loan amount, interest rate, and term and produces a monthly principal and interest payment. Then it adds estimated taxes, insurance, and any homeowners association fees to give you a total monthly housing payment. The simpler the calculator, the less it includes in that second half. The more expensive the calculator, the more variables it asks about, and the longer it takes to get an answer. Here is the straightforward breakdown of what goes into the calculation before we get into Houston-specific adjustments.
Mortgage Calculator Houston Texas
The Core Formula
Principal and interest payment comes from the standard amortization formula: M = P × [r(1+r)^n] / [(1+r)^n - 1] P is your loan amount. r is your monthly interest rate (annual rate divided by 12). n is your total number of monthly payments. This part is universal. It does not change whether you are in Houston, New York, or anywhere else. What changes is everything after that number.
The total monthly payment adds four more components: 1. Monthly principal and interest 2. Annual property tax divided by 12
Get the Full Details
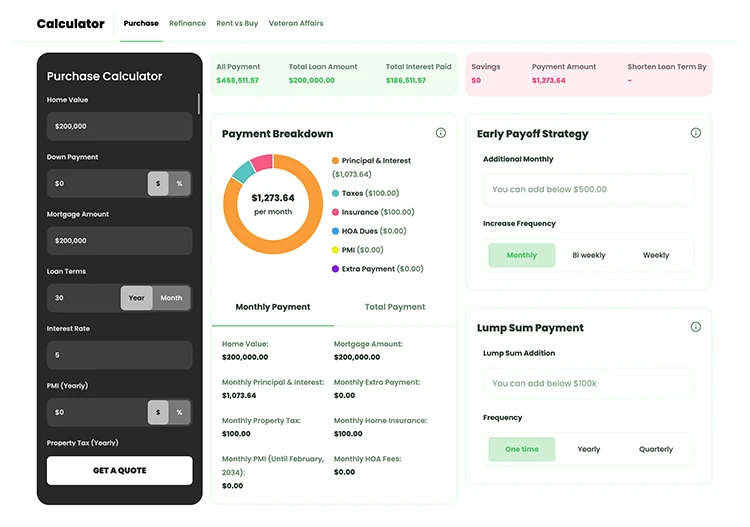
3. Annual homeowners insurance divided by 12 4. Monthly HOA fee, if applicable That last one is where Houston gets tricky. The city itself has no municipal income tax. It also has no state-level property tax relief programs that dramatically change the calculation for average buyers. What Houston does have is some of the highest property tax rates in Texas, and the rates vary significantly by which school district and county you are in.
Houston-Specific Variables That Break Generic Calculators
Generic mortgage calculators pull property tax estimates from national averages or rough county-level data. Harris County property taxes averaged around 2.3 percent of the home value in recent years, but that number means almost nothing on its own because it varies by appraisal district, homestead exemption status, and school district boundaries. A home in the Houston Independent School District pays a different rate than one in Spring Branch, Clear Creek, or Tomball. Those school district rates alone can swing your annual property tax by several thousand dollars. I ran into this exact issue last year while helping a client compare two homes in the same price range but in different school districts. The online calculator showed nearly identical monthly payments for both properties. When we pulled the actual tax records, the difference was about $180 per month in property taxes alone. The calculator had assumed the same rate for both because it defaulted to a Harris County average. That is the kind of gap that turns a comfortable payment into a financial strain if you are not prepared for it. The workaround is simple but nobody tells you about it. Before you trust any online calculator, go to the Harris County Appraisal District website. Look up the specific property tax rate for the address you are evaluating. There is a property search tool there. Enter the address. It will show you the current assessed value, the tax rate, and any exemptions already applied. Take those numbers and plug them into your calculator manually instead of letting it guess.
Homeowners Insurance in Houston
Insurance is the second major variable that generic calculators handle poorly. Houston sits in a high-risk zone for wind and hail damage. Many people do not realize this because they are coming from states where standard homeowners insurance covers everything. In Texas, wind and hail coverage is frequently sold as a separate policy or an endorsement with a much higher deductible than your standard policy. During storm season, which runs roughly April through October, those premiums can jump noticeably. A typical homeowners insurance estimate in a national calculator might show $80 to $120 per month for a $300,000 home in Texas. In Houston, you are more likely looking at $150 to $250 per month once you factor in wind/hail coverage, especially if the home is in a flood-prone area. And if the home is in a flood zone, you will also need a separate flood insurance policy through the National Flood Insurance Program or a private carrier. That is another $60 to $200 per month depending on your zone designation and elevation certificate status. Most free calculators do not ask about flood zones. They do not ask about wind deductibles. They give you a single insurance number that is almost certainly too low for Houston. The fix here is to get actual insurance quotes before you make an offer. Even a basic quote from a Texas-focused insurer will give you a more realistic monthly figure than anything a generic calculator spits out.

Down Payment and PMI Considerations
Private mortgage insurance, or PMI, applies when your down payment is less than 20 percent of the home value. This is not optional. Lenders require it. The cost typically runs between 0.5 percent and 1 percent of the loan amount annually, split into monthly payments. On a $350,000 loan with a 5 percent down payment, you are looking at roughly $145 to $290 per month in PMI until you reach 20 percent equity. Some calculators include PMI automatically. Many do not. If your calculator does not mention it, check the fine print or add it manually. The rule of thumb for when PMI drops off is reaching 20 percent equity in the home, either through payments or appreciation. Under the Homeowners Protection Act, lenders are required to automatically terminate PMI once you reach 22 percent equity based on the original amortization schedule, but you can request termination at 20 percent. In practice, most people just wait for the automatic removal. There is another detail that trips people up in Texas. The state allows for a homestead exemption that reduces the taxable value of your primary residence. For school district taxes, the first $100,000 of your home value is exempt from taxation. That translates to real savings on your monthly payment if you qualify. You need to apply for this exemption through the Harris County Appraisal District, and it is not automatic. A $300,000 home with a homestead exemption saves you roughly $1,560 to $2,340 in annual property taxes compared to the same home without the exemption, depending on the school district rate.
A Practical Walkthrough With Real Numbers
Let me show you how this works end to end with a realistic Houston scenario. Say you are looking at a $350,000 home in the Clear Creek Independent School District. You put 10 percent down, which leaves a loan amount of $315,000. The current interest rate is 6.75 percent for a 30-year fixed. First, principal and interest. Using the formula above: P equals $315,000. r equals 0.005625 (6.75 divided by 1200). n equals 360. The result is approximately $2,043 per month. Second, property tax. Clear Creek ISD combined with Harris County and other taxing units typically lands somewhere in the 2.5 to 2.8 percent range. With the homestead exemption applied, let us estimate 2.6 percent of the appraised value. That is $9,100 annually, or $758 per month.
Third, insurance. A realistic homeowners policy with wind/hail coverage for this price range in this area runs about $180 per month. If the home is in a moderate flood risk zone, add a flood policy at roughly $100 per month. Total insurance comes to $280 per month. Fourth, HOA. This varies wildly. Some Houston subdivisions have no HOA. Others charge $200 to $500 per month. Let us assume $150 for this example. Putting it all together: $2,043 plus $758 plus $280 plus $150. Your total monthly payment is approximately $3,231. Without factoring in the homestead exemption, property taxes alone would have pushed that number up by another $130 or so. That is a meaningful difference when you are stretching your budget.
Now compare that to what a basic online calculator would show. Most would give you the $2,043 principal and interest number and then add a generic tax estimate based on national averages. You might see a total payment in the $2,600 to $2,800 range. The gap between that estimate and your actual payment is $400 to $600 per month. Over five years, that is $24,000 to $36,000 in unexpected costs.
How to Build an Accurate Houston-Specific Calculation
The most reliable approach combines a few steps. Start with a mortgage calculator that lets you customize every input rather than one that uses default assumptions. The U.S. Department of Housing and Urban Development maintains a free calculator that allows you to enter custom tax and insurance figures. So does Freddie Mac's calculator. These are better than the random results you get from search engine ads. Then pull the actual numbers from real sources. The Harris County Appraisal District website gives you property tax rates. Contact two or three insurance agents who work in Houston and ask for quotes on a policy that includes wind and hail coverage. Check whether the property is in a flood zone using the FEMA flood map service center. Look up the HOA fees in the seller disclosure or the subdivision records. Enter all of those real numbers into your calculator. The resulting payment will be far closer to what your lender will actually quote you. It will not be exact because lenders may have slightly different assumptions about insurance costs or tax escalations, but it will be in the right ballpark.
When Calculators Completely Fail You
There are situations where even the most detailed mortgage calculator gives you misleading information. The first is adjustable-rate mortgages. If you are considering an ARM, the calculator will show you the initial rate for the first period, which might be 5.5 percent for a 5/1 ARM. But after five years, the rate adjusts based on an index plus a margin. The calculator cannot predict where rates will be in five years. The payment could go up significantly, or it could stay relatively stable. You need to look at the fully indexed rate, which is the maximum rate the loan could reach, and calculate what your payment would look like at that rate. That gives you a worst-case scenario to plan around. The second failure point is jumbo loans. If your loan amount exceeds the conforming loan limits set by the Federal Housing Finance Agency, which was $766,550 in most of Texas for 2024 and 2025, you are dealing with a jumbo loan. Jumbo loans typically have higher interest rates and stricter qualification requirements. Some calculators do not account for these differences. They treat a $400,000 loan the same way regardless of whether it is conforming or jumbo. In reality, a jumbo loan at 7 percent might look very different from a conforming loan at 6.75 percent once you factor in the lender's required reserve reserves and credit score thresholds. The third failure point is FHA and VA loans. These government-backed loans have different structures. FHA loans require an upfront mortgage insurance premium that is typically financed into the loan plus a monthly MIP that lasts for the life of the loan if you put less than 10 percent down. VA loans have a funding fee instead of mortgage insurance, and the fee varies based on your military status and down payment amount. Standard mortgage calculators often do not handle these nuances correctly. You need calculators specifically designed for FHA or VA loans, or you need to add those costs manually.

Download Options and Tools
There is no single downloadable mortgage calculator that is universally superior for Houston because the best tool depends on what you value. If you want something you can run offline, Excel spreadsheets are the most flexible option. There are plenty of free mortgage amortization templates available. The advantage of an Excel spreadsheet is that you can save your calculations, adjust variables easily, and compare multiple scenarios side by side. The disadvantage is that you need to know how to build or configure the spreadsheet correctly. For people who prefer a graphical interface, the HUD mortgage calculator and the Freddie Mac calculator are both free and web-based. They do not require downloads. They allow you to input custom property tax, insurance, and HOA values. They also provide amortization schedules, which show you how your equity builds over time. This is useful for understanding how quickly you move toward the 20 percent equity threshold that eliminates PMI. If you want something more visually polished, the Bankrate mortgage calculator and the NerdWallet calculator are both solid choices. They include sliders for down payment, interest rate, and loan term. They also factor in PMI automatically when your down payment is below 20 percent. The tradeoff is that their default tax and insurance estimates are still based on national averages, so you need to override those fields with Houston-specific numbers to get accurate results.
A Final Note on What This Does Not Tell You
Mortgage calculators tell you what your payment will be. They do not tell you whether you can afford the home. They do not account for closing costs, which in Houston typically run between 2 percent and 5 percent of the loan amount. They do not factor in moving expenses, repair costs, or furniture. A home that shows a manageable payment on paper might still be unaffordable once you include the $8,000 to $17,500 in closing costs you need to bring to the table. They also do not tell you about the broader financial picture. Taking on a $3,200 per month housing payment means that money is not going toward retirement savings, emergency funds, debt repayment, or other obligations. In Houston, where the job market can be volatile depending on your industry, having a comfortable buffer between your housing payment and your take-home pay is more important than finding the lowest possible rate. A slightly higher rate on a smaller loan often makes more sense than maximizing your purchasing power and stretching yourself thin. The bottom line is that a mortgage calculator is a starting point, not a finish line. The numbers it produces are only as good as the inputs you feed into it. For Houston specifically, that means doing the extra work of looking up actual property tax rates, getting real insurance quotes, and checking flood zone designations before you trust the output. The fifteen minutes you spend on that research will save you from some very unpleasant surprises down the road.