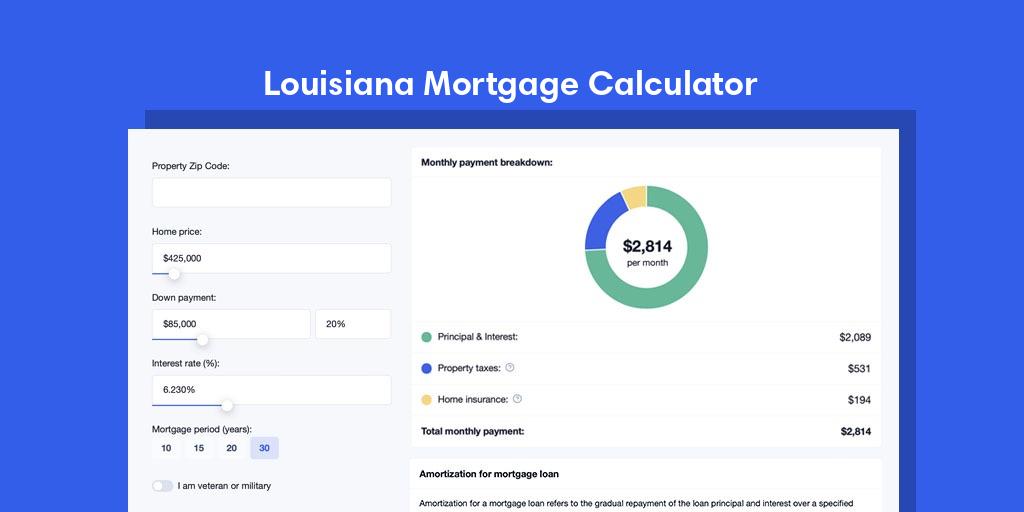
Using a Mortgage Calculator for Louisiana Home Loans
Most people grab a generic mortgage calculator online and punch in their numbers, then wonder why the result doesn't match what their lender quoted. Louisiana has a few quirks that throw off standard calculators if you aren't accounting for them.
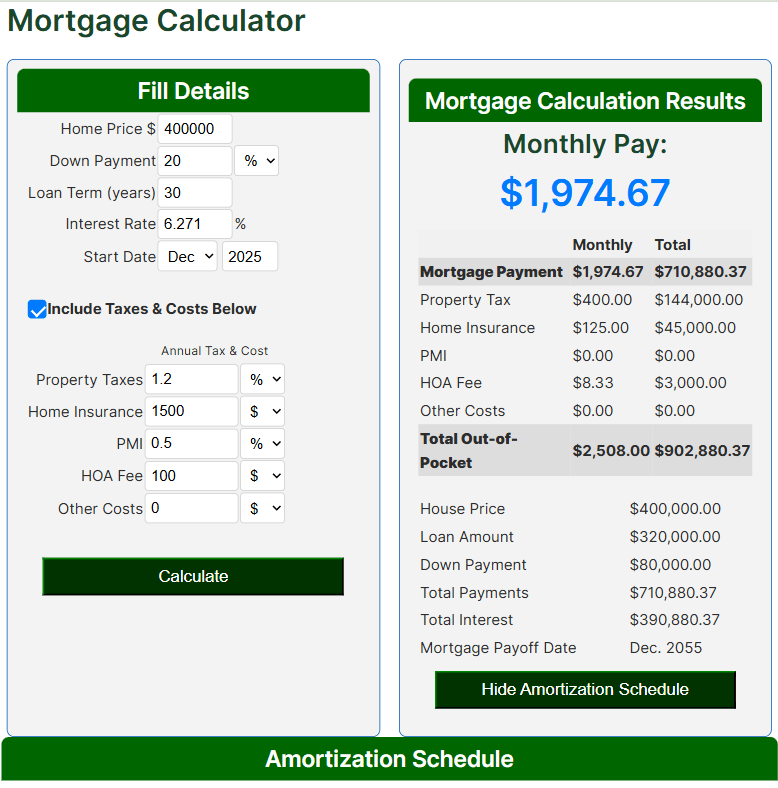
The basic math is straightforward: your monthly payment comes from principal, interest, taxes, and insurance, abbreviated PITI when you're putting it all together. The principal and interest piece uses the standard amortization formula, which any decent calculator handles without trouble. Where things get tricky in Louisiana is the tax and insurance side.
Mortgage Calculator Louisiana: What You Need to Know
Louisiana's property tax rates vary wildly by parish. I worked with a client last year who was looking at a house in Jefferson Parish and another in Caddo Parish. Same purchase price, same loan amount. The Jefferson property taxed at around 0.55 percent effective rate while the Caddo one was closer to 1.1 percent. That's a double difference in annual taxes, which changes your monthly PITI estimate by nearly two hundred dollars. Most online calculators default to national averages that don't reflect this.
Here's the workaround I always tell people to use. Don't rely on the calculator's built-in tax estimate. Look up the actual annual property tax for the specific address or neighborhood on the parish assessor's website. Most Louisiana parishes have this data public. Divide that annual number by twelve and plug it into the tax field manually. Same goes for homeowners insurance. Louisiana's exposure to hurricanes and flood zones means insurance premiums are significantly higher than the national average, especially in coastal parishes like Plaquemines, St. Bernard, and Terrebonne. I've seen quarterly premiums hit four figures in those areas.
Another thing people miss is the homestead exemption. Louisiana offers a homestead exemption that can reduce your taxable value by up to twenty-five thousand dollars for your primary residence. If you're calculating your expected payment as a buyer rather than already owning the home, make sure the calculator or you account for this properly. Without it, your estimated taxes will be inflated.
The Flood Zone Factor
This is the one that catches people off guard. If the property sits in a FEMA flood zone, which a lot of Louisiana properties do, you'll need flood insurance. That's separate from homeowners insurance and it adds to your monthly payment. Rates depend on your zone designation, elevation certificate status, and whether the community participates in the National Flood Insurance Program's Community Rating System. A Zone AE property in Baton Rouge might run you two to four thousand dollars annually for flood insurance. Zone X properties in higher-elevation areas of Natchitoches Parish might not require it at all.
When I'm helping people run numbers, I always check the flood zone first before doing anything else. It changes the calculation more than any other single factor in this state.
How to Actually Use This
Grab a Mortgage Calculator Louisiana tool that lets you input custom tax and insurance amounts. Some free ones are fine. Others will push you toward their affiliate lenders and feed you manipulated numbers. The good ones let you override every field.
Start with the purchase price and your down payment. Louisiana has some state-specific assistance programs like the Louisiana State Housing Authority's first-time buyer programs that can affect your down payment requirements and sometimes offer favorable rates. Check if you qualify before you lock in a loan amount.
Enter your interest rate. Current rates fluctuate daily. Get a real quote from a lender rather than guessing. The difference between 6.5 and 7 percent on a three hundred thousand dollar loan over thirty years is roughly two hundred twenty dollars per month. That's substantial.
Now the Louisiana-specific adjustments. Pull the property tax from the assessor's site for that exact address. Divide by twelve. Enter it. Look up flood zone status. If it's in a flood zone, get a flood insurance quote. Divide by twelve. Add it to your insurance field. Run the calculation.
When Calculators Fail You
These tools won't account for special assessments, homeowners association fees, or mello-roos bonds, though mello-roos is more common in California than Louisiana. They also can't factor in loan programs with unique structures like Arkansas Valley Agricultural Development loans or certain FHA variants that have different processing timelines affecting your rate lock.
If you're looking at a fixer-upper in New Orleans' Ninth Ward or a rural property outside of Shreveport, the calculator gives you a baseline but nothing more. You'll still need a local lender who understands Louisiana's specific requirements, particularly around hurricane-resistant construction standards that some parishes enforce.
The bottom line is that a Mortgage Calculator Louisiana resource is useful for initial screening but shouldn't be treated as final. Get real numbers from the assessor, your insurance agent, and a local lender before you make any decisions based on whatever the calculator spits out.