How to Actually Use a Mortgage Calculator for Massachusetts Properties
Most people grab a generic mortgage calculator, punch in their numbers, and call it a day. It doesn't work that way in Massachusetts. The state has specific property tax rates, mortgage recording taxes, and insurance requirements that change your actual monthly payment by a few hundred dollars compared to a national average calculator. I found this out the hard way during a closings in 2019 when a buyer walked away because the quote from the lender's calculator didn't match what we were getting at the title company.
Mortgage Calculator Massachusetts: What You Need to Know Before Using One
A mortgage calculator in this state needs to account for items that standard calculators ignore. Massachusetts properties carry some of the highest local property tax rates in the country, particularly in places like Winchester or Brookline where effective rates can exceed 2 percent. That is not included in a typical Zillow estimate or a national mortgage calculator. You also have the Massachusetts mortgage recording tax, which is 0.46 percent of the loan amount, plus a local option tax in some cities and towns. That recording tax goes directly into your closing costs and shows up on your HUD-1 settlement statement, but it is easy to miss if your calculator does not ask for it.
Insurance is another piece. Coastal towns like those in Barnstable County require flood insurance on many properties, and windstorm coverage is sometimes separately quoted. A basic calculator will assume a standard homeowners policy rate and your payment will be off by $40 to $120 per month.
Here is the practical approach. I use a calculator that lets me manually enter the property tax rate instead of relying on a preloaded average. Then I add the recording tax to my closing cost estimate and run a separate insurance comparison for flood zones. It takes about twenty minutes longer than punching numbers into a web form, but it saves you from the shock of seeing your actual PITI payment at closing.
I ran into a specific issue last year working with a client looking at a condo in Somerville. The association fee was listed in the MLS but the calculator did not have a field for HOA dues, and the lender's own tool defaulted to zero. That changed the debt-to-income calculation enough that my client barely qualified. The workaround was simple: I added the monthly common charges directly to the housing expense line in the underwriting spreadsheet rather than treating them as a separate variable. Lenders fold HOA fees into the front-end ratio, so entering them correctly matters. The difference between passing and failing qualification in that scenario was roughly $28 a month.
The Numbers You Should Always Double Check
Property taxes in Massachusetts are assessed at the municipal level and reassessed periodically. Some towns do semiannual revaluations. If you are buying a home that was recently reassessed, the tax bill shown online might reflect the old valuation. Verify the current year's tax amount with the city or town clerk's office. I have seen discrepancies of up to $3,000 annually between what a calculator estimates and the actual bill because the assessor had not updated the system yet.
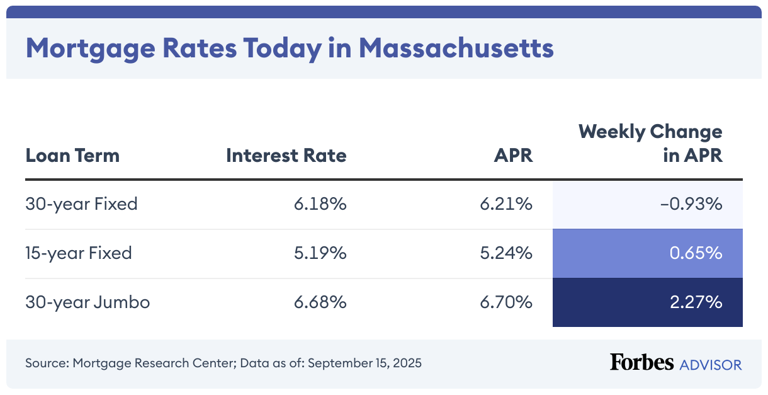
Interest rates also behave differently here than in other states. Massachusetts has a higher concentration of jumbo loans because median home prices in the Boston metro exceed the conforming loan limits. Jumbo rates can be slightly lower or slightly higher depending on the market, and they often require different down payment thresholds. If you are working with a loan above the conforming limit, make sure your calculator is set to jumbo terms. Using a conforming rate on a jumbo loan will give you a number that is off by approximately 0.125 to 0.375 percent on the interest rate, which compounds significantly over a 30-year term.
Another thing people miss: Massachusetts allows property tax deferrals for seniors and veterans. If you qualify, your effective monthly tax expense drops, but not every calculator has a toggle for that. I keep a separate spreadsheet for those cases and adjust the tax line manually rather than trust the output.
Common Pitfalls That Waste Time
The biggest mistake is assuming the calculator output equals what the lender will actually give you. Calculators do not factor in credit score adjustments, loan type differences, or lender-specific fees. A rate quote from a calculator showing 6.5 percent might become 6.875 percent once your credit profile and loan program are applied. The gap is usually small but it adds up.
Another pitfall is rounding. Some calculators round property tax estimates to the nearest hundred dollars. On a $750,000 home in a high-tax town, that rounding error can swing your monthly estimate by $25 or more. Enter the exact tax figure from the most recent bill whenever you can.
Private mortgage insurance is handled differently across lenders. Some calculate PMI as a single annual percentage of the loan balance. Others use a tiered system based on loan-to-value ratio and credit score. A calculator that assumes a flat rate will understate your payment if your LTV is above 80 percent and your credit is below 740. Check the specific PMI table for the loan program you are targeting instead of relying on a generic assumption.
What to Do When the Calculator Fails You
No online tool covers every edge case in Massachusetts. When the calculator cannot accommodate a specific situation, go to the source documents. Pull the latest property tax bill, confirm the mortgage recording tax rate with the registry of deeds for the county where the property sits, and get an insurance quote for your exact address before you run the numbers again. This usually takes about fifteen minutes and produces a more accurate result than any calculator.
For first-time buyers, I recommend running three separate estimates: one from a national calculator, one from your lender's internal tool, and one you build yourself using actual document figures. The variance between them is often where the real details hide. If all three numbers are within $50 of each other, you are in a reasonable ballpark. If they diverge more than that, dig into which assumption each one is making.
Mortgage Calculator Massachusetts Tools Worth Using
The Massachusetts Office of Consumer Affairs and Business Regulation maintains some resources, but their tools are basic. Most agents and borrowers end up using a combination of the Loan Simulator from the Consumer Financial Protection Bureau alongside their own adjusted spreadsheets. The CFPB tool is free, does not require an account, and lets you customize closing cost lines, which helps when you are adding recording taxes and local fees that standard models omit. Pair that with a spreadsheet where you plug in verified tax amounts and insurance quotes, and you get a much tighter estimate than any standalone online calculator.
I do not recommend paying for a premium mortgage planning software unless you are processing more than ten transactions a year. The free tools plus manual verification cover the vast majority of cases, and the extra cost does not produce meaningfully different results for most buyers.
Gallery Mortgage Calculator Massachusetts
How To Use a Massachusetts Mortgage Calculator - MBA Mortgage
Massachusetts Mortgage Calculator With PITI, HOA, and DTI
Mortgage Calculator: Buying a Home in Massachusetts - YouTube
ONE Mortgage unveils new calculator - Massachusetts Housing Partnership
Current Massachusetts mortgage and refinance rates