Figuring Out Your Mortgage Payment in Minnesota
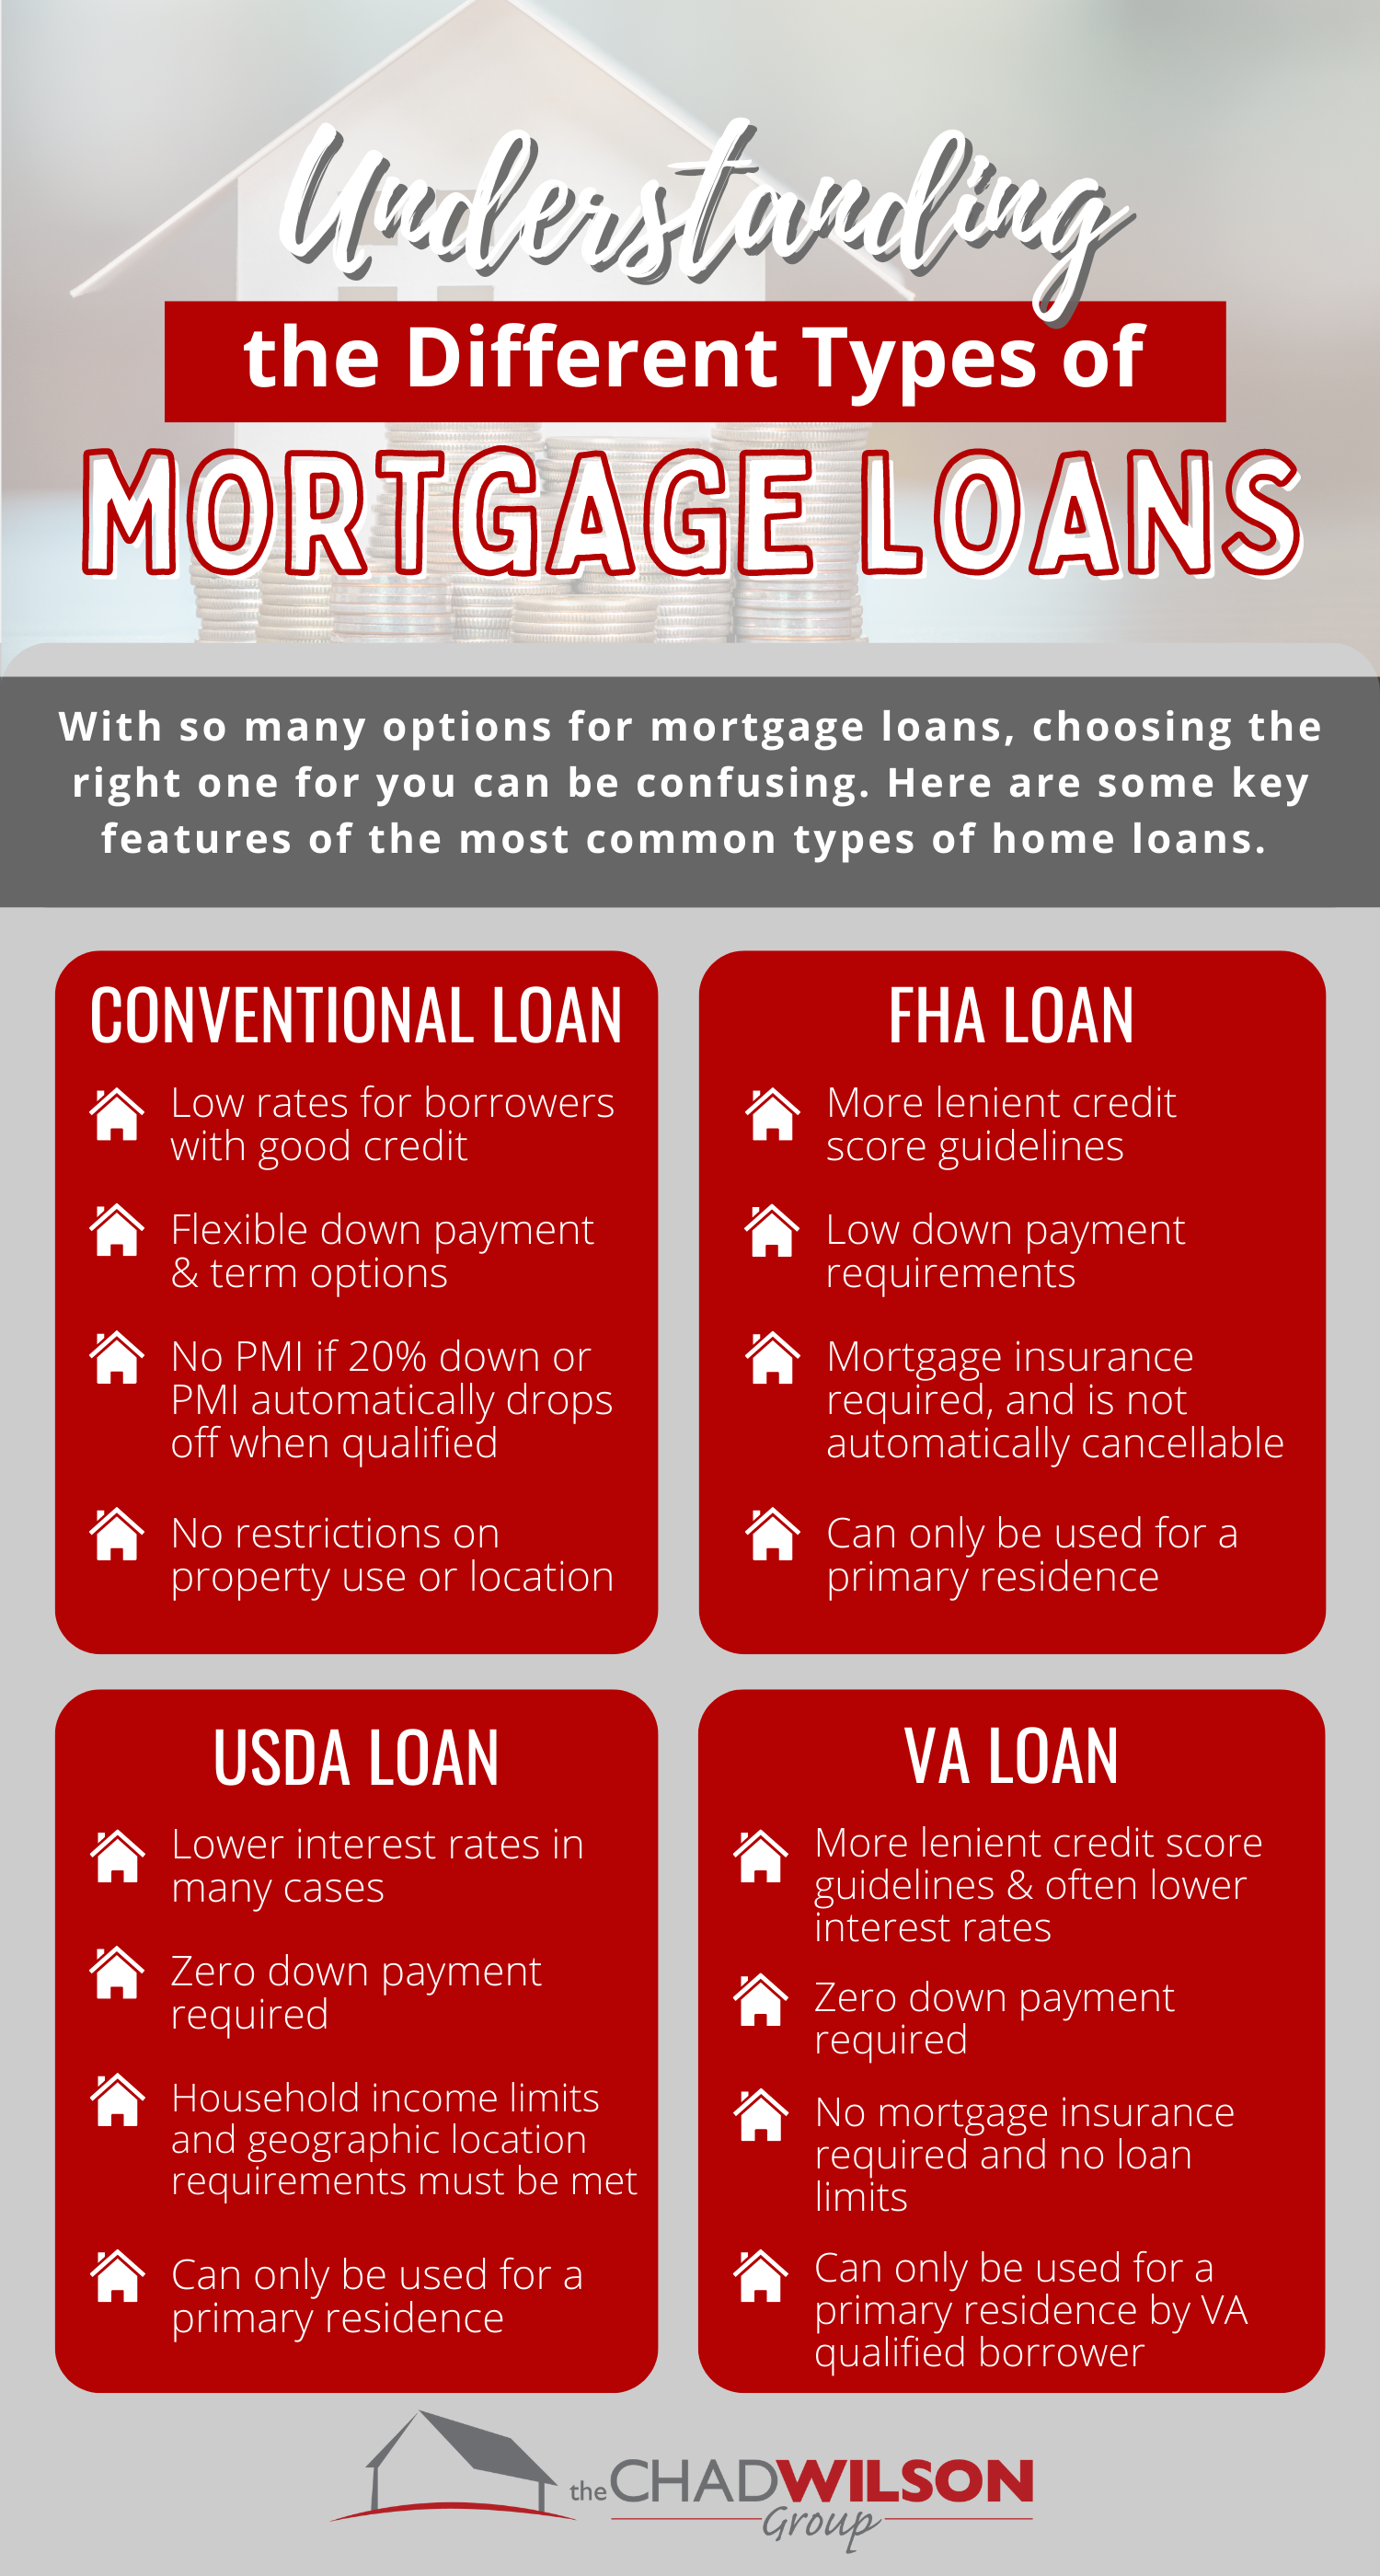
The standard mortgage calculators you find online don't really work for Minnesota the way they work for other states. I ran into this repeatedly when helping clients here. Property taxes, insurance, and the specific loan programs available in this state change the payment enough that a generic calculator will undershoot by a significant margin, sometimes $200 to $400 a month depending on where you are. I stopped recommending national calculators around 2018. They don't account for Minnesota's county-level tax variation, the specific MI requirements we deal with here, or the FHA and conventional loan program quirks that matter in this market. Instead, I use a localized version that pulls Minnesota-specific parameters directly.
Mortgage Calculator Minnesota workflow
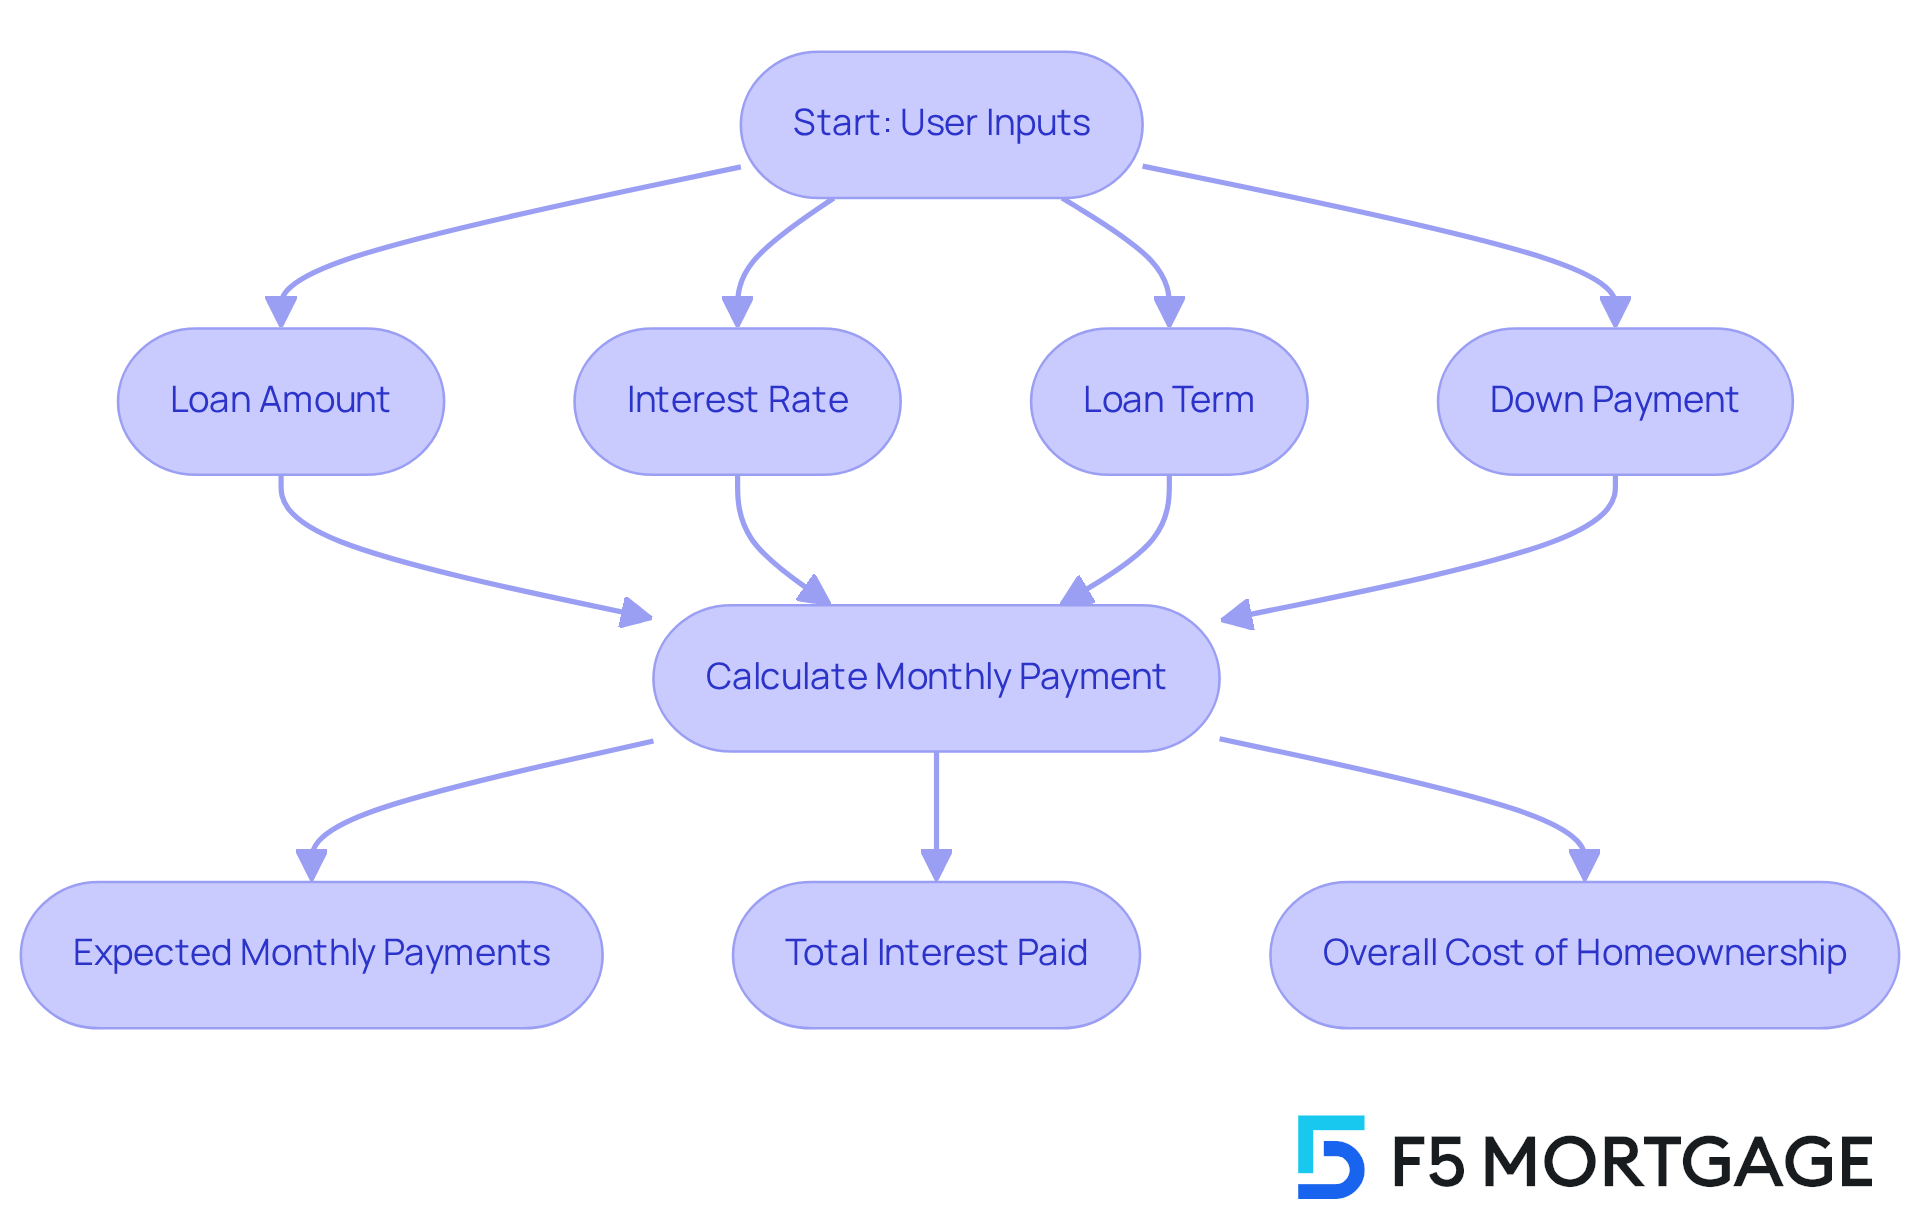
Start by opening a mortgage calculator that allows custom input for property tax rate, home insurance, and HOA. Most national tools hardcode those values or use a single national average. For Minnesota, you need the actual county tax rate. Pick a site or spreadsheet where you can enter the mill levy for your specific county. Hennepin, Ramsey, Dakota, and Washington counties all have different rates. Outside those, the range is usually lower but not always predictable. Enter your loan amount, interest rate, and term first. Then adjust the property tax field to match your county. Use your actual home insurance estimate. Don't use the national average of $1,200 a year. Minnesota averages around $1,800 to $2,600 depending on the area and the age of the home. Add HOA if applicable. That gives you the monthly PITI number you should be working with. One thing most people miss: Minnesota has a homestead exemption that affects property taxes differently than other states. If you are buying a primary residence, the exemption reduces the taxable value. You need to factor that into your tax calculation or the calculator will overstate your tax payment. I built a simple spreadsheet workaround where I subtract the homestead exemption amount from the assessed value before multiplying by the county rate. It takes about five minutes to set up once.
For Minnesota-specific loan programs, look into MN Housing Finance Agency options. They offer down payment assistance and favorable rates for qualifying buyers. The calculators on their site already include the state-level adjustments. If you are working with a lender who offers these programs, you should be using their numbers rather than a generic calculator. The difference can be meaningful, especially on the interest rate and closing cost side.
Get the Full Details
Common pitfalls I see people make
Using a national average for property tax. This is the biggest error. Minnesota property taxes are high compared to the national average and they vary wildly by county. A $300,000 home in one county could have a $4,000 annual tax bill while a similar home in another county has a $2,200 bill. The calculator needs to reflect the actual county you are buying in. If you don't know the county rate, check the county auditor's website for the current mill levy. It takes two minutes and saves you from a major budgeting mistake. Ignoring flood zone requirements. Minnesota has flood zones, especially near the Mississippi River and Lake Superior. If your property is in a flood zone, you will need flood insurance on top of your standard homeowners policy. Most calculators don't include this by default. Check the FEMA flood map for your address before you run the numbers. Flood insurance can add $600 to $2,000 a year depending on the zone. The second pitfall is assuming your rate will match what you see on a national calculator's teaser rate. Minnesota lenders advertise rates that vary by credit score, loan type, and points. A 6.5% rate might look available but actually require a specific credit score and point structure. Get a Loan Estimate from a local lender before you rely on any calculator number. It gives you the actual rate and terms after they pull your credit and verify the property.
I had a client who used a generic calculator last year and thought her payment would be around $1,400. The real payment came out closer to $1,750 once we factored in the correct Hennepin County tax rate, her home insurance, and the required private mortgage insurance at her 8% down payment. She had been saving for three years based on the wrong number. We recalibrated and adjusted the offer accordingly, but it was a close call. That is why I push people toward Minnesota-adjusted calculators now.
What this actually feels like in practice
You sit down, enter the basics, and get a number that is in the ballpark. Then you adjust the variables one by one and see how sensitive your payment is to each one. Property tax has the biggest impact after interest rate. Insurance is next. PMI or mortgage insurance is the third variable that swings the number. If you can put 20% down, you eliminate PMI and your payment drops noticeably. For down payments under 20%, PMI adds $50 to $150 a month depending on the loan size and your credit score. If you want to do this yourself, download a spreadsheet version that lets you toggle county rates. Or use a Minnesota-specific calculator if you can find one that is actually maintained. Many sites claim to be state-specific but they haven't updated their tax assumptions in years. Check the date on their data if they list it. Anything older than two years is probably stale. The numbers won't be perfect until you get a Loan Estimate from a lender. A calculator gives you a framework. It tells you whether a house is in your range or whether you are looking at a payment you cannot afford. It does not replace underwriting. Lenders will run their own numbers and may find issues like debt-to-income ratios or appraisal gaps that the calculator never sees. Use the calculator for initial screening. Then get the Loan Estimate for the real picture.

If you are shopping around, request Loan Estimates from at least two lenders. Compare the interest rate, points, and closing costs side by side. The monthly payment difference between two lenders offering slightly different rates can add up to thousands over the life of the loan. A half-point rate difference on a $300,000 loan at 30 years changes your payment by roughly $80 a month. Over ten years that is almost $10,000. Not worth ignoring just because a national calculator said the rate looked similar to another one. I keep a short list of lenders who give me accurate, comparable Loan Estimates so I can run these numbers quickly. It saves time and keeps my clients from getting sticker shock later. If you are doing this alone, just ask for the estimates upfront and compare them directly. The process is not complicated but skipping it will cost you money.