Getting Your Numbers Right Before You Talk to a Lender
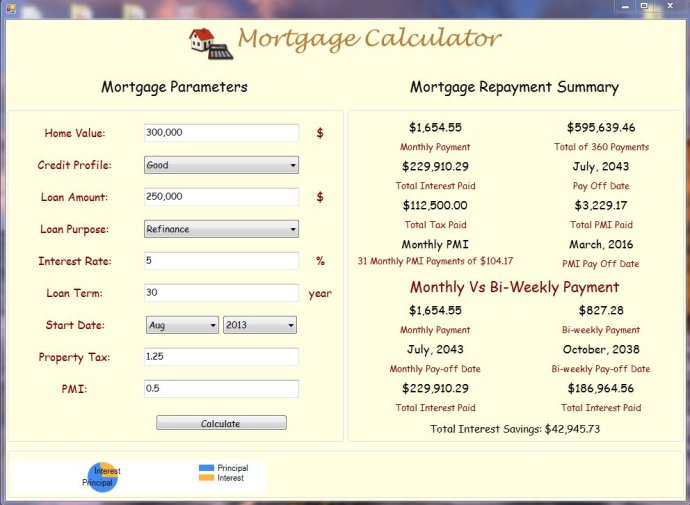
I used to let people walk into my office with a printed payment estimate from some free website, then wonder why their approval came back lower than expected. The problem was never the math itself. It was the assumptions baked into the calculator they used. Mississippi has its own quirks when it comes to property taxes, homestead exemptions, and the way certain counties handle homeowner insurance premiums, so a generic national calculator will mislead you every time. The core calculation is straightforward. You take the loan amount, apply the interest rate, factor in the term length, and then add taxes, insurance, and any HOA fees on top. But the parts people always forget are the ones that change your payment by a couple hundred dollars. Property tax rates in Mississippi vary by county and can range from about 0.5% to over 1.1% of assessed value depending on where you are. Jackson alone sits around 0.85%, but in rural counties like Tishomingo it can dip below 0.6%, while some areas in DeSoto County push closer to 1.0%. That difference matters.
How to Use a Mortgage Calculator Mississippi Properly
Start by finding a calculator that lets you input county-level property tax data rather than assuming a statewide average. Most national calculators default to a single percentage, which works fine for rough budgeting but falls apart when you're actually comparing loans across different counties. I had a client last year who was shopping between a house in Harrison County and one in Rankin County. The calculator showed nearly identical monthly payments, but once we plugged in the actual tax rates, the Rankin property came out $140 a month more expensive than the Harrison one after taxes. He would have picked the wrong house without adjusting for that. Here is what you should do. Enter your target purchase price, your down payment percentage, and the interest rate you have been quoted. Then manually adjust the property tax field using your county's rate, not a national average. Add annual homeowner's insurance divided by twelve, and include any HOA dues. The result should match what a lender would show you on a Loan Estimate within a few dollars. If it is off by more than that, something in your inputs is wrong. I keep a simple spreadsheet alongside any calculator I use. It tracks the debt-to-income ratio impact of each payment scenario, because that number is what actually determines whether you get approved. A calculator might tell you you can afford a $280,000 loan at a certain payment, but if your existing debts push your front-end ratio above 43%, most lenders will still turn you down. The payment the calculator shows is only half the story.
One thing nobody tells you about Mississippi mortgages is the role of state programs. The Mississippi Department of Finance and Administration runs several first-time homebuyer programs that offer down payment assistance and reduced interest rates. These programs have income limits based on county median income, so the cutoff changes depending on where you buy. A Mortgage Calculator Mississippi that does not account for program eligibility will give you a payment number that looks great but may not be attainable if you do not qualify for the assistance that makes the deal work in the first place. I ran into a specific issue recently with a borrower who had a fixed-rate FHA loan and was trying to verify her payment using a standard online tool. The calculator assumed her homeowner's insurance was $120 a month based on a national average, but in coastal Mississippi counties, flood insurance alone can add another $80 to $200 monthly depending on the zone. Her actual payment was $90 higher than what the calculator showed, which pushed her debt-to-income ratio just over the limit for the loan she was pursuing. The workaround was simple: I pulled her actual insurance quote first, entered the real figure into the calculator, and then recalculated her eligibility. It took about five minutes and saved her from going under contract on a house she could not actually afford. Another counter-intuitive thing is that a lower interest rate does not always mean a lower monthly payment in Mississippi. Some lenders offer rate-and-term refinances where they roll closing costs into the loan balance. That increases your principal, which increases your payment, even though your rate dropped. You need to look at the total monthly obligation, not just the interest rate number, when you are comparing offers.
Get the Full Details

If you want something you can actually use instead of a web page that refreshes and loses your data, there are downloadable spreadsheets available from the Mississippi Housing Corporation website. They are not fancy, but they include the county-level tax tables and program income limits built in. I have used them for years and they are more accurate than most commercial calculators for this state. You can find them by searching the MHC website under the resources or buyer education section. There are limits to what any calculator can do. It cannot tell you if a lender is quoting you a rate that includes unnecessary product additives like credit insurance or mandatory service fees that inflate your APR. It cannot predict whether your appraisal will come in at the contract price. And it will not account for the fact that some Mississippi counties require additional inspections or disclosures that can delay closing and affect your rate lock timeline. A calculator is a starting point, not a substitute for a Loan Estimate from a licensed lender in your state.