How Mortgage Calculators Actually Work in New York
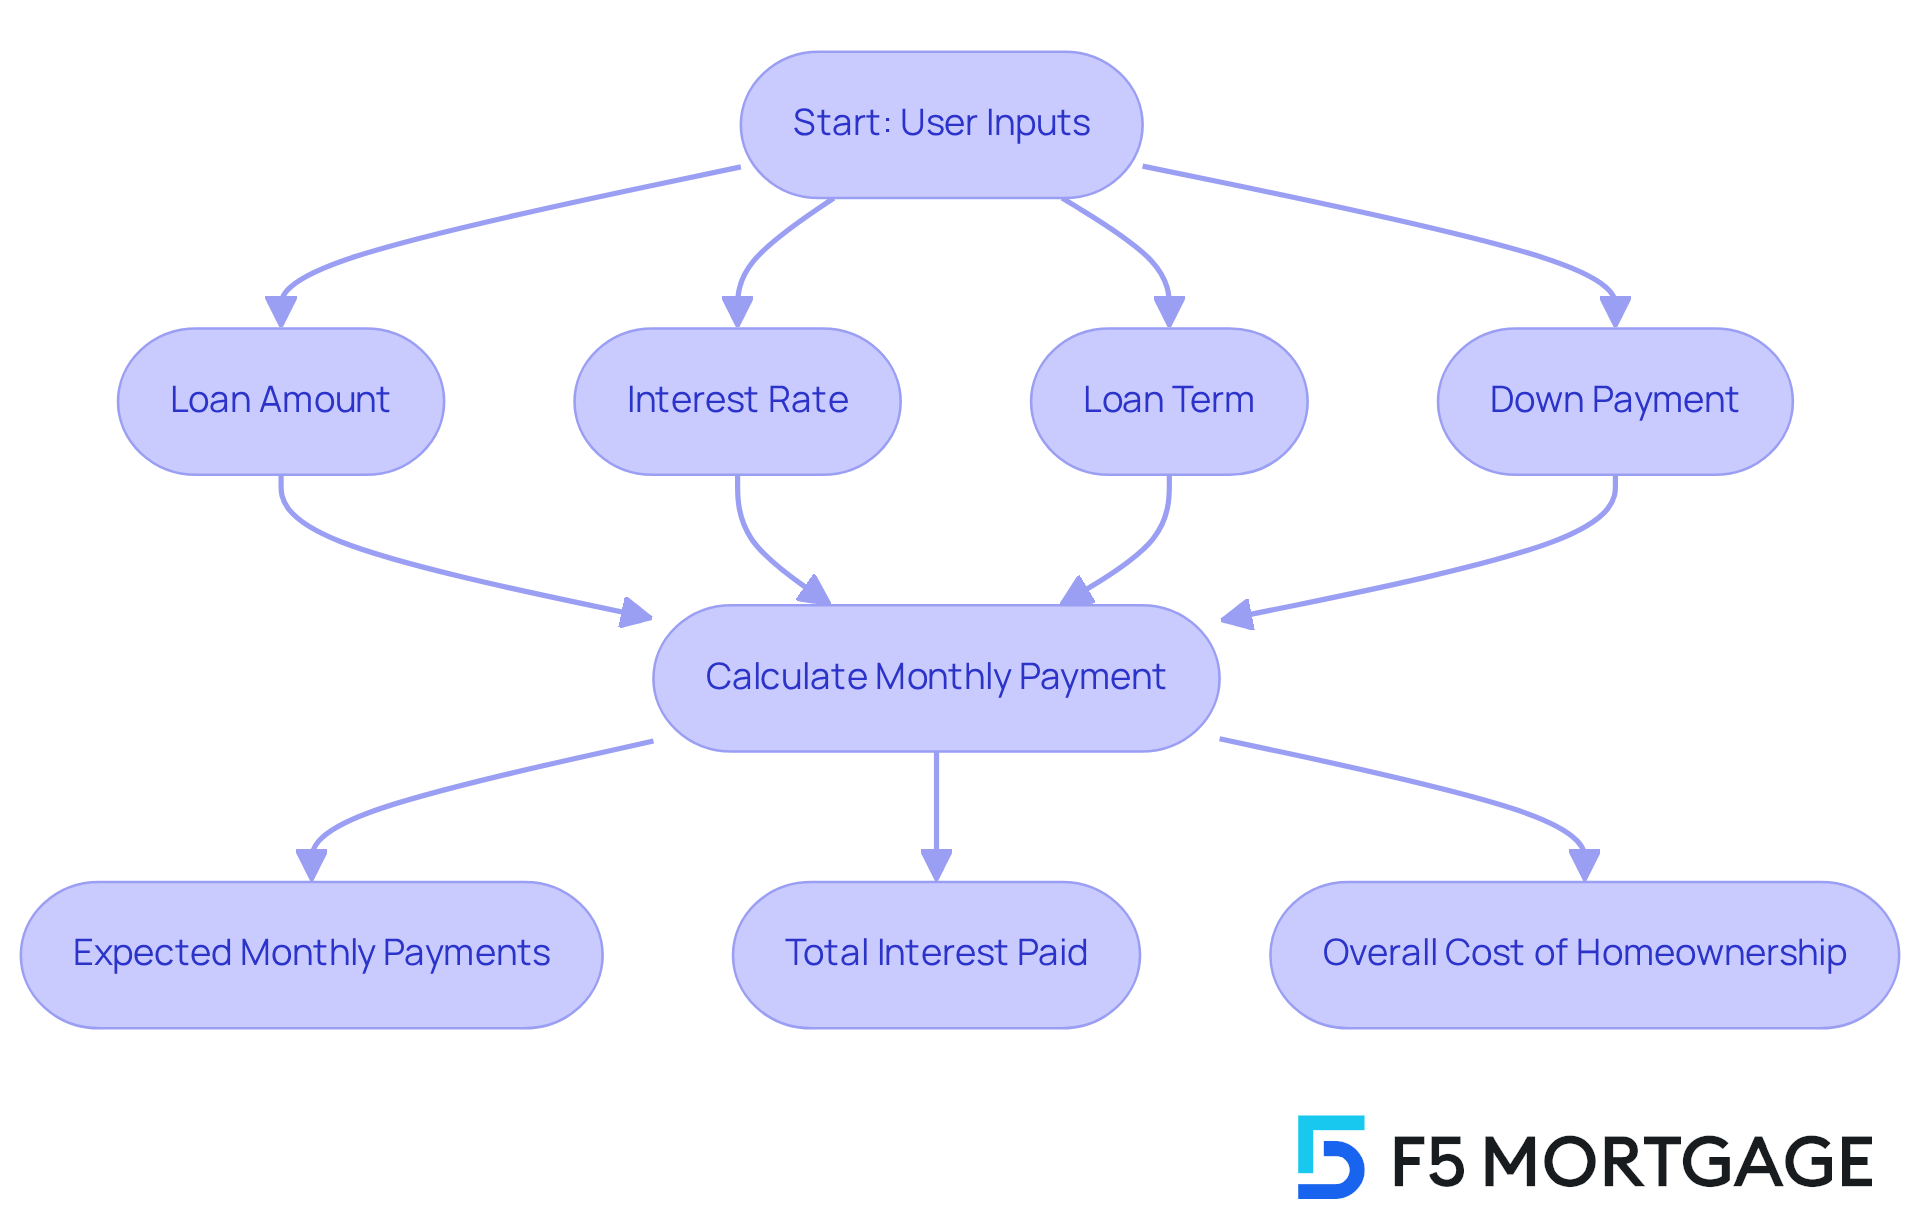
A mortgage calculator is just a tool that takes your loan amount, interest rate, and term and figures out what your monthly payment will be. That part is universal. Where New York gets complicated is everything tacked onto that base payment. Property taxes, mandatory mortgage insurance on jumbo-adjacent loans, HOA fees, and the various tax abatement programs that can make or break whether a purchase makes financial sense. I use a Mortgage Calculator New York for quick estimates, but I also know when those numbers lie to you. The standard online calculators assume a simple 30-year fixed with everything else factored in. They do not account for NY's unique closing cost landscape, the condo co-op split, or the fact that property taxes in some boroughs can add $400 to $900 a month to what the calculator tells you.
What to Actually Plug Into the Calculator
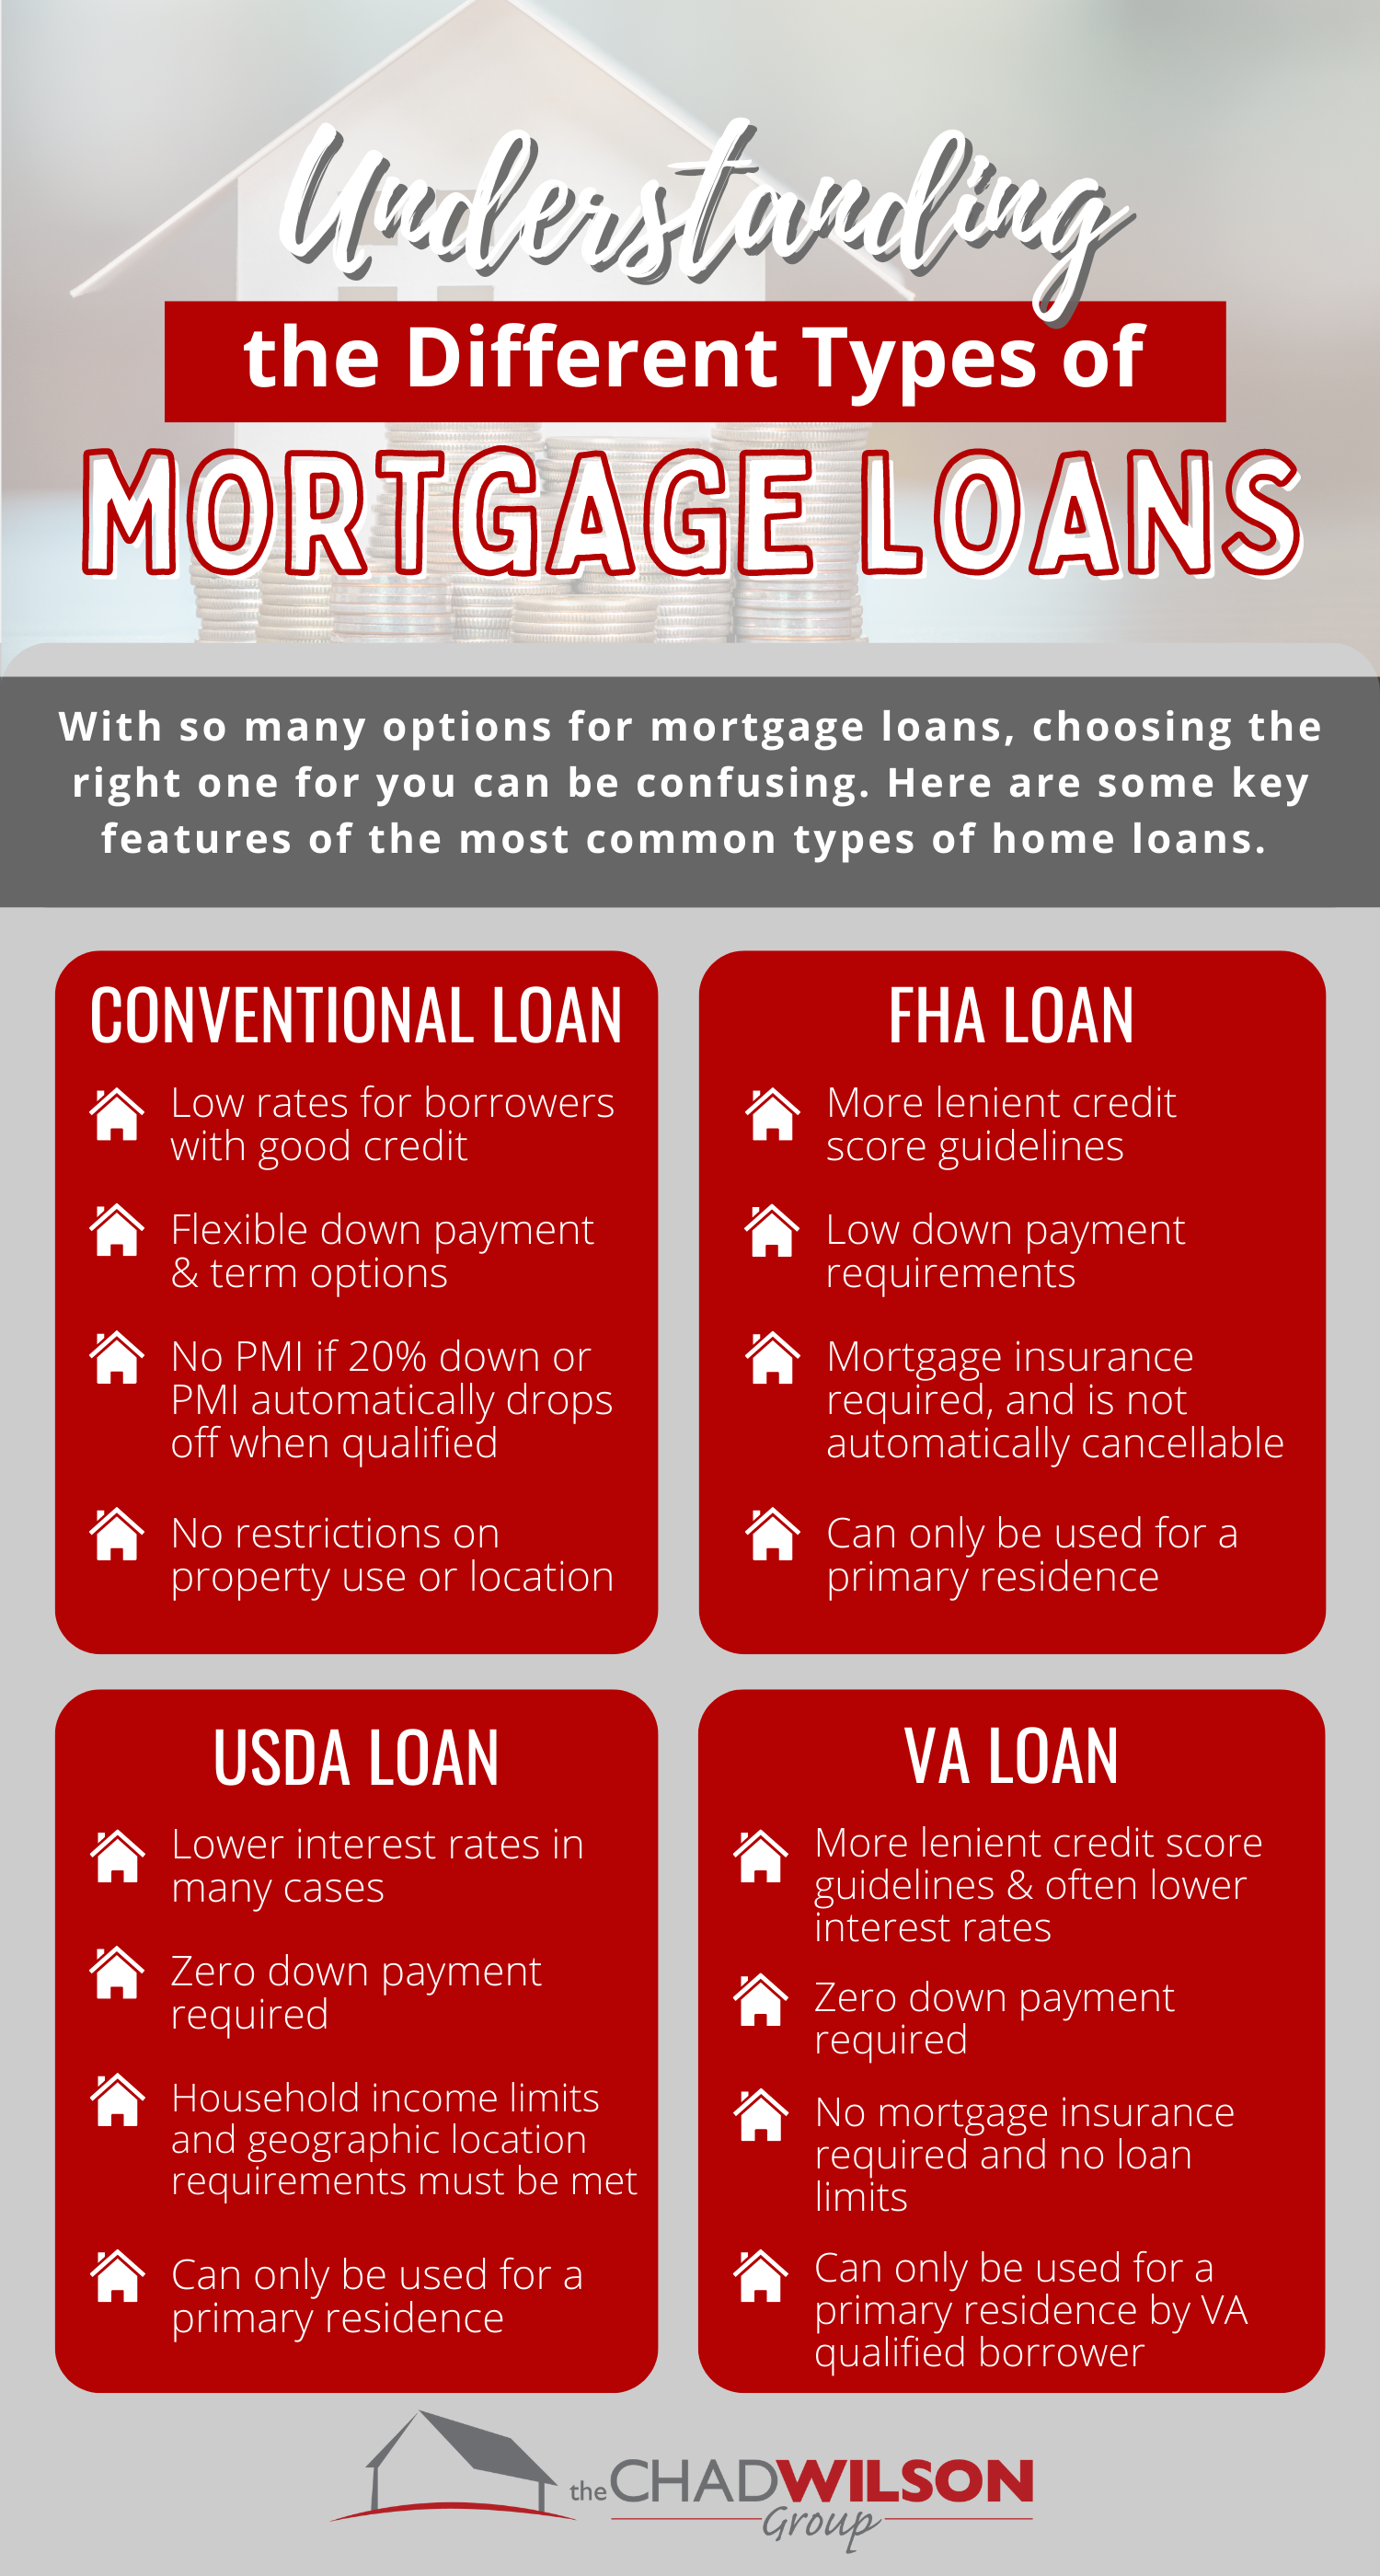
Most people open a mortgage calculator and type in their purchase price and down payment, then hit calculate and call it a day. That gives you a number that is usually $300 to $800 too low for a New York purchase because the calculator does not know your tax district. Here is what you need to handle first: find the annual property tax for the specific address. If you are looking at a co-op, the monthly maintenance fee replaces property taxes and often includes them. If you are looking at a condo, the tax information is in the flip book. For a single-family home in Brooklyn or Queens, expect anywhere from $3,000 to over $12,000 a year in property taxes depending on the neighborhood. That changes your monthly payment dramatically. Next, understand the loan limit environment. New York is a high-cost area. The conforming loan limit for 2024 sits at $766,550 for a single-unit property, which is significantly higher than the baseline limit used by most generic calculators. If you are buying above that threshold, you are in jumbo territory and the interest rates, reserves required, and underwriting standards are completely different. Many calculators will not even acknowledge this distinction and will show you a payment that assumes conforming terms.
A Specific Problem I Hit and How I Fixed It
There was a client looking at a condo in Long Island City with a $1.1 million price tag and a 10 percent down payment. We ran it through a standard mortgage calculator and got a monthly payment that looked manageable. Then I added the actual property tax from the assessment record, which came out to about $14,400 annually, plus the monthly maintenance of $1,800 and a mortgage insurance premium because the loan-to-value ratio was close to the jumbo line. The real monthly obligation was nearly $9,000. The calculator had shown roughly $6,200. That is a $2,800 gap that would have made the purchase impossible once we saw the full picture. The workaround was simple but tedious: I built a spreadsheet that pulled the tax assessment directly from the ACRIS system, added the maintenance fee line item, and applied the correct MI rate based on the actual loan amount versus the jumbo threshold. It took about 20 minutes instead of 5, but it saved us from chasing a bad deal for another two weeks.
Get the Full Details
Counter-Intuitive Things Nobody Tells You
One thing that catches people off guard in New York is that a lower interest rate is not always the better deal when you are comparing loans. If one lender offers a rate of 6.5 percent with $8,000 in closing costs and another offers 6.75 percent with $2,000 in costs, the higher rate might actually be cheaper over the life of the loan depending on how long you plan to stay in the property. The calculator will show the lower rate as better every time unless you factor in closing costs, which most do not do by default. Another thing is the relationship between your down payment and private mortgage insurance. In New York, many lenders require MI until you hit 20 percent equity, but some jumbo loans have different structures. If you put down 25 percent on a $1.2 million condo, you might still face MI at certain lenders because jumbo loans do not always follow the same MI rules as conforming loans. The calculator will not tell you this. You have to ask the lender directly about their MI thresholds.
Where Mortgage Calculators Completely Fail in New York
They do not account for tax abatements. If you are buying a new construction or a newly converted building in Manhattan, Brooklyn, or the Bronx, there may be a 421-a or tax abatement in place that reduces your property tax for 10 to 25 years. The calculator will show you the full tax amount and make the payment look much higher than it will actually be during the abatement period. This is not a minor difference. It can be a $400 to $700 per month gap that disappears once the abatement expires. They also do not handle co-op financing well. Co-ops in New York operate differently from condos. You are not getting a traditional mortgage in the same sense. The board has approval processes, flipping fees, and often stricter financial requirements. A calculator will give you a number, but the real constraint is whether the co-op board will accept the loan structure and your financial profile. The monthly payment might be fine on paper and the deal still dies in board review. If you want accuracy beyond the rough estimate, the best approach is to run the calculator first to get a ballpark, then take that number to a local broker or lender who understands the New York market. They can pull the actual tax assessment, confirm the MI requirements for your specific loan type, and factor in any abatements or programs. The calculator is useful for filtering listings quickly, but it is not a replacement for local expertise when the numbers are this tight.