Why North Dakota Mortgage Math Looks Different Than Everywhere Else
Most people grab a generic online mortgage calculator and plug in their numbers, then get confused when the result feels wrong. North Dakota has property tax rates that vary wildly between counties — Burleigh County sits around 1.08% while some rural counties drop below 0.60%. That single difference can swing your monthly escrow payment by hundreds of dollars. A mortgage calculator North Dakota calculator that doesn't let you adjust for county-level tax rates is essentially guessing. I've been running these calculations for clients for over a decade. The thing that catches people off guard most often isn't the interest rate — it's the way North Dakota handles property assessment cycles. The state reassesses property values every two years, and the new assessment doesn't always land until the following spring. So if you bought a home in 2023, your 2024 tax bill might still reflect the 2022 assessed value. Lenders use the most recent payable tax amount to calculate your escrow, which means your payment can jump unexpectedly when the new assessment hits.
How to Actually Use a Mortgage Calculator North Dakota Tool Correctly
Start by confirming your county. That's the first variable that matters more than anything else. North Dakota has 53 counties and the property tax burden ranges from roughly 0.55% in Ward County up to over 1.40% in some of the more heavily populated areas. Once you know your county, pull your actual tax bill from the county treasurer's website rather than guessing. I had a client in Grand Forks recently who was using a default tax estimate from a national calculator site. Her actual rate was nearly double what the tool assumed, and her estimated monthly payment was off by about $140. She found out right before closing when the lender's opening disclosure showed the real number. Next, look at whether your loan requires private mortgage insurance. If you're putting down less than 20%, most lenders will tack on PMI. In North Dakota, some credit unions and regional banks offer lender-paid mortgage insurance options that roll the cost into your rate instead. A proper calculator will let you model both scenarios. The national average PMI rate hovers around 0.5% to 1.0% of the loan amount annually, but it varies by loan type and credit score. FHA loans in the state carry MIP that runs for the life of the loan if you put less than 10% down, which changes the math significantly compared to a conventional loan. You also need to factor in homeowners insurance. North Dakota weather throws some unusual problems at homeowners here — hail damage is a chronic issue in the eastern part of the state, and wind coverage can add to premiums. Insurance costs in Fargo and Bismarck run higher than in smaller towns, but rural properties can cost more to insure due to distance from fire stations. Get actual quotes before you rely on a calculator's estimate. The tool might project $80 a month while your real premium runs $130 once the insurer accounts for hail risk in your ZIP code.
The Numbers That Actually Move Your Payment
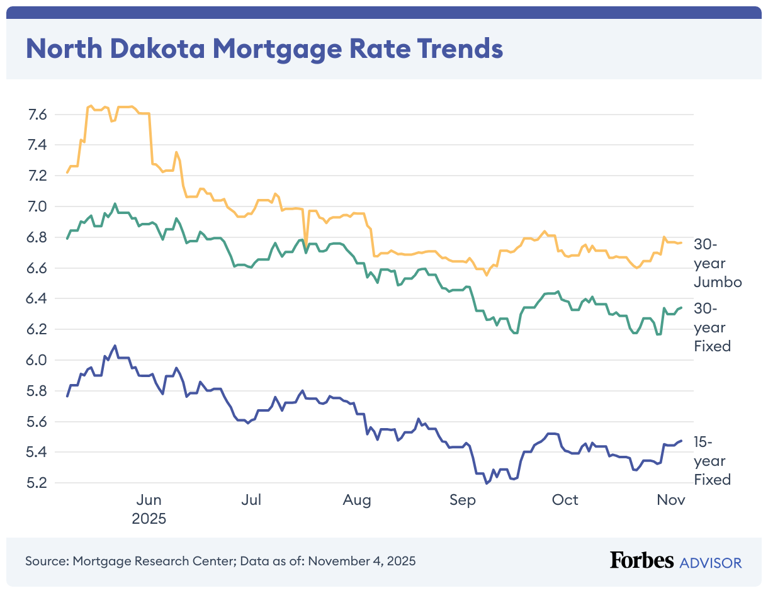
Interest rate changes produce the biggest impact, obviously, but the direction matters more than people realize. A drop from 7.0% to 6.5% on a $300,000 loan over 30 years saves roughly $157 per month. Going the other direction from 6.5% to 7.0% adds the same amount. The relationship isn't linear, so small rate shifts near the current market don't feel dramatic but they compound over the loan term. On a 30-year fixed, that $157 difference equals about $56,500 in total interest paid over the life of the loan. Down payment size interacts with PMI in a way that trip up a lot of first-time buyers. Putting 15% down instead of 10% might seem like a minor difference, but it can eliminate PMI entirely on conventional loans. On a $350,000 purchase, the 10% down scenario creates a $315,000 loan with PMI costing maybe $130 monthly, while the 15% down leaves a $297,500 loan with no PMI. You're borrowing less money and skipping the insurance fee, which together shift your payment by roughly $250 a month compared to the smaller down payment. Loan term length is another area where calculators sometimes mislead. People see the lower monthly payment on a 30-year versus a 15-year and assume it's the better deal. On a $320,000 loan at 6.75%, the 30-year comes to about $2,075 monthly while the 15-year lands near $2,830. The 15-year costs $755 more per month but saves roughly $118,000 in interest. If you qualify for the higher payment, it's usually worth it. But the calculator won't tell you whether you qualify — that depends on your debt-to-income ratio and the lender's underwriting standards.
Get the Full Details

Where These Calculators Fall Short
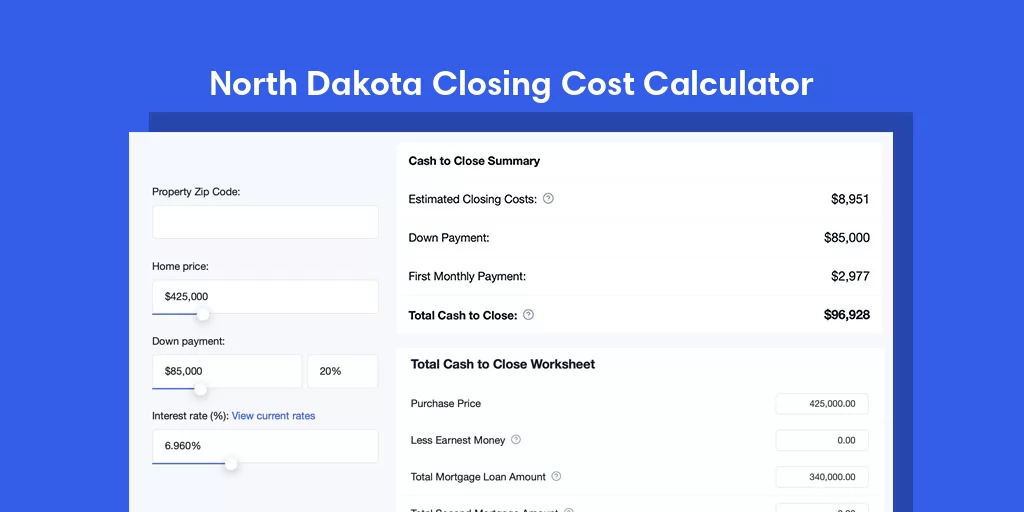
Online mortgage calculators have blind spots. They don't know your credit score, your existing debt obligations, or whether your employer has a retention bonus that counts as income. They can't access your actual property tax record for your specific parcel. And they typically don't account for North Dakota's homestead exemption, which can reduce the taxable value of your primary residence by a portion of its market value depending on the county. I ran into a specific edge case last year involving an refinancing client in Cass County. His mortgage calculator North Dakota estimate showed a refi would save him $90 a month. The problem was the calculator used the original loan balance and didn't account for the payoff of his home equity line of credit, which sat at $28,000. Once we factored the HELOC into the new loan amount, the payment actually increased by $45 a month instead of decreasing. The refi still made sense because he was consolidating two debts into one with a lower combined rate, but the calculator had given him the wrong impression about the monthly impact. Always double-check what assumptions the tool is making. Another limitation: these calculators rarely include closing costs in their output. In North Dakota, closing costs typically range from 2% to 5% of the loan amount. On a $280,000 purchase, that's $5,600 to $14,000 you need to bring to the table or roll into the loan. Rolling it in increases your principal and your interest charges, which shifts the monthly payment slightly higher than the calculator shows. If you pay closing costs upfront, your payment looks exactly like the estimate, but your cash reserves take a bigger hit at signing.
Practical Steps Before You Trust the Number
Get a loan estimate from at least two lenders before relying on any calculator output. The Loan Estimate form is a standardized document that shows your actual rates, fees, and monthly payment breakdown including taxes and insurance. It takes about 10 minutes to request and gives you real numbers instead of estimates. I usually tell people to run the calculator first for a general sense of affordability, then get the Loan Estimate within 48 hours. The difference between the two tells you how much the tool got wrong and which variables matter most for your situation. Check your county's tax assessor website directly. North Dakota provides online property search tools for every county. Enter your address or parcel number and pull the current assessed value and tax rate. Plug those exact figures into the calculator rather than using state averages. The variation between counties is large enough that using a statewide average introduces meaningful error into your monthly payment estimate. If you're buying in a newly developed subdivision, ask the builder or developer about any pending special assessments or municipal improvement districts. Some areas outside Fargo and Minot have sewer or water district fees that get added to your property tax bill. These aren't reflected in standard calculators and can add $20 to $80 a month to your payment without warning. I've seen this happen twice in the last three years in subdivisions near Mandan where the initial tax bills didn't include the new district assessments because the districts hadn't been formally established yet.
The bottom line is that a mortgage calculator gives you a starting point, not a final answer. North Dakota's county-level variations in property taxes, insurance costs, and assessment timing mean that the real number will differ from whatever the tool shows. Run the calculator, then verify with actual documents and a Loan Estimate before you make any decisions based on the output.