How to actually use a mortgage calculator without getting the numbers wrong
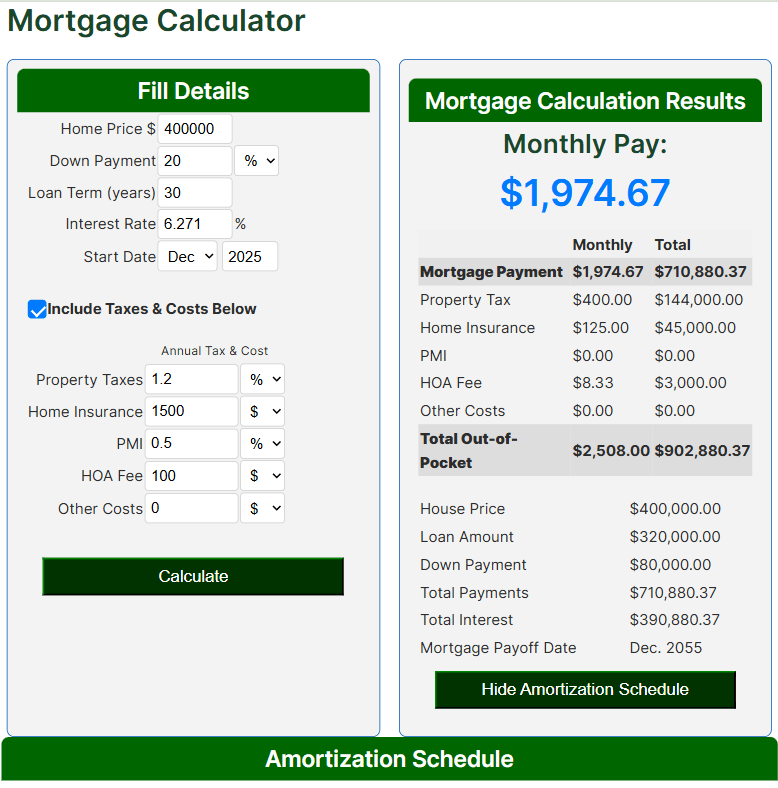
The spreadsheet most people use for this isn't very good. I've seen it dozens of times, usually at closing tables where someone just typed monthly payments into a Google Sheet like it was a final answer. It's not. A Mortgage Calculator San Antonio is a starting point, not a decision tool. The difference matters when your actual payment ends up twenty percent higher than what you budgeted around. The math itself is standard amortization. Monthly payment equals the loan amount multiplied by the monthly interest rate, divided by one minus one plus the monthly interest rate raised to the negative of total number of payments. In Excel that's PMT(rate, nper, pv). Simple enough. The problem is what people leave out. Most free calculators online return the principal and interest number and stop there. They don't fold in property taxes, homeowners insurance, HOA dues, or PMI. In Bexar County the average property tax rate runs around 2.1 to 2.4 percent annually. On a $350,000 home that's roughly $750 to $875 a month sitting on top of your PITI before you even think about insurance. If your calculator didn't include those line items, the number you're looking at is misleading by design.
I worked a file last year where the borrower was absolutely certain their payment would come in under $2,100. Their calculator showed $1,847. The actual HUD-1 had them at $2,384 because nobody had asked the calculator to include tax escrow properly. The tool was right for what it was doing. It was just doing too little.
What you should actually be putting in
How to run a Mortgage Calculator San Antonio correctly
Start with your purchase price or refinance amount. Subtract your down payment to get the base loan. Enter the interest rate as a decimal annual figure. Set the term, usually 30 or 15 years. Then add the extra fields if the calculator has them. If it doesn't have extra fields, you're going to need a separate sheet for taxes and insurance anyway, so just do it now instead of later. Property taxes in San Antonio vary by zone. The Alamo Heights district and some of the north side areas push rates higher than the South Side or eastern Bexar County. You can look up your exact rate on the Bexar Appraisal District website and plug it in. Homeowners insurance in this market runs somewhere between $1,200 and $2,400 annually depending on the age of the home, construction type, and coverage level. Split that monthly and add it to your payment.Get the Full Details
PMI drops off once you hit 20 percent equity, but lenders still require it until then on conventional loans. FHA loans tack on MIP for the life of the loan if you put less than ten percent down, which is a detail a lot of people miss until they're paying it for ten years. VA loans have a funding fee instead, which you either pay upfront or roll into the loan balance. The calculator won't always make these distinctions clearly, so know which program you're targeting before you trust the output.
Something most guides won't tell you about rates and points
Buying points changes your monthly payment but also your effective APR, and those two numbers move in opposite directions. A calculator that only shows you the payment and doesn't also calculate the true cost of borrowing can give you the wrong impression about whether an option is actually cheaper. Two points on a $300,000 loan costs $6,000 upfront but might drop your payment by $85 a month. That's a break-even around seven years. If you plan to sell before then, you've thrown the money away. The calculator won't tell you that. You have to do the math yourself. Another thing nobody talks about enough is rate lock duration and floaters. Locking at 6.75 percent is fine until the market moves and you realize you could have gotten 6.50 percent three weeks later. Some lenders will let you float your rate down during the lock period instead of committing flat. It's a strategy, not a calculator input, but it changes your effective cost enough to matter. I tell people who are on the edge of closing to ask their loan officer about a float-down option before they sign the lock paperwork. It costs a little extra in points sometimes, but it can save you hundreds over the life of the loan if rates dip during processing.
Where these calculators completely fail
They don't account for closing costs, which in San Antonio typically run between two and five percent of the loan amount depending on the lender, title company, and whether you're buying or refinancing. You can't really budget for a home purchase if you only look at the monthly payment. A $320,000 loan might have $8,000 to $16,000 in closing costs that need to come from your cash to close, and that's a whole different number than what the payment calculator shows you. They also don't handle ARM adjustments well. A 5/1 ARM might look great on paper with a 5.5 percent initial rate, but the calculator won't show you what happens after year five when the rate adjusts to whatever the index says plus your margin. You need to know the cap structure, the index being used, and what the fully indexed rate would look like under current conditions. Run that through a second calculator if yours doesn't support ARMs natively, or just look at the actual loan estimate the lender gives you, which will show the projected adjustments across the full amortization schedule. For people who want something more robust than a web form, I recommend using a dedicated mortgage calculator that lets you import or manually enter all the cost lines. Or better yet, just pull a Loan Estimate from three different lenders and compare them side by side. That's the document the government requires them to give you, and it includes the actual closing costs, the APR, and the total interest charge over the life of the loan. No calculator on the internet matches that level of accuracy until you're past the pre-approval stage.
The bottom line is that a mortgage calculator in San Antonio, or anywhere else, is useful for quick back-of-the-envelope work. It is not a substitute for reading the actual numbers on your loan estimate, checking your local tax rates, and understanding how points, PMI, and closing costs affect your real cost of borrowing. Most people skip those steps because the payment number looks good on the screen. It usually isn't the full story.