Working Through a South Carolina Mortgage Calculation
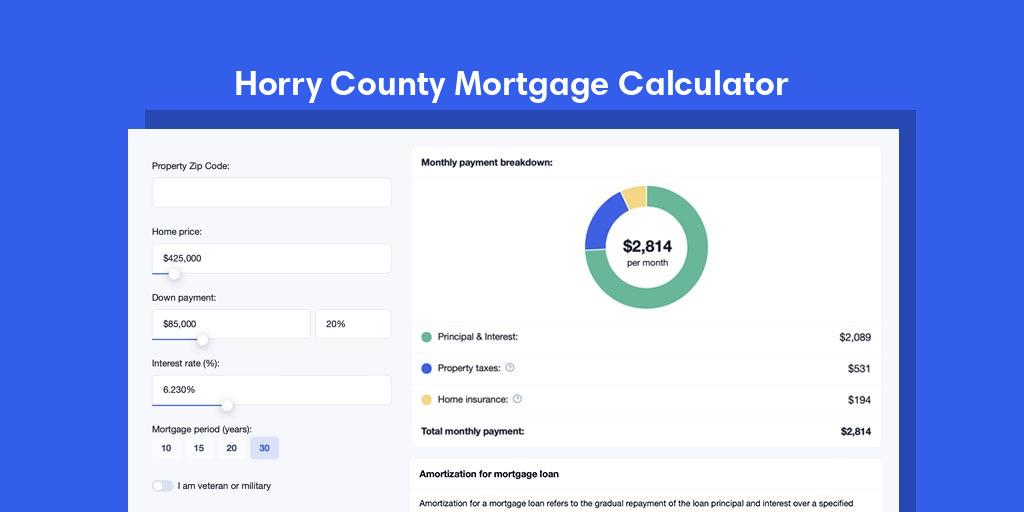
Mortgage math doesn't change much by state, but South Carolina has a few particulars that matter when you're trying to get an accurate number. Property taxes run about 0.57% of assessed value on average statewide, though Beaufort and Charleston counties push higher. Flood insurance is real in low-lying areas near the coast. These aren't details you want to skip because they materially shift your monthly payment. I've filled out dozens of these over the years and the process is straightforward if you don't rush it. First, gather your loan amount, interest rate, and loan term. Then input your down payment — which matters more in South Carolina than most people realize since the state has specific first-time buyer programs tied to income limits and purchase price caps. I worked with a client last year who thought she qualified for a standard FHA deal, but her income was $800 over the SC Housing Finance Authority limit for Beaufort County. She ended up qualifying through a different program entirely. The calculator still gave her a payment estimate, but it was based on the wrong assistance program. Factor that in before you trust the output. Here's the part most online calculators miss: South Carolina assesses property at roughly 4% to 20% of market value depending on the county, not the full sale price. That's why your property tax line item might look surprisingly low in a generic calculator but jumps when you see your actual bill. You need to know the assessment ratio for your specific county. Charleston County sits around 5%, Dorchester is closer to 10%. Call the county assessor's office if you can't find it online.
For the actual calculation itself, you're looking at P&I first. That principal and interest figure uses the standard amortization formula. Take your monthly interest rate — annual rate divided by 12 — multiply it by one plus that rate raised to the negative number of total payments, then divide the loan amount by that result. It sounds heavy but any basic financial calculator or Excel spreadsheet will do it instantly. From there add property tax, homeowners insurance, and if applicable HOA dues or mortgage insurance. PMI drops off once you hit 20% equity, but in South Carolina many lenders still require it with less down, especially on jumbo loans or investment properties. One thing I always tell people: don't stop at the monthly payment number. Look at the total interest over the life of the loan and compare it across rate points. A 0.5 point buydown on a $250,000 loan costs about $1,250 upfront but saves roughly $40 per month on a 30-year fixed at current rates. That's a break-even in about 31 months. If you're planning to sell before then, the buydown is wasted money. I've seen buyers pay points they didn't need because the calculator made the lower payment look nicer on paper. Another practical concern is ARM products. South Carolina has a fair number of adjustable-rate mortgages, particularly among younger buyers and investors. The initial rate teaser period often looks great in a calculator, but those resets are where people get blindsided. Make sure you're calculating the fully indexed rate, not just the start rate. The difference between 6.5% and 7.8% on a $275,000 loan is roughly $180 per month after the adjustment. That changes whether you can actually afford the house or not.
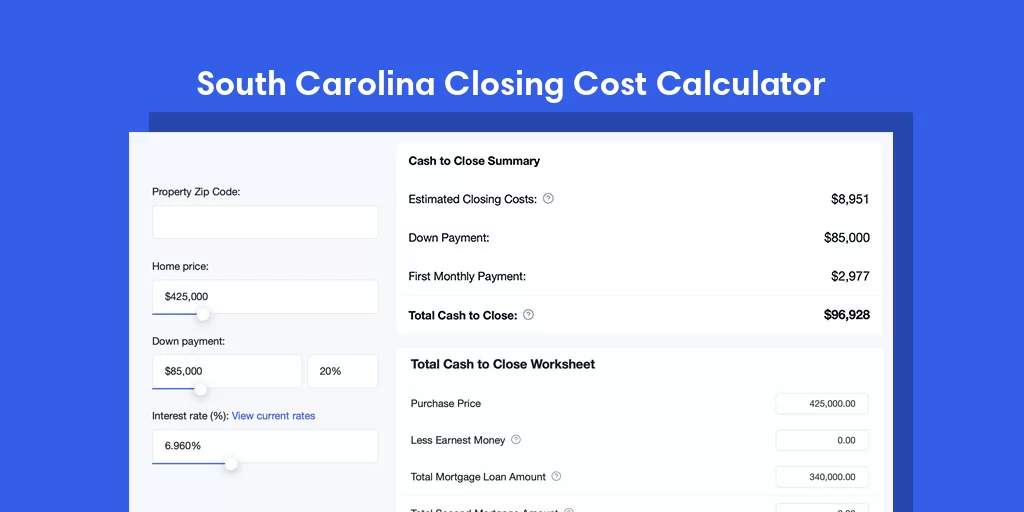
If you want to run this yourself, you can use a basic Excel sheet. Set up columns for loan amount, annual rate, term in months, property tax rate, home insurance annual cost, and PMI if applicable. The PMT function in Excel handles the P&I in one cell: =PMT(rate/12, nper, -loan_amount). From there just sum the pieces. I've been doing this on spreadsheets for over a decade and I still prefer it to clicking through some of the flashier online calculators that make assumptions about your county or insurance costs without asking. The main limitation with any mortgage calculator is that it doesn't capture closing costs, which in South Carolina typically run 2.5% to 4% of the loan amount depending on the county and lender. Title insurance, recording fees, transfer taxes — these all vary by location within the state. A calculator won't tell you that Berkeley County has different transfer tax requirements than York County, for example. You'll need a good lender or attorney to get those numbers right. Property tax recalculation every few years in South Carolina is another blind spot. Reassessment happens at the county level and can significantly shift your payment mid-term. I had a borrower in Greenville whose assessed value jumped 22% between two revaluation cycles and his escrow payment went up $95 a month. The original calculator estimate was no longer relevant. Nothing wrong with the tool — just something to keep in mind as a living document rather than a permanent answer.
Get the Full Details

One workaround for getting more accurate numbers is to run your calculator estimates alongside a lender's Loan Estimate. The LE form breaks everything out line by line and you can spot where your assumptions diverged from reality. I usually do this after I've done my own preliminary math so I know what to question when the numbers come in. Takes about ten minutes and saves a lot of follow-up.