Building a Mortgage Calculator That Actually Handles Extra Payments
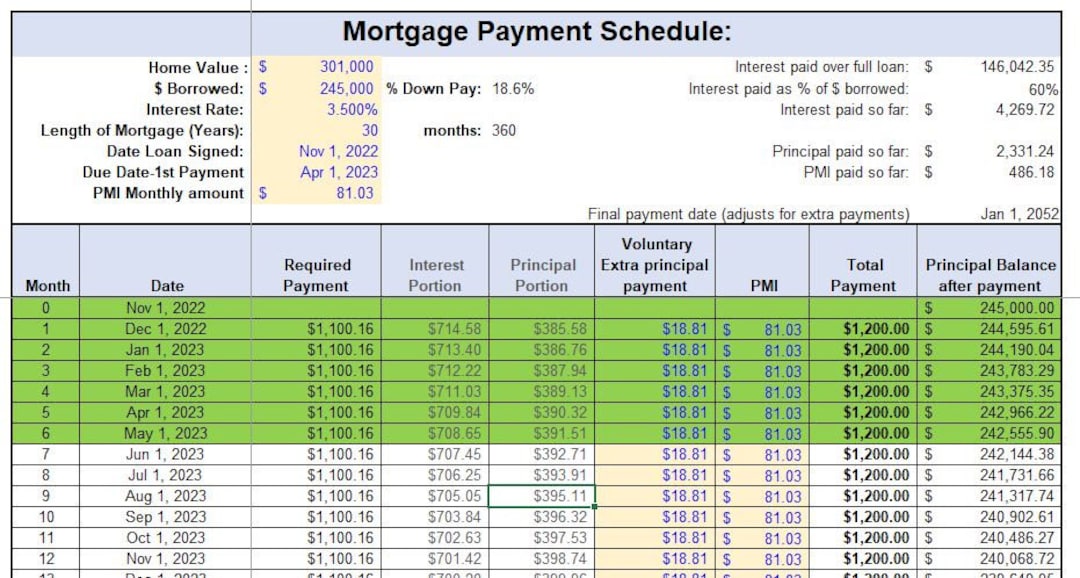
Most mortgage calculators you find online or download as spreadsheets handle the basic amortization just fine, but the moment you try to model extra payments, things get messy. I built several of these over the years for clients and ended up learning where the pain points actually are. Here's how to do it properly. The core issue is that standard amortization schedules assume a fixed payment every month. When you add extra payments, you have to decide whether that extra money goes toward principal or whether it simply shortens the term. In practice, almost everyone means principal, which means you need the spreadsheet to recalculate the remaining balance and then reamortize from that new balance going forward. This isn't just a one-time subtraction. Every month after an extra payment, the interest portion drops and more of the regular payment goes toward principal, which compounds over time. Here's the formula structure that actually works. Start with the standard amortization variables: the loan amount, the annual interest rate, and the number of payments. Convert the annual rate to a monthly rate by dividing by 12, and convert the term to months by multiplying the years by 12. Then use the PMT function to get the base monthly payment. After that, for each row in your schedule, calculate the interest portion as the remaining balance times the monthly rate. Subtract that interest from the total payment to get the principal portion. Add any extra payment you designated for that month to the principal portion. Subtract the new total principal payment from the balance. Repeat for every month.
The trap most people fall into is using a fixed reference to the original loan balance instead of the rolling remaining balance. I've seen spreadsheets where someone adds a $10,000 extra payment but the next month's interest calculation still uses the old balance. That produces a schedule that looks correct at first glance but is wrong by month two and compounds the error further downstream. Always make sure the ending balance of one row feeds directly into the beginning balance of the next row through a cell reference, not a hardcoded number. Another thing that trips people up is the timing of extra payments. Are they made at the beginning of the month or the end? This matters because interest accrues daily on most mortgages. If someone makes a mid-month extra payment, the interest for that month should be calculated on the higher balance before the extra payment hits. The proper approach is to compute interest first, then apply the extra payment to principal after interest is accounted for. Some lenders handle this automatically, but your spreadsheet needs to reflect it explicitly if you want accuracy. I had a client once who was comparing two scenarios: one where she paid an extra $500 per month consistently, and another where she made a single $6,000 payment every January. Her initial spreadsheet showed the consistent extra payment saved more over the life of the loan, which felt wrong intuitively because the lump sum was the same total amount. The issue was that her model was calculating interest on the average balance rather than the actual daily balance. Once I switched it to a month-by-month rolling balance calculation, the lump sum strategy actually came out ahead by about $400 in total interest over 30 years. The difference wasn't huge, but it was meaningful and showed why granular modeling matters.
When you're building this, you also need to account for tax implications if this is for a client who cares about deductibility. Extra principal payments reduce the interest you pay, which reduces your itemized deduction. That's a secondary effect most basic calculators ignore entirely. If your audience includes people who itemize, add a column that shows the annual interest deduction and flag how much it changes year over year with extra payments. It's a small addition that separates a useful tool from a toy. There's also the issue of what happens when an extra payment pushes the remaining term below one year. Your spreadsheet should handle the final partial payment gracefully instead of breaking or showing a negative balance. I usually add a check at the end of the schedule that says if the remaining balance is less than the normal payment, just pay the balance plus the accrued interest for that period and stop. This prevents the weird circular reference errors that come up when the final row tries to subtract more than what's owed. For the actual spreadsheet layout, keep it simple. Columns for payment number, beginning balance, regular payment, extra payment, total principal paid, interest paid, and ending balance. That's all you need. Anything more and you're just adding complexity without adding accuracy. Put the input section at the top with clearly labeled cells for loan amount, interest rate, loan term, and optional extra payment amounts. Then build the schedule below starting from row 8 or so. Use conditional formatting to highlight rows where extra payments were made. It makes it easier to scan.
Get the Full Details

If you want a download link, I don't host files myself, but the structure I described above is straightforward enough that anyone familiar with Excel or Google Sheets can replicate it in about 15 minutes. Search for mortgage amortization template and then modify the standard version to include an extra payment column and adjust the balance rollforward. The modification takes about five minutes once you understand how the references work. The biggest limitation of any spreadsheet-based mortgage calculator with extra payments is that it assumes the interest rate stays fixed. If you have an adjustable-rate mortgage, this approach breaks down because the rate changes at set intervals and the payment recalculates accordingly. For ARMs, you'd need a more complex model that pulls in rate adjustment schedules and rebalances the payment at each reset point. Most people building a quick spreadsheet don't bother with this, but if you're giving advice to someone with an ARM, you should be honest about that gap. Another scenario where spreadsheets fall flat is when prepayment penalties apply. Some loans charge a fee if you pay down principal above a certain threshold in a given year. Without embedding the penalty rules directly into the model, the calculator will overstate your savings. I've encountered this with commercial loans and a few consumer products, and the workaround is to add a penalty calculation column that triggers based on the cumulative extra payments in each calendar year. It's a bit more work but it's the only way to make the output reliable.
Overall, a mortgage calculator spreadsheet with extra payment support is a practical tool if you build it correctly. The key details are the rolling balance, the interest-first-then-extra-payment order, and the final partial payment handling. Get those right and you have something genuinely useful. Get them wrong and you're just producing numbers that look plausible but aren't.