How UK Mortgage Calculators Actually Work
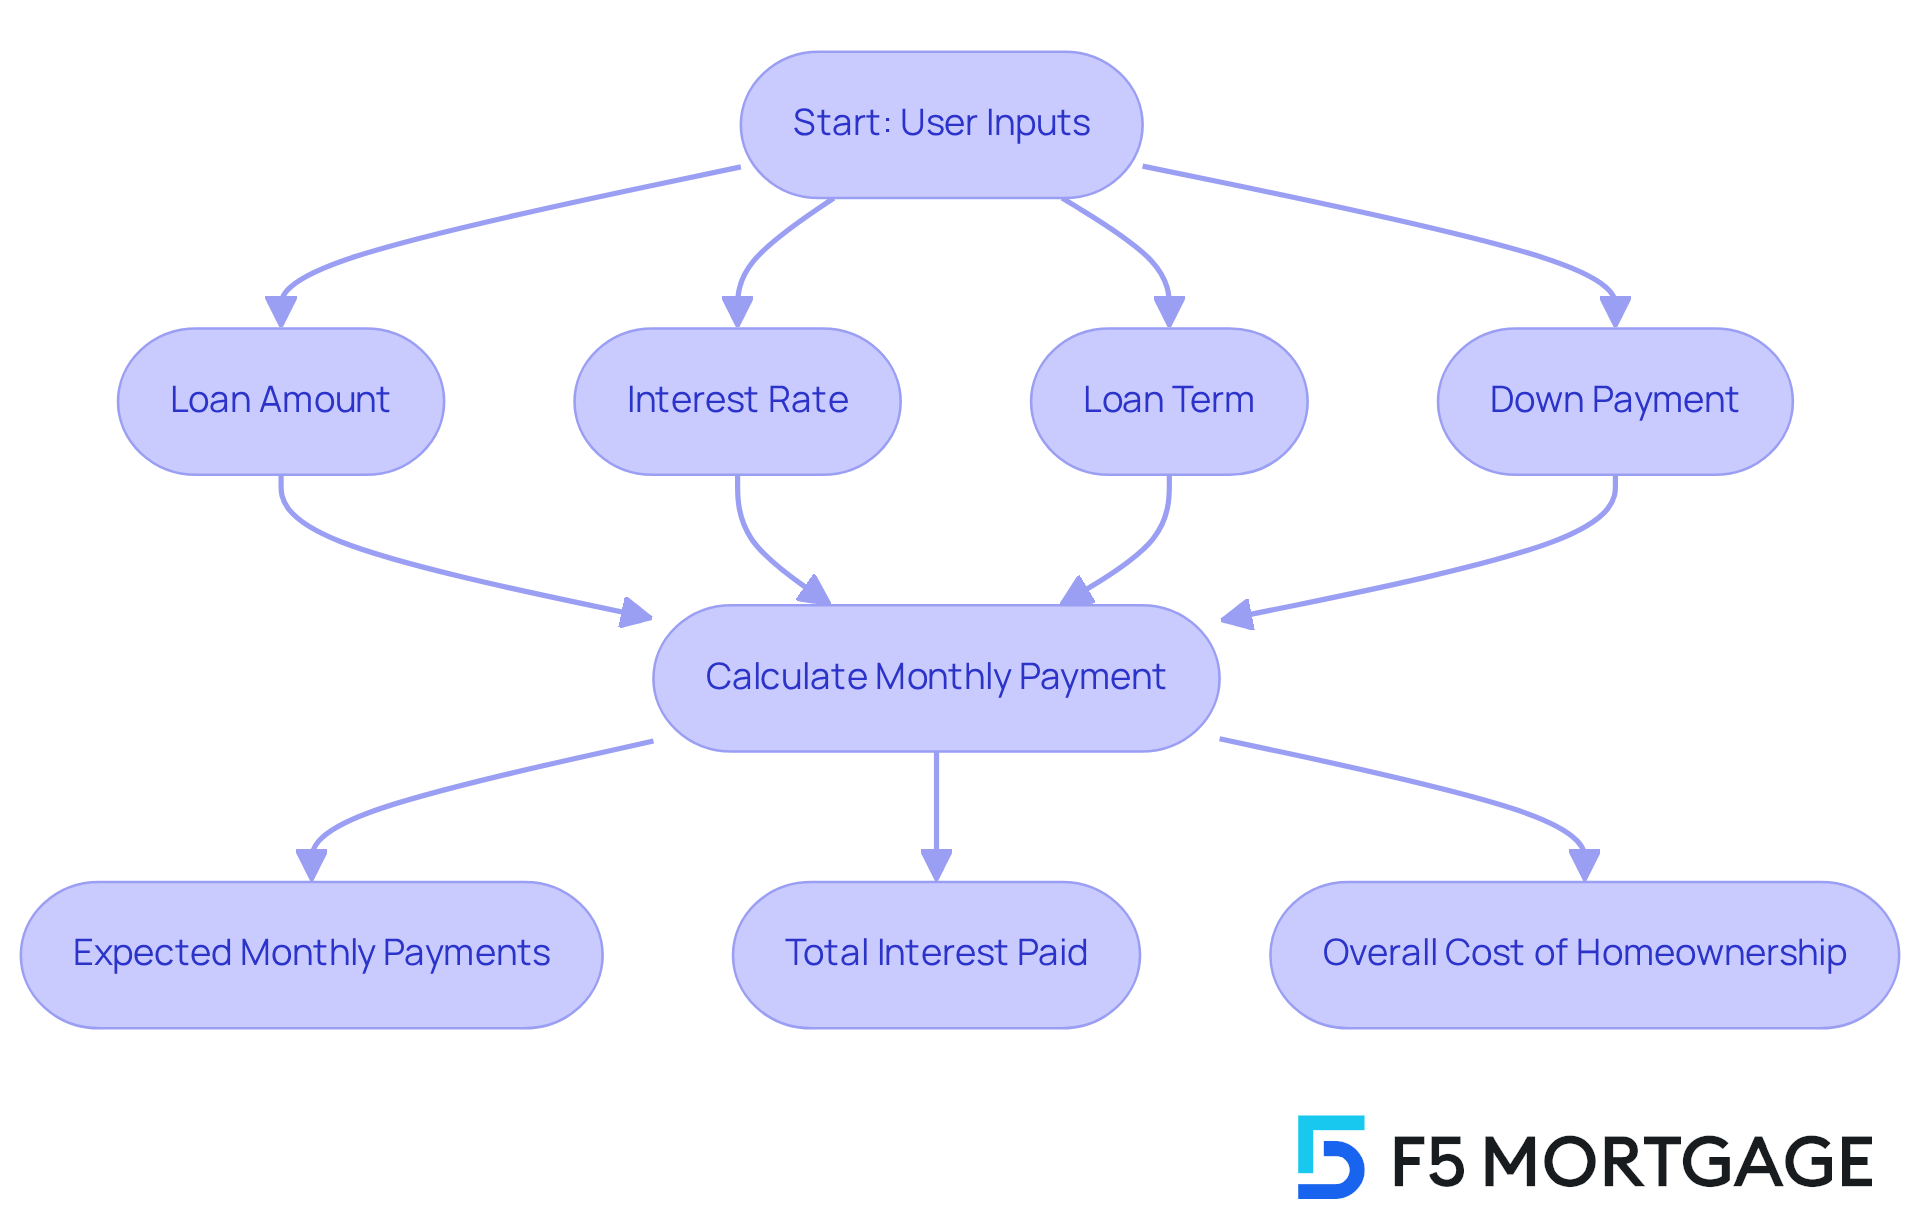
Most people treat online mortgage calculators like magic boxes that spit out a final answer. They don't. These tools give you an estimate, usually within about 5 to 10 percent of what a broker or lender would offer, assuming you feed them decent numbers. The problem is most people feed them the wrong numbers because they don't know what matters in the UK system. The core formula is straightforward. You put in the property price, your deposit percentage, the interest rate, and the term length. The calculator outputs a monthly repayment figure. Simple enough until you factor in the bits most people skip.Mortgage Calculator United Kingdom
Here is what actually happens when I use one of these tools myself. I typically run through the basic inputs first, then go back and adjust for the things that change the number more than people expect. The biggest variable isn't the interest rate. It's whether you are looking at repayment or interest-only, and then it's the fees attached to the deal. Arrangement fees, valuation fees, solicitor costs, these all get rolled into the total cost but rarely into the monthly payment shown on the calculator. I've seen people miss £2,000 in upfront costs and then wonder why their affordability check came back short. The calculator won't tell you that unless you manually add it to the loan amount.What most calculators leave out
Product types in the UK are messier than people realise. A standard 25-year repayment mortgage with a fixed rate for two years looks clean on the surface, but after the fixed period ends you are automatically switched to the lender's standard variable rate, which in 2025 and 2026 has been sitting around 5.5 to 6.5 percent for most high street lenders. The calculator will show you one monthly figure, but that figure changes significantly after year two unless you remortgage. I dealt with a client last year who used a calculator and saw £890 per month. That was correct for the first two years. After the fix ended, the payment jumped to roughly £1,120. She hadn't budgeted for that. She thought the monthly figure was locked in for the life of the mortgage. It isn't. Another thing calculators don't handle well is shared ownership mortgages, which are common in London and parts of the South East. You are buying a share of the property and paying rent on the rest. Standard calculators treat this like a normal purchase and the output is completely wrong. You need a separate tool or you need to work out the mortgage portion and the rent portion separately and then add them together manually.
The underwriting gap
Here is the counter-intuitive part. A lower mortgage amount doesn't always mean a better monthly payment relative to your income. Lenders in the UK assess affordability using stressed rates, not the actual rate you are getting. Most lenders apply a stress test of around 6.5 percent or 3 percent above the product rate, whichever is higher. This means a 4.5 percent fixed rate gets stress tested at 7.5 percent for affordability purposes, while a 6 percent variable rate only gets stress tested at 9 percent. The math works against you in some cases. This is why I sometimes recommend running the same numbers through multiple calculators from different lenders before committing to anything. The output can vary by £50 to £100 a month on the same property and the same income. It comes down to how each lender weights your outgoings during the affordability assessment.
Get the Full Details
Using a calculator properly
Start by entering your actual deposit, not the dream deposit. If you are a first-time buyer looking at Help to Buy, remember that the equity loan portion doesn't reduce your mortgage payment because you are borrowing 80 percent regardless. The calculator will show the same monthly figure as if you had put down a 20 percent cash deposit, which is technically correct but misleading if you think your monthly burden is lower than it is. Always check what the calculator assumes about the end of the term. Some tools assume a repayment mortgage and calculate based on amortising the full balance. Others let you choose interest-only but then require you to specify a separate repayment vehicle like an investment fund. If you are considering interest-only, you need to show the lender how the capital will be repaid at the end. A calculator alone won't solve that problem. I usually factor in the arrangement fee by adding it to the mortgage balance and recalculating. It shifts the monthly payment by roughly £3 to £8 depending on the fee size and the term length. Not dramatic, but it adds up over five years and it's the kind of detail that separates an accurate estimate from a rough guess.
When the calculator fails
Self-employed borrowers. Calculators assume steady income. If you are a contractor or a business owner, your declared income might be lower than your actual earnings because you have tax planning in place. Most mortgage calculators won't account for this. You need a broker who understands how to present your accounts to lenders, because a calculator gives you a number and a broker gives you a path to get approved. Limitations matter here. Online calculators are fine for a quick sanity check or for comparing different rate scenarios. They are not fit for purpose if you are navigating shared ownership, significant deposit gifts from family, non-standard construction properties, or complex income structures. For those situations, the calculator is the starting point, not the destination. I've had people come to me after spending hours with a mortgage calculator United Kingdom tool convinced they knew exactly what they could afford. They had missed the fact that their desired property was built with reinforced autoclaved aerated concrete, which knocked 40 percent of lenders off the table, and that their broker would need to find a specialist lender with different terms and rates. The calculator couldn't see any of that. None of them could.
Use the tool. Just know what it can and can't do for you. It's a rough compass, not a GPS.