Understanding the Balloon Payment Mortgage
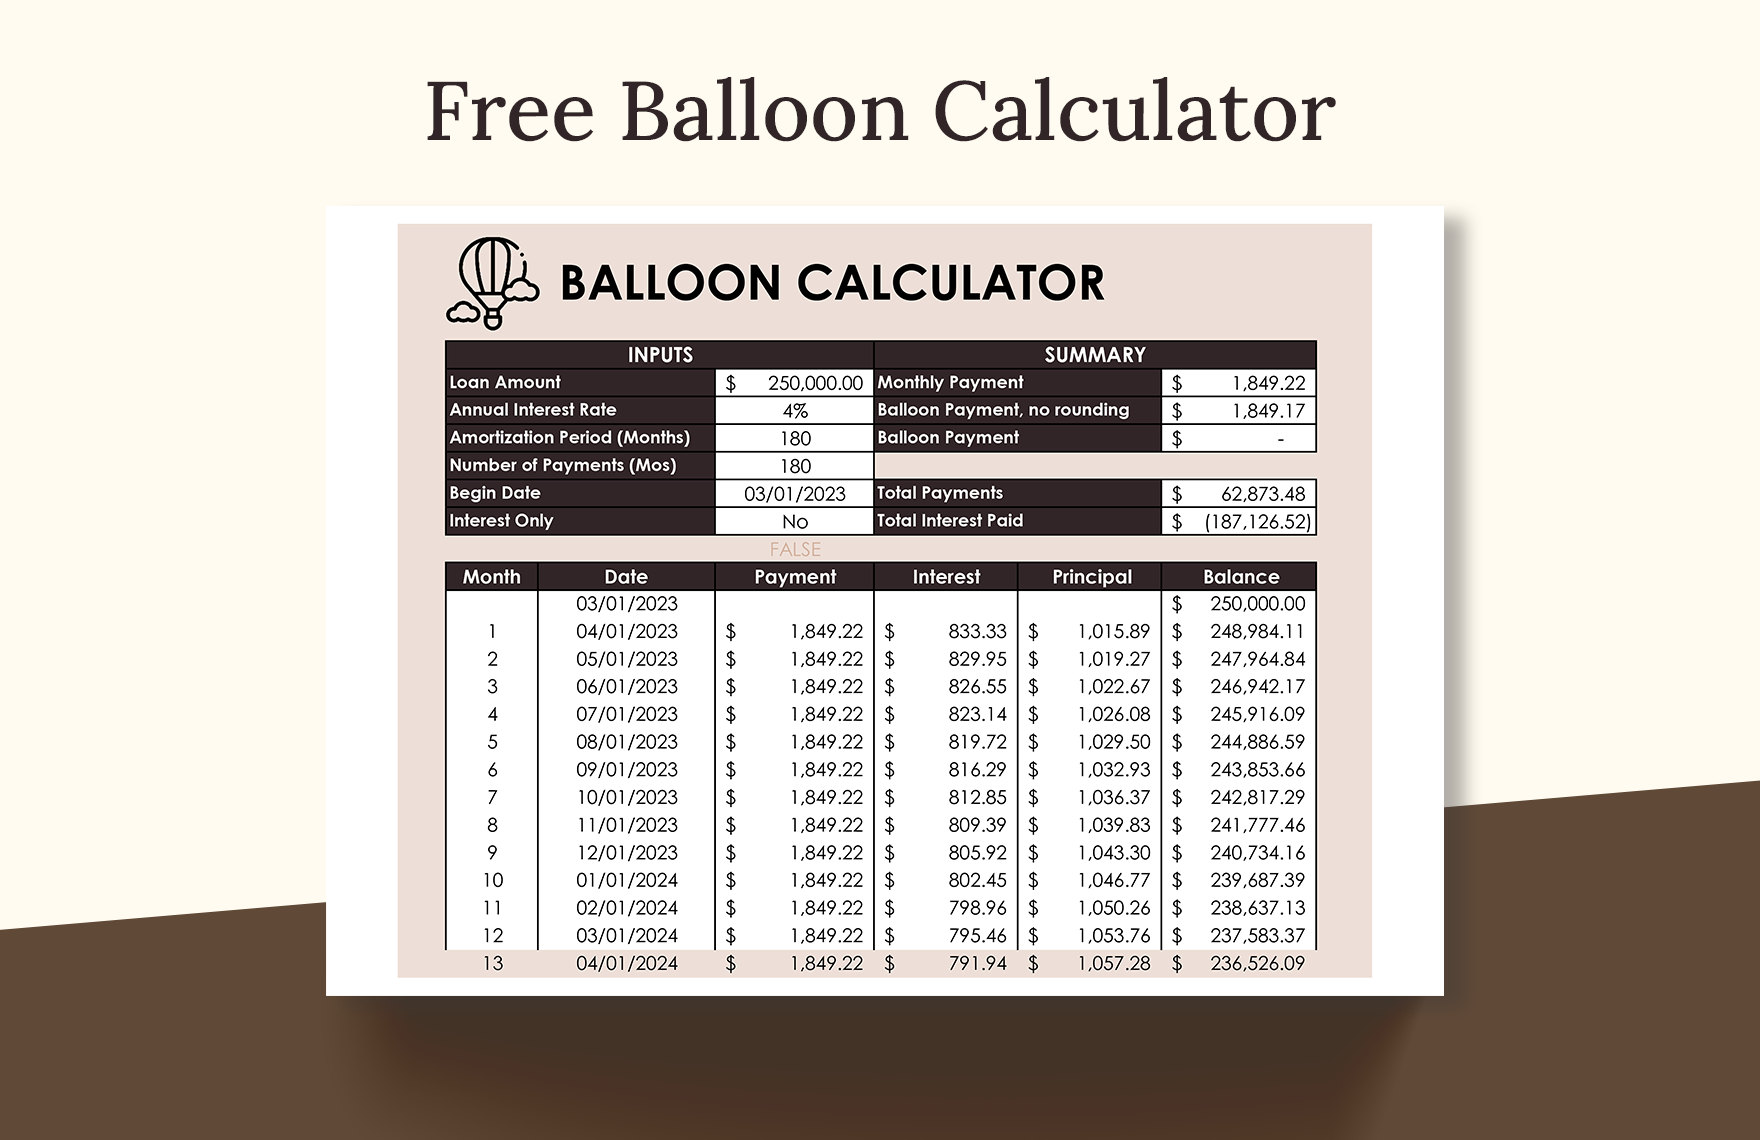
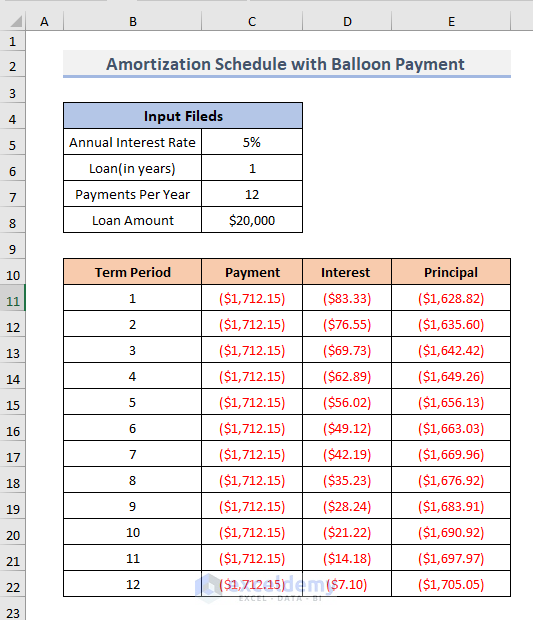
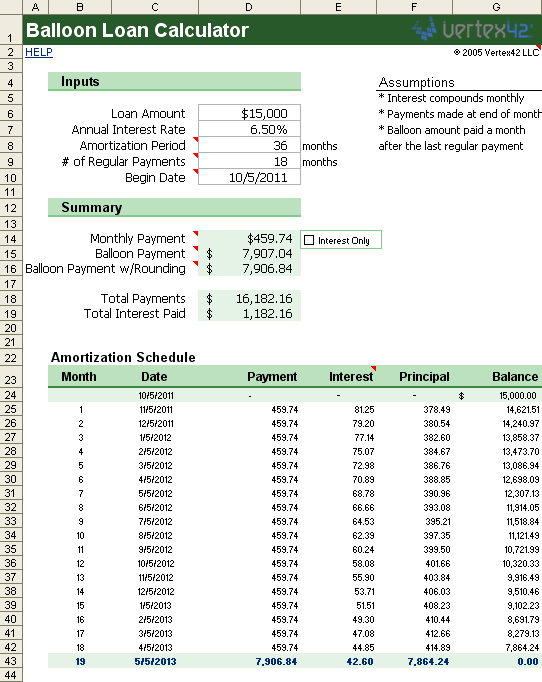
A balloon payment mortgage works like any other loan for most of its term, but at the end of a set period you owe the remaining balance all at once. The monthly payments are usually calculated based on a longer amortization schedule, but the loan itself matures much earlier. This creates a large lump sum due at the balloon date. Most people use this structure because the smaller monthly payments make qualification easier, or because they plan to sell or refinance before the balloon comes due. The calculator does three things. It takes your loan amount, interest rate, and term. It computes your monthly payment as if you were going to amortize the full balance over a longer period, typically 15 to 30 years. Then it tells you what the remaining balance will be when the balloon date hits. That remaining balance is your balloon payment. Everything else is straightforward arithmetic. Here is the actual calculation method. First you determine your periodic interest rate by dividing the annual rate by 12. Then you figure out your total number of payment periods for the amortization schedule. If you have a 30-year amortization, that is 360 periods. You plug those into the standard annuity formula to get your monthly payment. After that you calculate how much principal remains after however many payments you actually make before the balloon date. If the balloon is in 7 years, that is 84 payments made, and the remaining balance after payment 84 is what you owe.
The formula for the remaining balance looks like this: remaining balance equals the original loan amount times one plus the periodic rate, raised to the power of the number of payments made, minus the monthly payment times one plus the periodic rate, raised to the power of payments made, minus one, all divided by the periodic rate. It is not pretty but it is correct. Most online calculators use this same approach, sometimes with slight variations depending on whether they account for leap years or different day-count conventions. I have run into one specific edge case that trips people up constantly. Say you have a 7-year balloon on a 30-year amortization schedule at 6.25 percent interest on a $320,000 loan. Your monthly payment works out to roughly $1,971. After 84 payments you still owe about $277,000. That seems manageable until you realize you also need to factor in property taxes, insurance, and possibly HOA fees if your calculator does not include them. I once had a client who used a bare-bones calculator that only showed principal and interest. She thought her monthly obligation was under $2,000. It was actually closer to $2,650 once escrow items were added. She almost missed a payment in year five because of it. The workaround is simple: always use a calculator that includes estimated taxes and insurance, or add about 30 to 40 percent to your P&I payment as a rough escrow estimate if the tool you are using does not handle it. There is a counter-intuitive thing about balloon mortgages that nobody mentions in the brochures. The shorter your balloon term relative to the amortization schedule, the more you benefit from the lower monthly payment, but also the larger your balloon payment will be. People tend to focus on the payment amount and ignore the balloon size. A 5-year balloon on a 30-year amortization leaves you with roughly 83 percent of the original principal still owed. A 10-year balloon on the same schedule leaves about 70 percent. The difference in monthly payment between those two options might only be $40 to $60, but the balloon payment difference could be tens of thousands of dollars. Pick your balloon term based on when you realistically plan to exit the loan, not on which monthly payment looks nicer on paper.
Another nuance that gets overlooked involves prepayment penalties. Some balloon mortgages carry steep prepayment penalties that are calculated as a percentage of the remaining balance. If you are planning to refinance before the balloon date, check whether your loan agreement has a defeasance clause or a yield-maintenance provision. These can make early payoff significantly more expensive than just refinancing into a new loan. I found this out the hard way with a commercial client who thought she could simply refinance her balloon mortgage into a conventional loan. The yield maintenance provision added roughly $18,000 to her payoff cost. She ended up paying it because she had no choice, but it cost her months of research to discover what it was.
Get the Full Details

When a Balloon Mortgage Calculator Falls Short
Most free online calculators will give you the basic numbers. They will tell you your monthly payment and your balloon balance. That is useful. It is not sufficient if you are actually trying to make a decision about whether to take this loan. Here is why. A balloon mortgage calculator does not account for your personal financial situation, your credit profile, or the likelihood that you will actually be able to refinance when the balloon comes due. Interest rates at the time of the balloon could be much higher than they are today. Your income could change. The property value could drop. None of that shows up in the calculator output. If you are using this for a real purchase decision, I would recommend running the numbers through a spreadsheet where you can model different scenarios. What happens if rates go up 2 percent when you need to refinance? What happens if the property does not appreciate as much as you expect and you cannot sell without taking a loss? What happens if you miss a payment near the balloon date and your lender calls the loan? These are the questions a simple calculator will not answer for you. I also want to be clear about the downsides because nobody talking about balloon mortgages ever does. The biggest risk is refinancing risk. If the market tightens right when your balloon is due, you might not qualify for the refinance you need. Lenders tighten their standards during credit crunches, and that tends to happen around the same time people need to refinance balloon loans the most. The second risk is that the payment shock is real. Even if you do not have to pay the full balloon in one lump sum because you refinance, your new monthly payment will be higher because you are starting a new amortization schedule on a much larger remaining balance. Third, some lenders charge higher rates for balloon loans because they view them as riskier products. You might save on the monthly payment but pay more in total interest over the life of the loan if you end up holding it longer than expected.
For these reasons, I usually recommend that anyone considering a balloon mortgage also run the numbers through a standard amortization calculator assuming they keep the loan for the full amortization period. Compare the total interest paid under the balloon structure versus a traditional fixed-rate loan of the same term. In many cases the total cost ends up being similar or worse once you factor in refinancing fees and potential rate increases. The balloon structure only makes sense if you have a credible exit strategy and the numbers work in your favor under stress conditions.