How to actually use an amortization table instead of ignoring it
Most people run a mortgage payment and then close the browser tab. That is a mistake. The monthly payment number is only one data point. What actually matters is how the loan behaves over its entire term. An amortization schedule shows you that. It breaks down each payment into principal and interest, tracks the remaining balance month by month, and reveals how much you are really paying in interest over time. Without it, you are making decisions blind. I spent years helping clients restructure loans after they bought houses without looking at anything but the monthly payment. You would be surprised how many people sign documents for 30-year fixed loans and never realize that in the first five years, roughly 60 to 70 percent of their payment goes toward interest, not principal. The numbers are right there in the table. They just skip it.
Using a Mortgage Calculator With Amortization Table output
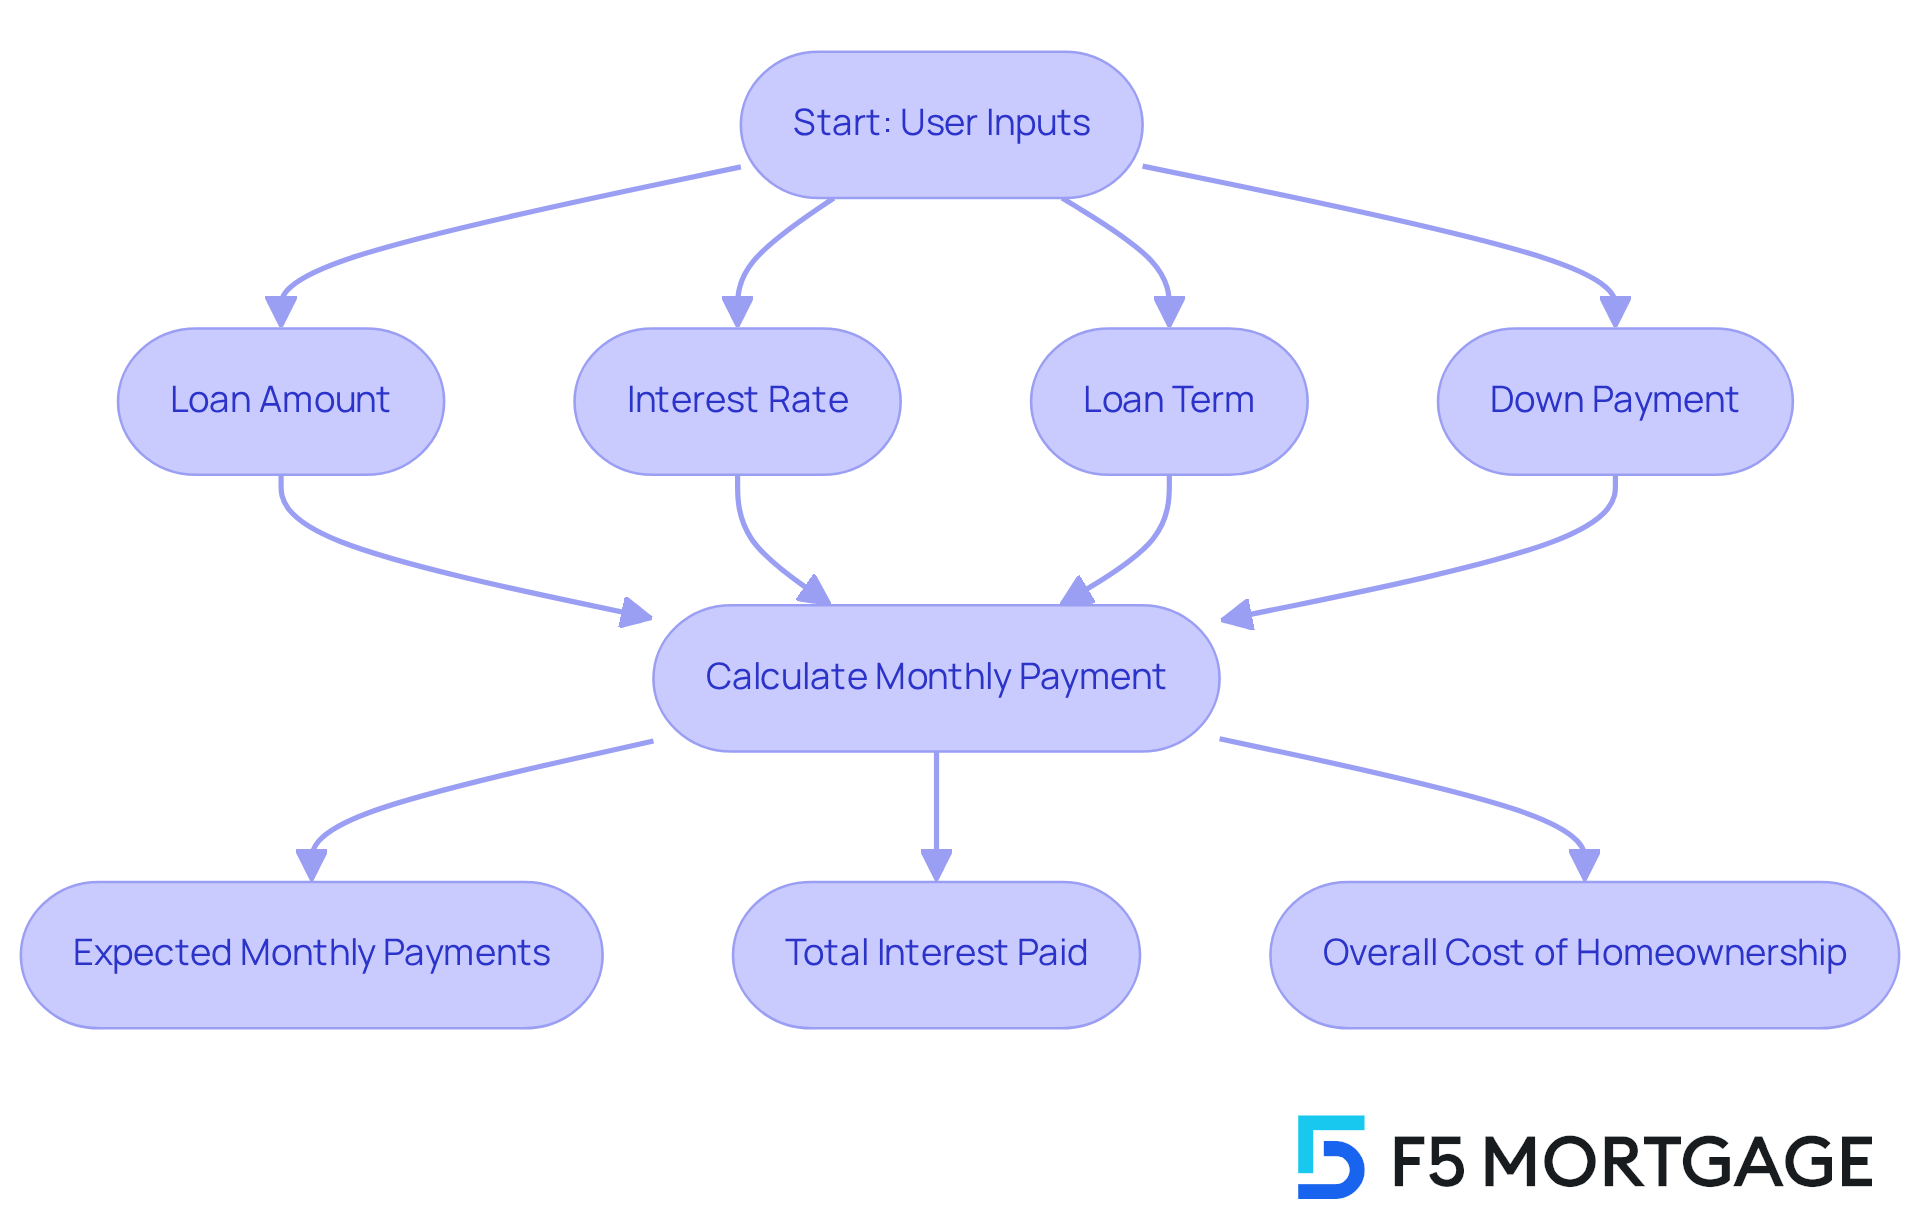
Here is how I go about it when a client sends me a loan scenario or I am evaluating options for someone. I input the loan amount, interest rate, and term into the calculator. The output gives me two things: the monthly payment and the full amortization schedule. I then look at three specific rows in that table to make sense of the deal. The first thing I check is payment one. The interest portion will nearly equal the total interest rate divided by twelve times the original balance. This is basic math, but it is also the part where people get confused about why their first payment barely touches the principal. A 6.5 percent rate on a 300,000 dollar loan means roughly 1,625 dollars in interest in the first month alone. If the monthly payment is around 1,896 dollars, only about 271 dollars reduces the principal. That is not a bug. It is how amortization works. The table makes it visible. The second thing I look at is the midpoint of the loan. For a 30-year loan, I pull up payment number 180. The remaining balance should be somewhere between 200,000 and 220,000 dollars depending on the rate. If it is higher than that, the loan is performing poorly from a principal reduction standpoint. If the borrower wants to refinance or sell before the term ends, this row tells you whether there is any equity to work with. I have seen people try to refinance at year three only to find they had almost zero equity because the amortization table showed them exactly where they stood, and they ignored it.
The third data point is the final payment. The remaining balance should hit zero. If it does not, something is wrong with the input or the loan includes a balloon payment. I caught a case once where a client was told they had a standard 30-year mortgage, but the amortization table showed a balance of about 48,000 dollars at the end. The lender had slipped in a balloon clause. The calculator output was the only thing that revealed it before closing. That one table saved my client from a financial headache that would have been very expensive to resolve after the fact. Mortgage Calculator With Amortization Table tools vary in quality. Some give you a clean downloadable spreadsheet. Others show a partial schedule and hide the rest behind a paywall. I prefer the ones that export to CSV or Excel because I can manipulate the data. If you are evaluating multiple loan options, being able to copy the schedule into a spreadsheet and compare them side by side is the fastest way to see which loan actually costs less over time, not just which has a lower monthly payment. One detail most online calculators do not show you clearly is the effect of extra payments. I run a simple sensitivity check myself. If I add 100 dollars per month to the principal on the 300,000 dollar example at 6.5 percent, the payoff date shifts by roughly four years and total interest drops by about 35,000 dollars. The amortization table makes that drop visible if you rerun the numbers. Most people do not bother. They accept the standard schedule and move on. The difference between a 30-year loan and a 26-year payoff is not dramatic on the surface, but it is massive in absolute dollars.
Get the Full Details
There are limitations to keep in mind. Standard amortization calculators assume fixed rates and fixed payments. They do not account for property taxes, homeowners insurance, or PMI unless the tool specifically includes those fields. If you are looking at an adjustable-rate mortgage, the amortization table for year one will not reflect what happens when the rate adjusts in year seven. I always note the teaser rate versus the fully indexed rate in my analysis. The table from the calculator is only accurate for the period it represents. If the rate changes, you need a new schedule. Some calculators offer ARM projections, but the output is usually rough and based on caps and margins that may not match your actual loan terms. Another common pitfall is rounding. Most calculators round the monthly payment to the nearest cent, but the amortization schedule may compound small rounding differences over 360 payments. I have seen schedules that were off by 10 to 20 dollars at the end due to rounding conventions. If you need precise numbers for a legal document or a refinancing decision, pull the schedule from your actual loan documents rather than relying on a generic online tool. The lender's amortization schedule will use their rounding method, which may differ slightly from the calculator you found on a blog. If you want something you can keep and reference later, download a spreadsheet version of the amortization table. Most serious mortgage professionals use Excel or Google Sheets because they can adjust assumptions without re-entering data. There are free templates available online that build the schedule automatically using the PMT and IPMT functions. The formula for the monthly payment is P times r divided by one minus one plus r raised to the negative n, where P is the principal, r is the monthly interest rate, and n is the number of payments. I use this formula in my own work rather than copying random templates because I can verify the output against the calculator results. If they match, I know the template is accurate. If they do not, I discard it and build a new one.
When comparing loans, I look at the total interest paid across the full term, not just the monthly payment. A 30-year loan at 6 percent will have a lower monthly payment than a 15-year loan at the same rate, but the total interest paid on the 30-year is more than double. The amortization table makes this obvious if you sum the interest column. I have had clients who were attracted to a lower monthly payment on a 30-year loan only to discover three years later that they had built very little equity because the table showed them where every dollar was going. Had they looked at the schedule before signing, they would have made a different choice. The best use case for an amortization table is when you are deciding between two loan options or when you are planning to make extra payments. Run both scenarios through the calculator, compare the total interest columns, and pick the one that saves you money over the life of the loan. It takes about ten minutes. The alternative is finding out years later that you could have saved tens of thousands of dollars by choosing differently. I also use the schedule when advising clients about prepayment penalties. Some loans charge fees if you pay down the principal faster than a certain threshold in the early years. The amortization table shows the principal portion of each payment. If you plan to accelerate payments, check whether the loan has a prepayment penalty clause before you start. Otherwise, you could save on interest only to trigger a penalty that wipes out most of the benefit. I saw this happen to a client in 2022. They paid down 20,000 dollars in the second year and got hit with a penalty equal to six months of interest. The amortization table did not reveal the penalty. The loan documents did. Always read the fine print alongside the schedule.
If you are looking for a reliable Mortgage Calculator With Amortization Table, I recommend starting with a calculator that provides full schedule export. Avoid tools that only show the first 12 months and charge for the rest. The output should include columns for payment number, date, principal paid, interest paid, total payment, and remaining balance. Those five columns are all you need to do a proper analysis. Anything less is incomplete.


