How Extra Principal Payments Actually Change Your Mortgage
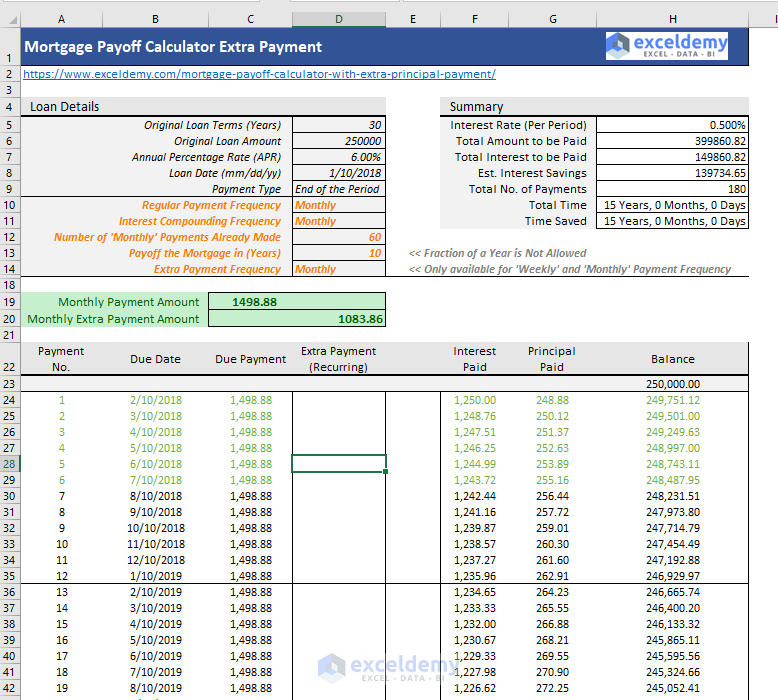
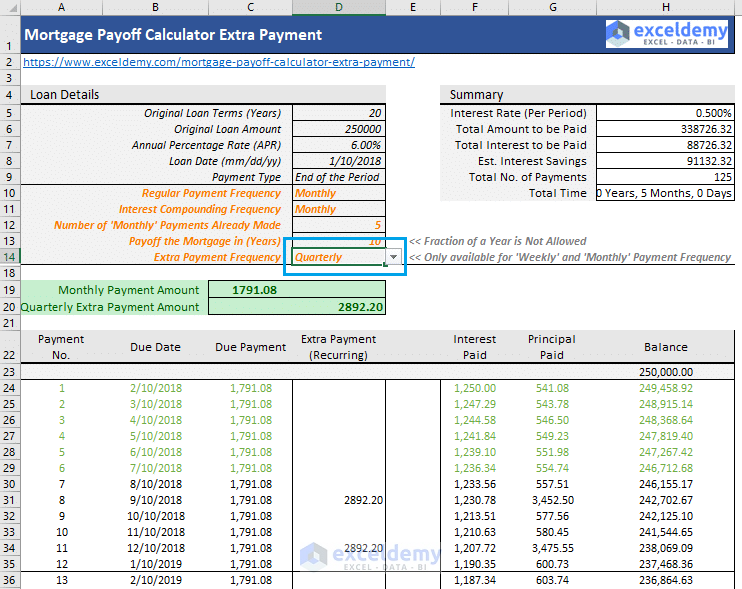
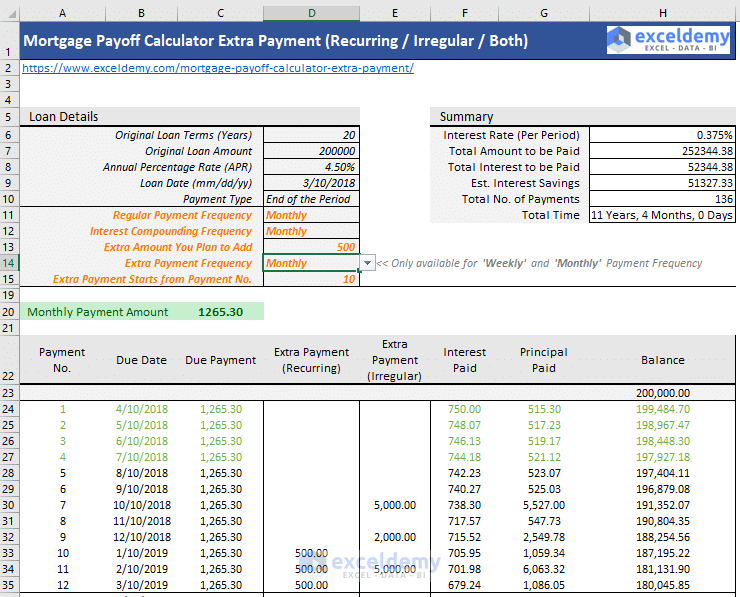
Most people treat their mortgage calculator like a crystal ball. It isn't. A Mortgage Calculator With Extra Principal Payment gives you a rough idea of what happens when you throw extra money at your loan, but the numbers it produces are projections based on assumptions that may not match your actual loan terms. That gap between the calculator output and reality is where people get surprised.Here is the basic mechanics. When you make an extra payment labeled toward principal, the servicer applies it directly to reduce your outstanding balance. Your regular monthly payment stays the same because the loan term does not automatically shorten. What actually changes is the amortization schedule. Each subsequent payment starts with a slightly smaller interest portion since interest is calculated on the new, lower balance. Over time, those compounding savings add up. The calculator shows you the end result, but it often misses the messy middle. I have built and maintained mortgage calculators for years, and the number one thing people get wrong is how they enter the extra payment. They type in a dollar amount and expect the calculator to know whether that payment comes every month, once a year, or randomly. Most free online tools either assume the extra goes every single payment or ignore the frequency entirely and just add it to the total paid over the life of the loan. That distinction matters more than most borrowers realize. Start by finding a calculator that lets you specify both the extra amount and how often you plan to pay it. Some let you choose monthly, biweekly, annual lump sums, or even custom schedules. If yours does not offer that level of detail, you are probably looking at a oversimplified tool that will give you optimistic numbers. Enter your current loan balance, not the original purchase price. Enter your current interest rate, not the rate when you first bought the house, unless you are doing a fresh purchase calculation. Enter the remaining term in months, not the original 30-year length, because the remaining time is what actually determines your payment.
Once those baseline inputs are correct, run the calculation with and without the extra payment and compare the outputs side by side. The difference between the two scenarios tells you more than either number alone. Look at three specific figures: total interest paid over the life of the loan, the number of months saved, and the new payoff date. Those three numbers are the ones that actually matter for your financial planning. Everything else is decoration.
The Part Nobody Warns You About
Extra principal payments do not always shorten your loan term the way a calculator says they will. I ran into this problem with a client who had a $420,000 loan at 6.25 percent with roughly 22 years remaining. She was putting an extra $500 toward principal every month. The calculator showed she would shave off about five years and save roughly $47,000 in interest. She felt great about it. Then her servicer sent her a statement showing the payoff date had only moved up by two years and ten months instead of the full five. The issue was that her loan had a prepayment penalty clause that kicked in after the first seven years. Every extra payment she made triggered a one-percent penalty on the amount over a certain threshold. The calculator did not account for the penalty because it had no way to read her loan documents. I had to manually recalculate by subtracting the penalty costs from the projected interest savings. The real savings dropped from $47,000 to about $31,000. Still significant, but nowhere near the promotional number the calculator flashed on the screen. That is why you should always read your actual loan agreement before you trust the output of any online tool. Another issue that comes up constantly is how servicers handle extra payments. Some apply them automatically to future payments rather than to principal. A few require you to submit a separate authorization form specifying that the additional amount goes toward principal. If you just send a check with a note and do not explicitly state it is for principal reduction, your servicer may apply it the way they see fit, which is often not the way you want it applied. Call your servicer and ask them directly how extra principal payments are processed. Write down what they tell you. The answer you get on the phone may differ from what their website says.
Get the Full Details

Counter-Intuitive Things About Extra Principal Payments
One thing most people do not expect is that making one large extra payment early in the loan saves dramatically more than making the same total amount in smaller payments spread across years. This is because interest is front-loaded in a standard amortization schedule. In the first few years of a 30-year loan at a typical rate, roughly 60 to 70 percent of each regular payment goes toward interest. Hitting the principal hard during that window compresses the entire interest calculation downward more than any equivalent payment made later. A single $10,000 extra payment in year two of a 30-year loan at 6.5 percent saves far more than ten $1,000 payments scattered throughout the life of the loan. A second thing people miss is that extra principal payments do not change your required monthly payment. Your payment stays fixed until the loan is paid off or refinanced. If you are counting on the lower payment to free up cash flow, you are mistaken. The only benefit is time savings and interest savings. Some servicers will recalibrate your payment if you pay off the loan early, but that is extremely rare. You are essentially paying down the balance faster while keeping the same monthly obligation. That is why the strategy only makes sense if your goal is to eliminate debt sooner, not to reduce your monthly outlay.
When This Strategy Falls Apart
Extra principal payments are not universally beneficial. If your mortgage interest rate is below 4 percent and you have high-interest credit card debt, student loans, or other obligations carrying rates above 6 or 7 percent, throwing extra money at the mortgage is usually the wrong move from a pure mathematics standpoint. The guaranteed return you get by paying off a 19 percent APR credit card far exceeds the 3.5 percent interest you save by prepaying a mortgage. I see people do this constantly, and it drives me nuts because the math is trivial. Another scenario where extra principal payments become questionable is when you are close to paying off the loan anyway. Once you hit roughly the last five years of a 30-year mortgage, the interest portion of your payment has already shrunk to a small fraction. Putting extra money at that stage saves you very little interest and mostly just accelerates a payoff that was already coming. The opportunity cost of tying up cash in home equity at that point can be higher than investing it elsewhere. Home equity is illiquid. You cannot easily access it without a refinance or HELOC, both of which come with their own costs and qualification requirements. There is also a tax consideration that calculators ignore entirely. In the United States, mortgage interest is deductible if you itemize, which reduces your effective interest rate. A 6.5 percent loan for someone in the 24 percent tax bracket is actually closer to 4.94 percent after the deduction. If you are not itemizing, the standard deduction already absorbs your interest benefit, and the effective rate is unchanged. Either way, online calculators assume a pre-tax rate and give you no indication of the after-tax reality. That matters most for higher-income borrowers who are well into the deduction phase of their loan.
Practical Steps to Make This Work for You
Get your current payoff statement from your servicer. Do not rely on the remaining balance shown on your monthly app or website. Those numbers often lag by a billing cycle or two. A payoff statement gives you the exact principal balance as of a specific date, along with any accrued interest and fees. Use that number as your starting point in the calculator. Test multiple scenarios. Run the calculator with an extra $200 per month, then $500, then $1,000. See how each level of extra payment changes your payoff date and total interest. This helps you find the maximum amount you can sustain without jeopardizing your emergency fund or other financial goals. Committing to an aggressive extra payment schedule that forces you into debt later is worse than making a modest but consistent extra payment over a longer period. Consider the biweekly payment structure as an alternative to random extra payments. By paying half your monthly obligation every two weeks instead of the full amount once a month, you naturally make 26 half-payments per year, which equals 13 full payments. That extra single payment per year goes entirely toward principal because your regular payment is already accounted for. It is a low-friction way to accelerate payoff without having to remember to make extra payments each month. The math works out similarly to making one extra monthly payment per year, though the timing is slightly different because the payments are spread throughout the year rather than concentrated at the end.
If you receive irregular income or a bonus, using that windfall for a lump-sum principal payment is one of the most effective ways to reduce interest costs. A single large payment in the first five years of your loan can cut your total interest by thousands of dollars. The calculator will show you the exact number, but the real-world impact is what matters. You are essentially buying back years of interest payments with money you already have. Keep an eye on your loan documents for prepayment penalty clauses and any restrictions on how extra payments are applied. These details vary by lender and by state. Some states limit or prohibit prepayment penalties entirely. Others allow them for the first several years of the loan. If your loan has a penalty, factor it into your calculation before you commit to an extra payment strategy. A calculator that ignores penalty fees is giving you a false sense of security.