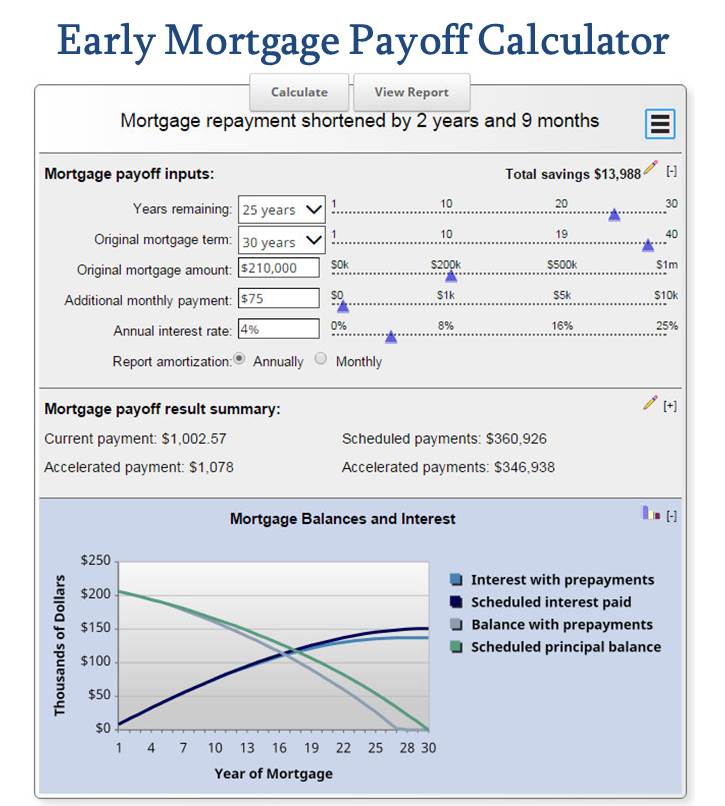
How a Mortgage Calculator With Lump Sum Actually Works
Most people treat lump-sum payments like magic, but they're just a straightforward principal reduction. When you throw extra money at your mortgage, the calculator simply re-allocates the amortization schedule. Your remaining balance drops faster, which means less interest accrues in the months ahead. That's it. The math isn't hard. What trips people up is usually the timing and the terms.
When you enter a lump sum into a mortgage calculator with lump sum, the tool asks one critical question: when does the payment happen? Make it in month three versus month sixty on a thirty-year loan, and the interest savings difference is massive. Early payments hit harder because they compound over more remaining periods.
The basic calculation works like this. You start with your original principal, subtract the lump sum, then run the standard amortization formula on the new balance for the remaining term. Some calculators do this by just subtracting months from your payoff date. Others recalculate every monthly payment with the new principal. The difference matters, and I'll get to that in a moment.
Mortgage Calculator With Lump Sum: What to Look For
Not all calculators handle lump sums the same way. The ones worth your time let you specify exactly which month the payment lands, whether it's applied to principal only or also covers escrow, and whether it adjusts your term or your monthly payment. The best ones show you both scenarios side by side.
A calculator that only asks "how much" without asking "when" is mostly decorative. You need timing granularity. If your tool only lets you pick years, you're going to get rough estimates that could be off by thousands of dollars in actual savings.
I built a custom spreadsheet years ago because no off-the-shelf calculator handled a particular edge case cleanly. My client had taken out a $420,000 conventional loan at 4.75% for thirty years, then received an unexpected $35,000 from the sale of a rental property. The twist was that the lender applied any extra payment to the current month's principal and interest first, then rolled any remaining amount forward. Standard calculators assumed the full lump sum went straight to principal in one clean hit. They understated the interest savings by about $1,800 because they didn't account for that partial-month allocation quirk.
What I ended up doing was manually splitting the $35,000 into two tranches, adjusting the amortization table month by month for the overlap period, and then letting the standard formula take over once the full remaining balance hit the principal. It took about twenty minutes of fiddling, but it gave a number that matched what the lender's own payoff statement showed within forty dollars. That level of accuracy matters when you're deciding whether to pay down a mortgage or invest elsewhere.
Why Timing Changes Everything
Let me give you a concrete example. Take a $350,000 loan at 6% interest over thirty years. Your regular monthly payment is roughly $2,098. Total interest over the life of the loan comes to about $405,480.
Now plug in a $25,000 lump sum paid right at the start. The new balance is $325,000. Recalculate, and your total interest drops to roughly $356,600. You save about $48,880 and pay off the loan nearly six years early.
Do the exact same $25,000 payment in year fifteen instead. Your remaining balance at that point is still around $290,000. After applying the lump sum, the new balance is $265,000. Total interest savings this time land around $19,200. You still come out ahead, but you're leaving roughly $30,000 on the table compared to making that payment upfront.
The lesson is boring but important:
the earlier the lump sum, the more it matters. This isn't rocket science. It's just how compound interest works in reverse. Every dollar you remove early saves you interest on that dollar for every remaining month in the loan.
Common Pitfalls People Miss
Prepayment penalties. Some loans, especially certain adjustable-rate mortgages and refinanced loans, carry clauses that charge a fee if you pay down principal aggressively in the first few years. A 2% penalty on a $50,000 lump sum wipes out any interest savings for the first three to five years. Always check your closing documents. I've seen borrowers skip this step and learn the hard way.
Second, many online calculators assume your payment stays fixed when you add a lump sum. In reality, some lenders will reamortize your loan, which means your monthly payment could actually go up slightly because your remaining term shortens but the payment structure recalculates. Other lenders let you keep the same payment and just shorten the term. Know which camp your lender falls into before you make any assumptions.
There's also the tax angle. Mortgage interest deductions on Schedule A are real for a lot of people, but reducing your principal faster means less deductible interest each year. If you're in a high tax bracket and itemize, that could cost you more in taxes than you save in interest. A rough rule of thumb: if your marginal tax rate is above 32%, the after-tax cost of your mortgage interest is closer to 4% than 6%, which changes whether paying it down early is the best move.
How to Use a Calculator Properly
Input your original loan amount, interest rate, and remaining term. Most people skip the remaining term part and just enter the full original term, which throws off the results if they're already halfway through the loan.
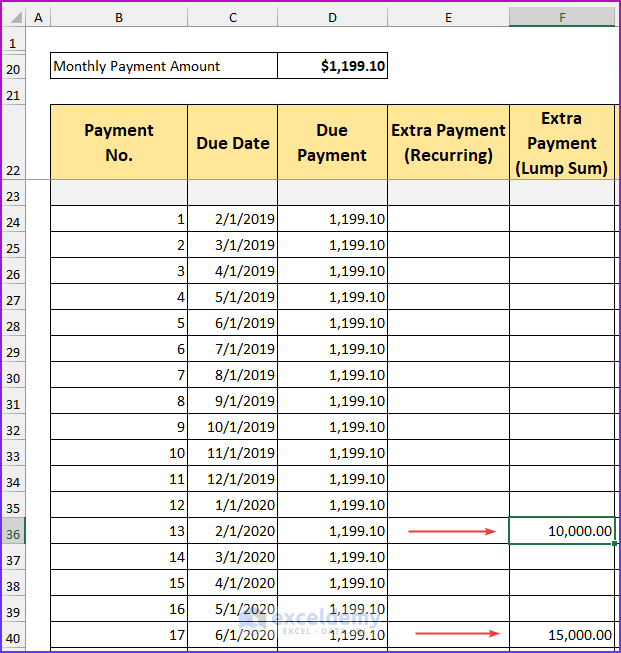
Enter the lump sum amount and the month you plan to make it. If the calculator doesn't ask for the month, find one that does, or adjust your inputs manually.
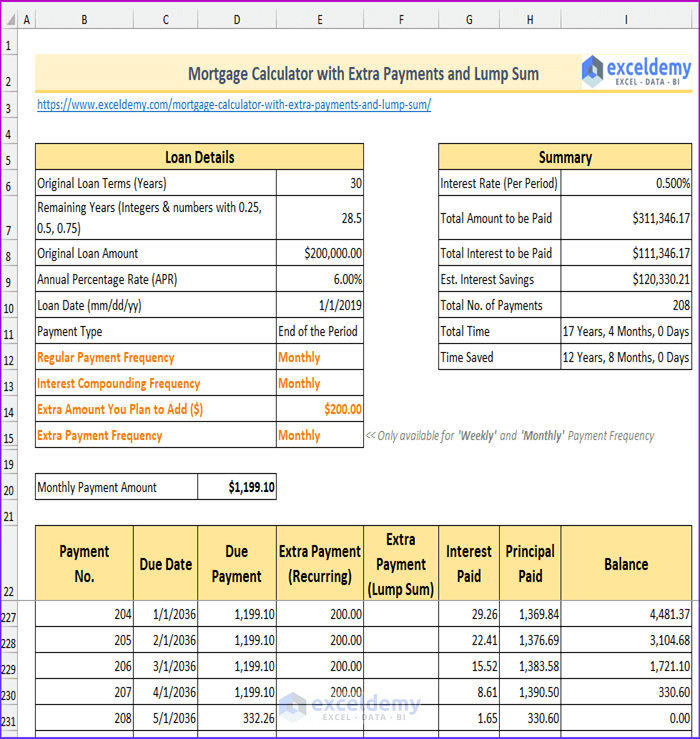
Run the baseline scenario first, with no lump sum, so you have a reference point. Then run the lump sum scenario. Compare total interest paid and payoff date between the two.
Some calculators will also show you a revised amortization schedule. Don't ignore it. Look at the first twelve months after the lump sum. If your payment amount changes unexpectedly, you'll see it there.
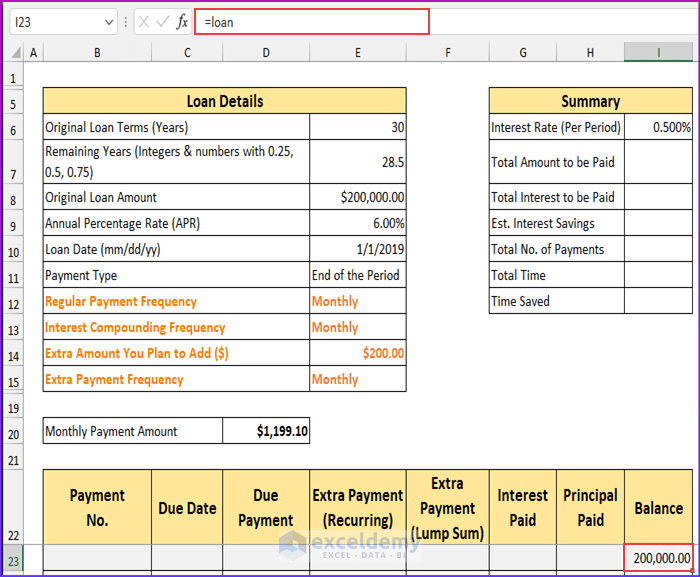
I usually cross-reference whatever number a calculator gives me against a quick manual check in a spreadsheet. I set up columns for payment number, beginning balance, interest portion, principal portion, and ending balance. After running thirty-six months of standard amortization, I drop in the lump sum as a negative principal adjustment in the appropriate row, and then let the formulas carry forward. It takes about ten minutes and catches calculator errors that might otherwise go unnoticed.
When a Lump Sum Might Not Be the Right Move
If your mortgage rate is below 4%, you're probably better off investing that lump sum in a diversified portfolio. Historically, the stock market returns 7% to 10% annually over long horizons. Locking that money into a low-rate mortgage is a guaranteed 4% return, minus any tax benefits, which puts your net return closer to 2.5% or 3%. That's not a great deal compared to what the market offers.
If you have higher-interest debt, pay that off first. Credit card balances at 18% or personal loans at 10% are a far bigger drain than a 5% mortgage. No calculator will tell you that, but it's worth stating plainly.
And if you don't have an emergency fund, don't drain your savings to make a lump sum payment. Being mortgage-free on paper while having zero liquidity is a risky position. I'd rather have three to six months of expenses in cash than an extra twenty thousand dollars in home equity that I can't touch without refinancing or taking out a HELOC.