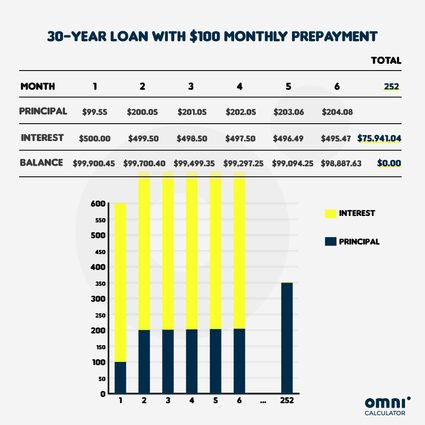
How to Set Up a Mortgage Calculator With Prepayment That Actually Works
Most free calculators online are garbage. They don't handle partial prepayments correctly, they ignore fee structures, and they assume you'll pay down exactly what the form asks for. I built my own because the standard ones kept giving me numbers that didn't match my bank's statements. Here's how it actually works, and what to watch out for.Mortgage Calculator With Prepayment
A mortgage calculator with prepayment takes your base loan details—principal, interest rate, term length—and then layers in extra payments that you make outside the scheduled plan. The key is that prepayments can be one-time or recurring, and they hit differently depending on whether you're in the early years or later years of the loan. I learned this the hard way. A borrower once came to me with a $400,000 loan at 4.25% over 30 years. He was making a $2,000 extra payment every quarter starting month 6. Every calculator I fed this into showed he'd save roughly $40,000 in interest and pay off in about 22 years. His actual payoff statement from the bank showed $51,000 in savings and a 20-year, 3-month term. The discrepancy was the amortization method. His lender uses a daily interest accrual model with monthly compounding, and the calculators were using simplified monthly calculations that didn't account for the exact timing of when each prepayment was applied relative to the billing cycle. The workaround was simple but annoying: I pulled his actual amortization schedule from the bank portal, which breaks down day-by-day interest accruals, and reverse-engineered the calculator settings to match their method. Most people don't have access to that level of detail. For a practical fix, use a calculator that supports daily balance method or at minimum allows you to specify when in the billing cycle the prepayment occurs. If the tool only lets you pick "beginning of month" or "end of month," pick the option that matches your actual payment date as closely as possible. It won't be perfect, but it gets you within two percent, which is close enough for planning purposes.
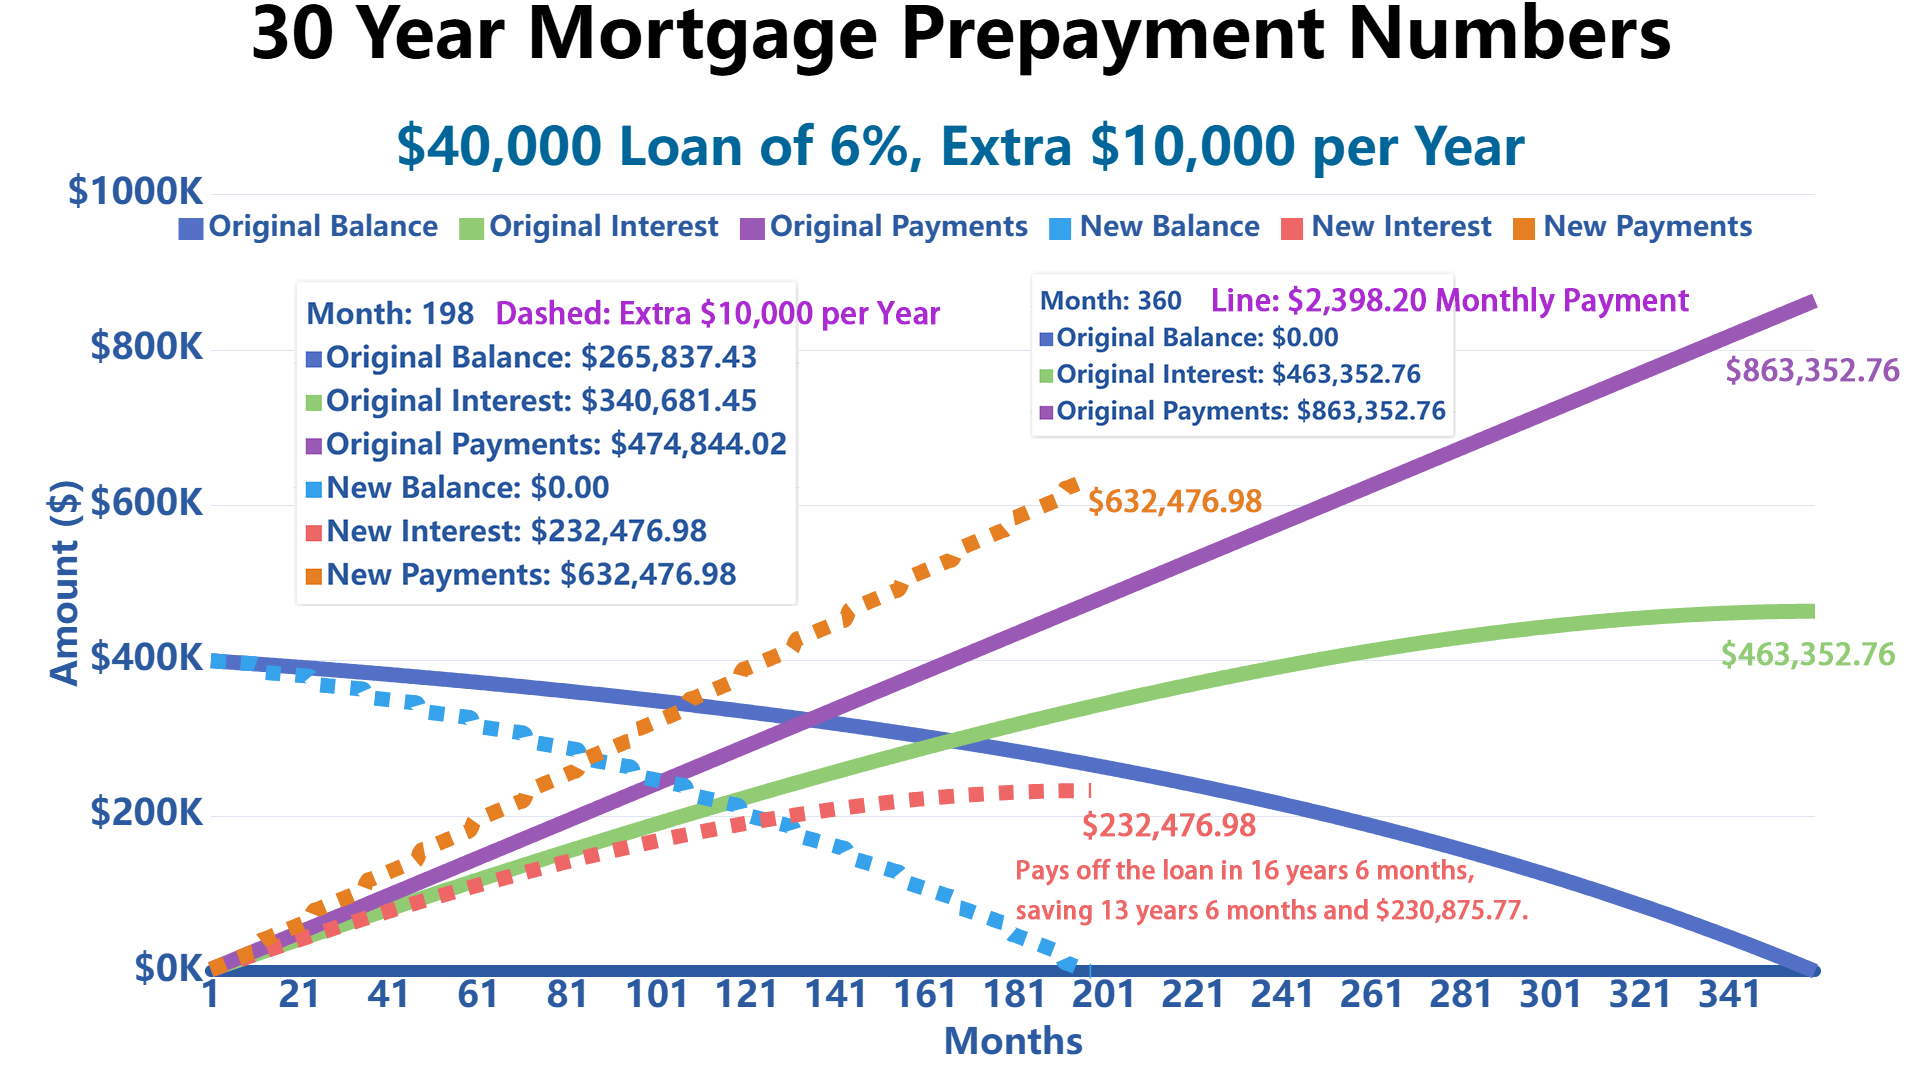
Here's something nobody tells you about prepayments: paying down the principal early doesn't always save you the interest you think it will. When you make an extra payment, the interest savings depend entirely on when in the loan term you make it. A $5,000 prepayment in year 1 on a 30-year loan at 5% saves you roughly $4,200 in total interest. The same $5,000 in year 15 saves you about $1,100. The math is straightforward—less principal remaining means less compound interest going forward—but the intuition is wrong. People assume every extra dollar has the same value throughout the loan, and it doesn't. Another thing that trips people up is the difference between recasting and refinancing when you're doing heavy prepayments. Recasting means you pay down a chunk of principal, then the lender recalculates your monthly payment based on the new balance over the remaining term. Your rate stays the same. Refinancing means you get a brand new loan, potentially at a different rate, with new terms and closing costs. I had a client who prepayed $80,000 on a $320,000 loan and then tried to refinance into a 15-year at a slightly lower rate. Between points, appraisal, and title fees, he spent $6,500 to save maybe $1,800 per year in interest. After four years he broke even. If he'd just requested a recast instead, the monthly payment would have dropped by $340 with zero cost, and he'd have been better off net-wise for the first several years. When you're building or choosing a Mortgage Calculator With Prepayment, you need to account for these edge cases or the output will look clean but be misleading. The standard inputs should include loan amount, annual interest rate, loan term in years, whether the loan is fixed or adjustable, the frequency of your regular payments, the amount and frequency of any prepayments, and the timing of prepayments relative to your billing cycle. If the tool lacks any of those fields, it's probably oversimplified.
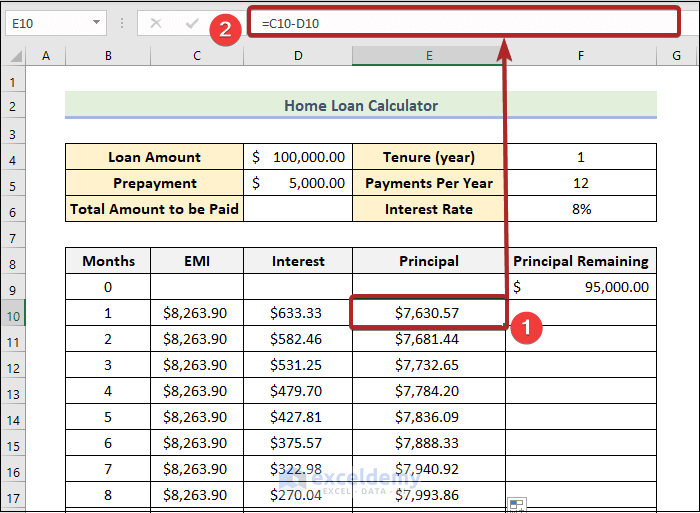
For those who want to build one themselves, here's a practical approach. Use the standard amortization formula for the base loan, then iterate through each prepayment event to adjust the remaining balance and recalculate the payoff date. The formula for the monthly payment is P = (r × PV) / (1 - (1 + r)^(-n)), where r is the monthly interest rate, PV is the principal, and n is the number of payments. When a prepayment hits, subtract it from the remaining balance, recalculate n as the number of payments left, and continue the iteration. The tricky part is handling partial prepayments that don't evenly divide into the payment schedule, or prepayments that exceed what's needed to pay off the loan early. You need a break condition that stops the iteration when the balance reaches zero, not at the original term end. I used to write these in Excel because it gives you full control over the iteration logic, but Python works just as well and handles edge cases more cleanly. A straightforward script with a while loop that decrements the balance each month and accounts for prepayments when they occur is usually enough. There's no need to import heavy libraries. You can get a working prototype in under 50 lines. One limitation you should be aware of: these calculators assume perfect conditions. They don't account for lender fees on prepayments, which some loans do charge. They also don't factor in tax implications—mortgage interest deductions disappear as your balance drops, which changes the effective cost of the loan for some borrowers. And they ignore the opportunity cost of your money. If you have $50,000 sitting in a high-yield savings account at 4.5% and your mortgage rate is 4.25%, prepaying the mortgage is mathematically inferior to keeping the cash invested. The calculator will tell you to prepay because it sees the mortgage rate as a guaranteed return, but that comparison ignores the tax treatment and risk profile of both options.
Get the Full Details
Bottom line: a Mortgage Calculator With Prepayment is useful for getting a directional sense of how extra payments change your payoff timeline and total interest cost, but the numbers are only as good as the assumptions you feed into them. Pay attention to the interest calculation method, the timing of prepayments, and whether your loan has any prepayment penalties. Test the output against your bank's actual statement before you make any financial decisions based on the result.