Figuring Out the Real Cost
I've sat at two screens comparing loan estimates side by side for years now. The spreadsheet approach works until it doesn't, and that's usually when someone is staring at two PDFs from different lenders and trying to make sense of why the monthly payments are identical but the total costs look completely different. Mortgage Comparison is mostly a exercise in translation. You are converting different lender terminology into the same language so you can see what you are actually paying. The method that saves time starts with the Annual Percentage Rate and the total closing cost column, not the interest rate. Lenders will give you whichever number makes them look better. A 6.5% rate with three points costs dramatically more than a 6.75% rate with zero points over a five-year hold, even though the lower rate looks cleaner on the page. I learned this the hard way during a refinance in 2019 when a broker offered me something that looked like the best deal until I added up the origination fee, the discount points, and the appraisal charge separately from the other lender's single all-in number. My workaround was to create a single row for every line item that appeared on both Good Faith Estimate and Closing Disclosure forms, then sum the out-of-pocket costs before any monthly payment calculation. That took me about twenty minutes and saved me roughly four thousand dollars.
Mortgage Comparison: What It Actually Means
At its core, Mortgage Comparison is checking loan terms, interest rates, fees, and closing costs across multiple offers to find the option that fits your financial timeline. It sounds simple. It is not simple because lenders bundle costs differently. One might roll an application fee into the rate while another charges it upfront. Another might advertise a low rate but add mortgage insurance that another lender structures differently. You have to unwrap each offer layer by layer. The most important document is the Loan Estimate. Every lender in the United States has to provide one within three business days of a formal application. It uses a standardized ten-page format now, which actually helps. Pages one through three contain the loan terms, projected payments, and costs. Page ten is a side-by-side comparison summary if you submit multiple applications. The problem is that people read page one and stop reading. Page two has the breakdown of closing costs that matters most. Look at Section B for services you cannot shop around for and Section C for services you can. That distinction alone changes your negotiating leverage. Here is something most calculators online will not tell you: the rate you see during the application process is a quoted rate, not a locked rate. It can shift between when you apply and when you lock, usually moving with the bond market. In 2022 I watched a quoted rate tick up by half a point over four days while a client was juggling two different loan programs. The fix was to submit both applications on the same morning and request a rate lock on both immediately, rather than waiting until after the credit pull. Waiting costs money, sometimes thousands.
Another counter-intuitive detail involves the discount points. Paying one point to drop your rate by a quarter percent sounds straightforward until you calculate the breakeven. At a quarter point reduction on a three-hundred-thousand-dollar loan, you save about twenty-one dollars a month. That is roughly forty-seven months to recover a three-thousand-dollar point. If you plan to sell or refinance before that window, the point was a bad move. I keep a simple breakeven chart on my phone now. It cuts the decision time from fifteen minutes to about two minutes per offer. There is a particular edge case with jumbo loans that nobody warns about. Jumbo programs often have stricter reserve requirements and higher credit score thresholds, which means the rates can look attractive on paper but the combined cost of rate buydowns and mandatory mortgage insurance from a separate lender can push the effective cost above a conforming loan. I ran into this with a client in late 2023 who had a jumbo quote that looked cheaper until I factored in the required six months of reserves held in liquid assets. The opportunity cost of tying up that cash offset the rate savings entirely. The workaround was to compare against a conforming loan with a higher rate but no reserve requirement and run the numbers through a net present value calculator instead of a simple payment comparison.
Get the Full Details

Building a Practical Comparison
Start by gathering Loan Estimates from at least three lenders. Two is the minimum, three gives you a real range. Do not use rate check tools that do not require a hard credit pull for the initial numbers. Those are marketing rates, not commitment rates. Real rate shopping requires a hard pull, and multiple hard pulls within a fourteen to forty-five day window count as a single inquiry on your FICO score for scoring purposes. That window matters. Spread your applications out and you will see your score dip multiple times for the same search. Here is the spreadsheet structure I use. Column A is the lender name. Column B is the note rate. Column C is the APR. Column D is the total closing costs. Column E is the monthly principal and interest. Column F is the total monthly payment including taxes, insurance, and HOA if applicable. Column G is the loan type and program. Column H is the lock period. Column I is the number of points purchased. Column J is the break-even in months if points were paid. This takes about ten minutes to set up if you already have the Loan Estimates in front of you. The trick most people miss is comparing apples to apples on the loan program itself. A 30-year fixed does not compare directly to a 7/1 ARM the way you might think. The ARM starts lower but resets based on an index plus a margin. In a rising rate environment, that initial payment looks great until year eight. I have seen borrowers lock into an ARM because the monthly payment was hundreds less, only to get hit with a payment increase that exceeded their budget after the first adjustment. The workaround is to run a stress test using the maximum possible rate increase allowed by the cap structure. Most adjustable-rate mortgages have periodic and lifetime caps. Plug the lifetime cap rate into your payment calculator and see if you can still afford it.
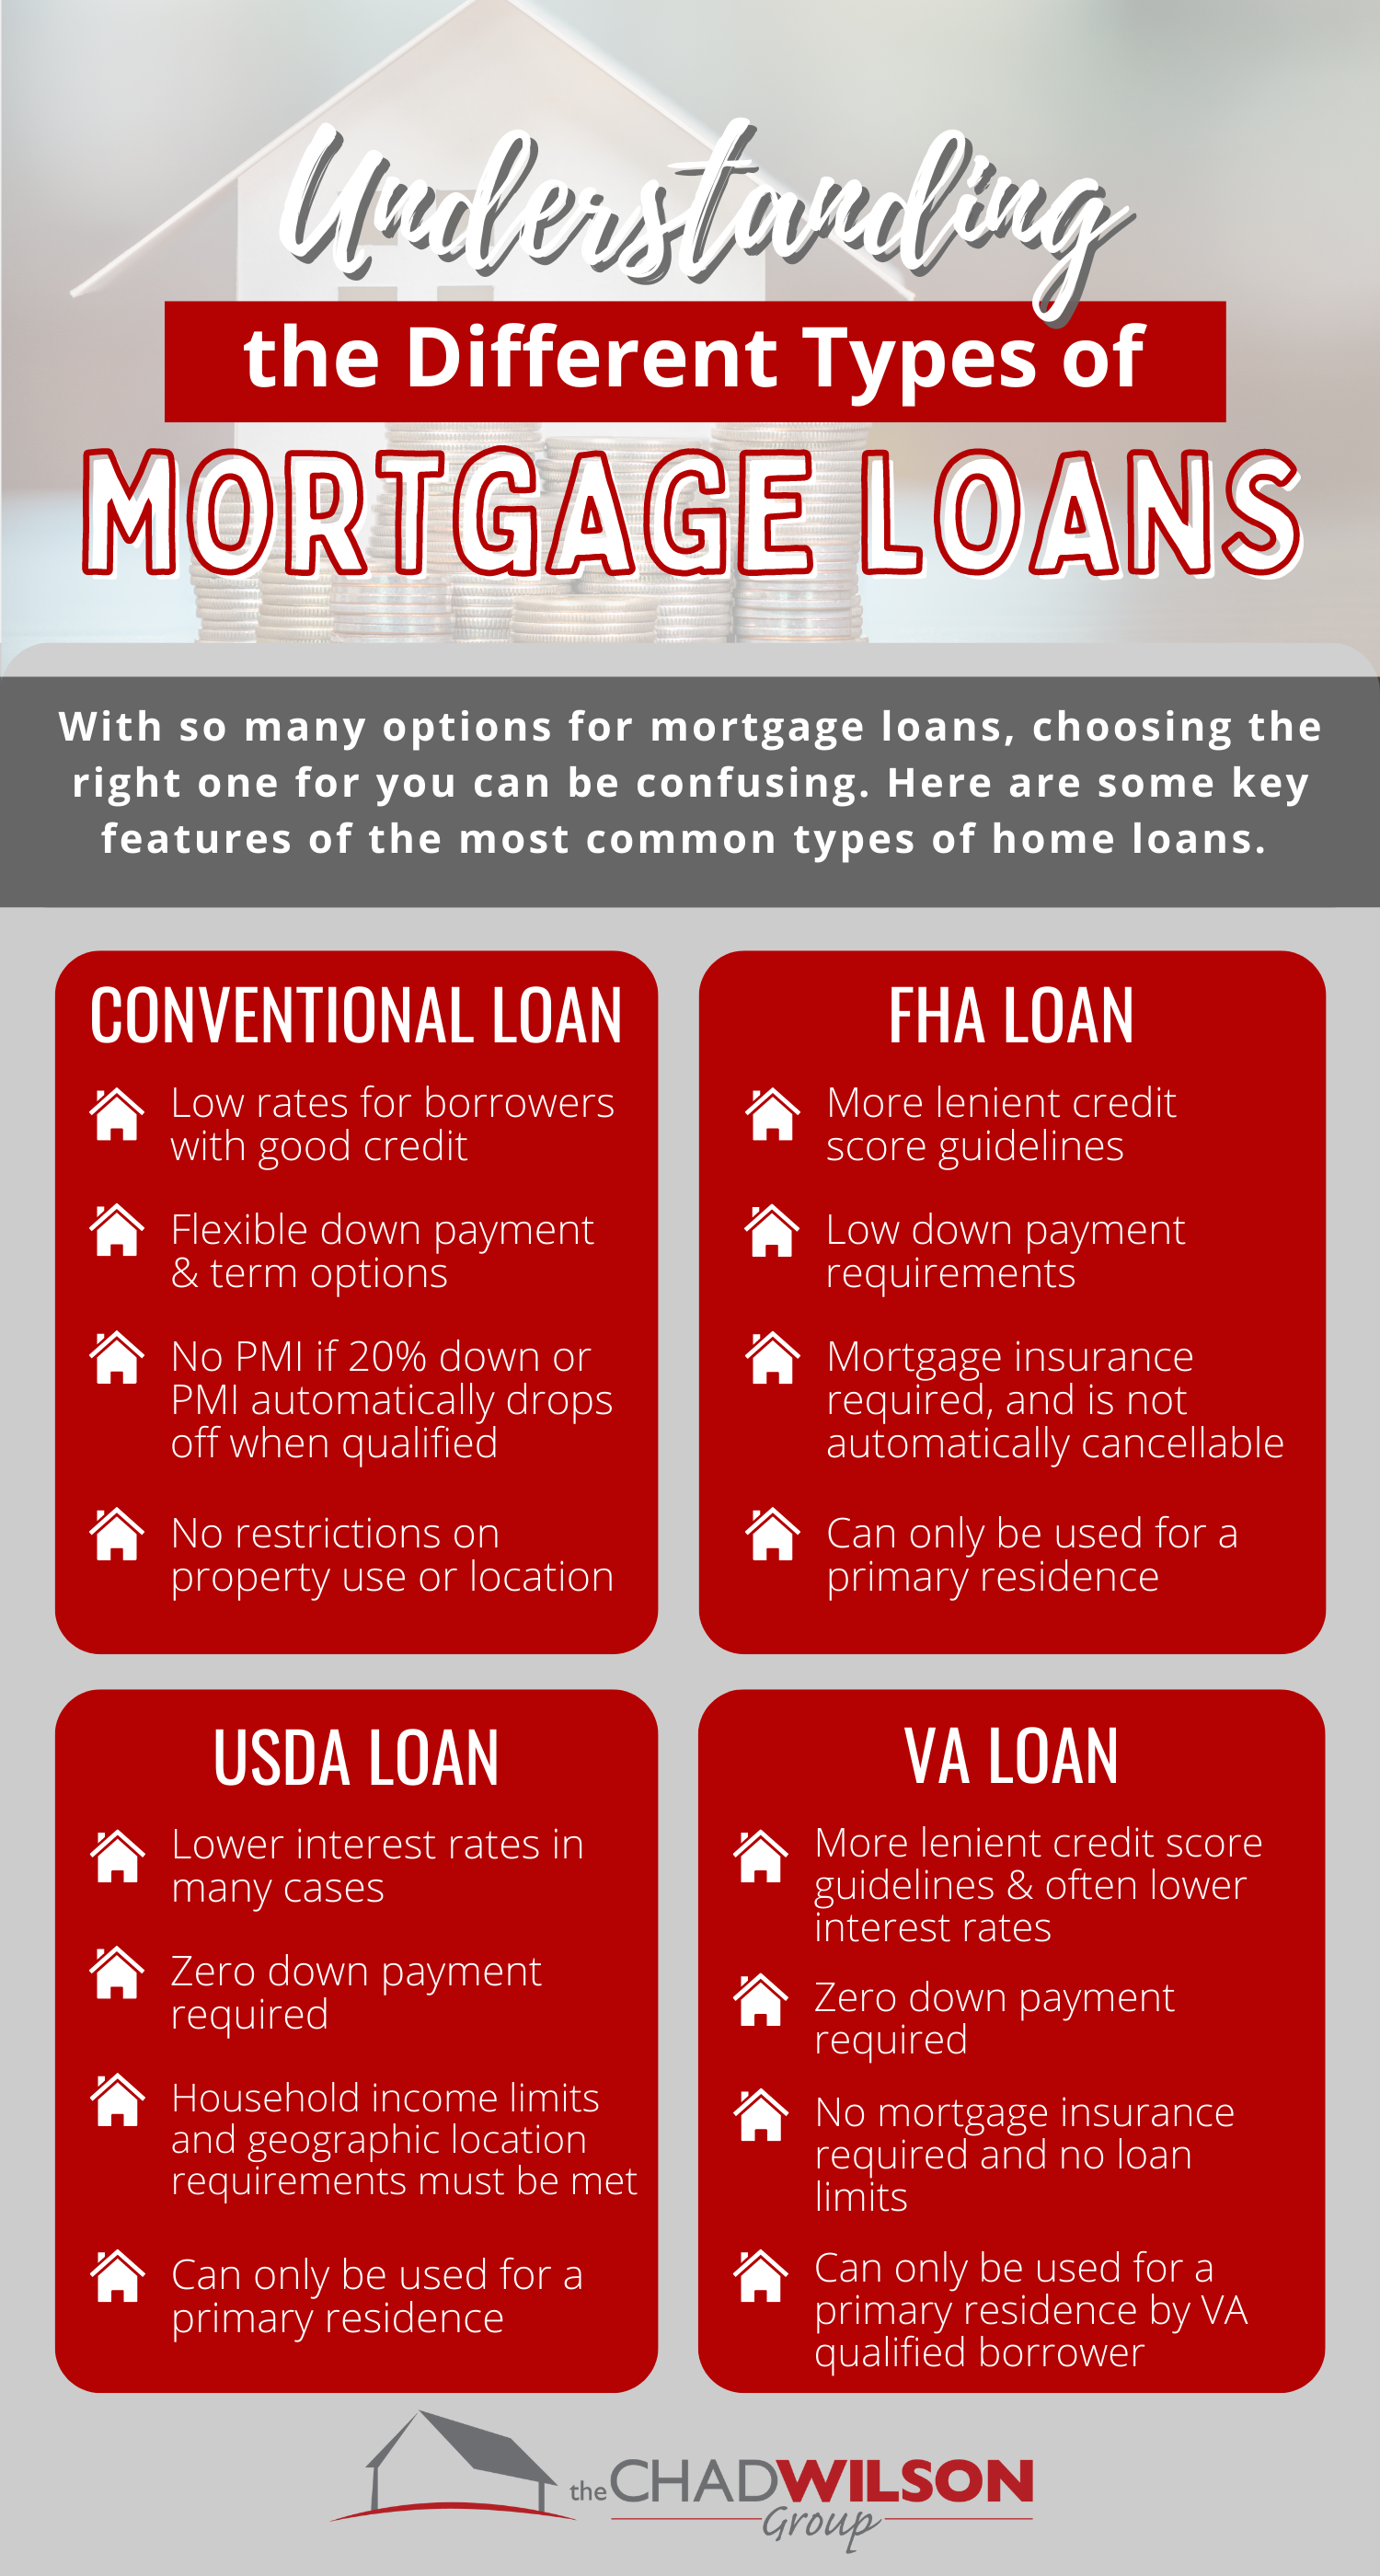
Down payment requirements vary enough between lenders that you cannot assume uniformity. Some will accept 3% down for first-time buyers through state programs. Others require 5% or 10% for the same product. The difference matters because dropping below 20% triggers private mortgage insurance, and the cost of that insurance differs by lender and by loan-to-value ratio. I once found a lender who charged a significantly lower PMI premium at 96% LTV compared to another lender at the same LTV. The rate difference was negligible. The PMI difference was about forty dollars a month. Over five years that adds up to twenty-four hundred dollars, which is not trivial. There is also the matter of lender credits versus upfront costs. Some lenders will offer a credit at closing that offsets your fees. That credit reduces what you pay out of pocket but usually comes with a slightly higher rate. The math favors the credit if you plan to move within three to five years because you avoid the upfront cost and the higher rate impact is minimal over a short horizon. If you are holding the loan for ten years or more, the lower rate with upfront costs typically wins. I tell clients to decide their expected timeline first, then run the comparison against that timeline, not against an assumed thirty-year hold.
Common Mistakes That Cost Money
The biggest mistake is focusing only on the monthly payment. A lower payment with higher fees and points can cost more overall than a slightly higher payment with lower upfront costs. The second biggest mistake is ignoring the lock expiration date. A rate lock that expires before closing forces you to either pay a lock extension fee or accept a new rate. Extension fees can range from a flat fee to a percentage of the loan amount. I had a client in 2021 who locked at a good rate but closed three weeks late due to appraisal delays. The lock had expired. The extension fee was two thousand five hundred dollars. If he had asked for a longer lock or monitored the timeline more closely, that money would not have been spent. A third mistake is not comparing the same loan amount and term. Comparing a 250,000 loan to a 300,000 loan tells you nothing useful. Make sure the principal amount, the property value, and the occupancy type match across all estimates. Differences in those variables change the rate and the costs in ways that make direct comparison invalid.
When Comparison Stops Working
This approach breaks down in markets where lender inventory is extremely thin. During the peak of the 2021 refinancing wave, some lenders stopped accepting new applications entirely or took weeks just to issue a Loan Estimate. In those conditions, having three estimates to compare is not realistic. The workaround is to prioritize speed over comparison. Lock with the first solid offer you receive and accept that the market condition limits your ability to shop. Waiting for more quotes in a broken market costs more than the potential savings from comparison. The method also fails when loans are non-standard. Portfolio loans, construction-to-perm loans, and certain commercial-to-residential conversions do not produce comparable Loan Estimates in a meaningful way. Each lender structures these entirely differently, and the cost components are not aligned. In those cases, the comparison shifts from rate and fee analysis to underwriting criteria and timeline reliability. Pick the lender with the strongest track record for that specific loan type rather than the lowest number on a spreadsheet. For most conventional purchases and refinances, the spreadsheet method with the columns I described above will give you a clear answer within an hour. The key is reading past the headline rate and looking at the actual cash you pay today plus the actual rate you pay over the life of the loan, adjusted for how long you plan to keep it.