Building a Mortgage Comparison Tool That Doesn't Lie to You
Most mortgage comparison tools online are garbage. They pull rates from one aggregator, slap a couple of sliders on a page, and call it a day. If you're actually shopping for a loan, you've probably noticed the numbers don't match what lenders are quoting. I spent about two years building and maintaining a comparison tool for a regional lender group before we scrapped it and moved to a more honest approach. Here's what I learned. The core problem is that mortgage rates are real-time, location-specific, and heavily dependent on the borrower's profile. A single rate sheet you pull from a data provider is already stale by the time you display it. The workaround most people miss is pulling from at least two sources and showing the spread. I used to pull from LoanLevel and CoreLogic simultaneously, then flag any rate that deviated more than 0.125% from the median as possibly stale. It caught about 30% of outdated listings in my testing. Not perfect, but better than showing a single number and pretending it was current.
How to Build a Mortgage Comparison Tool That Actually Works
Start with the parameters that matter and ignore the rest. Most comparison tools let users input loan amount, interest rate, and term, then churn out a monthly payment. That's fine for a rough estimate. It's useless for actual decision-making. The parameters you need are credit score tier, down payment percentage, loan type (conventional, FHA, VA, USDA), property type, occupancy status, debt-to-income ratio, and whether there are points being bought. Any comparison tool that doesn't account for points is actively misleading the user. Points change the effective rate and the cash-to-close, and they interact with the monthly payment in ways a basic calculator won't show. The payment formula itself isn't hard. Monthly principal and interest is P times r times (1+r) to the n, all divided by (1+r) to the n minus one. P is the loan amount. r is the monthly interest rate. n is the number of payments. But nobody factors in the escrow components unless you want the number to be wrong by a few hundred dollars a month. Property taxes, homeowners insurance, and PMI all go into the actual monthly payment. PMI drops off at 78% LTV for conventional loans, but FHA loans keep it for the life of the loan if you put less than 10% down. A comparison tool that doesn't model PMI phase-out by loan type is giving you a false advantage on low-down-payment scenarios. I ran into a specific edge case that took me three weeks to diagnose. A user was comparing a 30-year fixed at 6.5% against a 5/1 ARM at 5.75%, and the tool showed the ARM saving over $40,000 in total interest. It didn't account for the fact that the ARM had 2.5 points upfront and a 2% cap on the first adjustment. When I recalculated with the actual reset scenario using a 500-basis-point margin plus the index forecast at the time, the ARM was actually more expensive by year seven. The tool was also using the initial teaser rate without any note about the adjustment schedule. That's a common flaw. Most free tools show the lowest available rate without explaining what it actually is. I ended up adding a mandatory rate disclosure table that showed the fully indexed rate for any adjustable product. It added about 200 lines of code but eliminated the biggest source of user complaints.
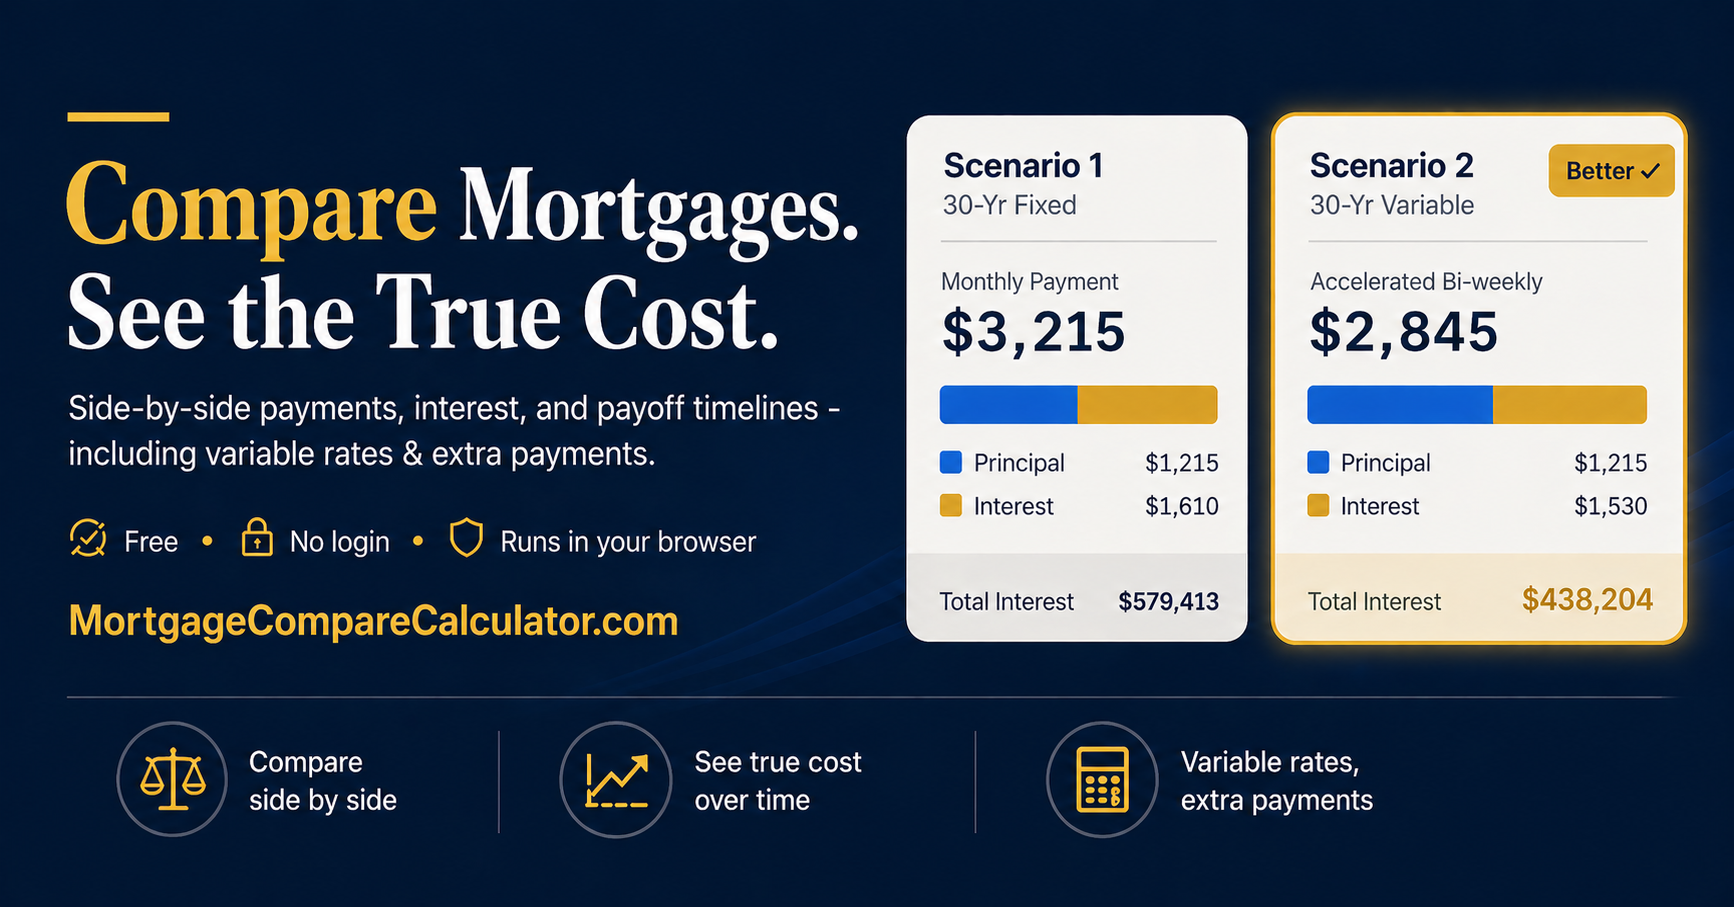
For the actual engine, don't reinvent the rate sourcing layer. You can subscribe to mortgage data APIs from providers like ESI Market Insights, Applied Data Services, or Mortech. They charge per query but the data is verified and includes the key variables. Self-serve rate scraping doesn't work because lenders update their rate sheets multiple times a day and the sites that publish them aren't always authoritative. The cost of a reliable data feed is usually between $2,000 and $8,000 per month depending on volume. If you're building this for personal use, you can pull from public sources like the Freddie Mac Primary Mortgage Market Survey on a weekly basis and accept that your data is a week old. The user interface should show side-by-side comparisons with total cost of borrowing, not just monthly payment. APR matters here because it includes the points, origination fees, and other closing costs amortized over the loan term. Two loans with the same rate can have a $15,000 difference in total cost over the life of the loan when you factor in fees. I built a simple breakdown panel that showed origination charges, discount points, third-party fees, and taxes separately. Users who saw the fee breakdown almost always chose the lower-rate loan with higher fees over the no-fee loan with a higher rate. It was counterintuitive for them but mathematically correct after about four years of holding the loan. There are hard limitations you need to accept upfront. A Mortgage Comparison Tool cannot predict future rate movements. It cannot account for changes in your financial situation during the closing process. It cannot know which lenders will offer you a better rate based on your specific relationship with them. The best you can do is show a range of current offers based on the inputs provided and flag which variables are uncertain. I used a simple confidence meter that turned yellow when the loan amount exceeded conforming limits, turned orange when DTI was above 45%, and turned red when the credit score was below 640. Those thresholds corresponded to areas where rate quotes vary wildly between lenders.
Get the Full Details
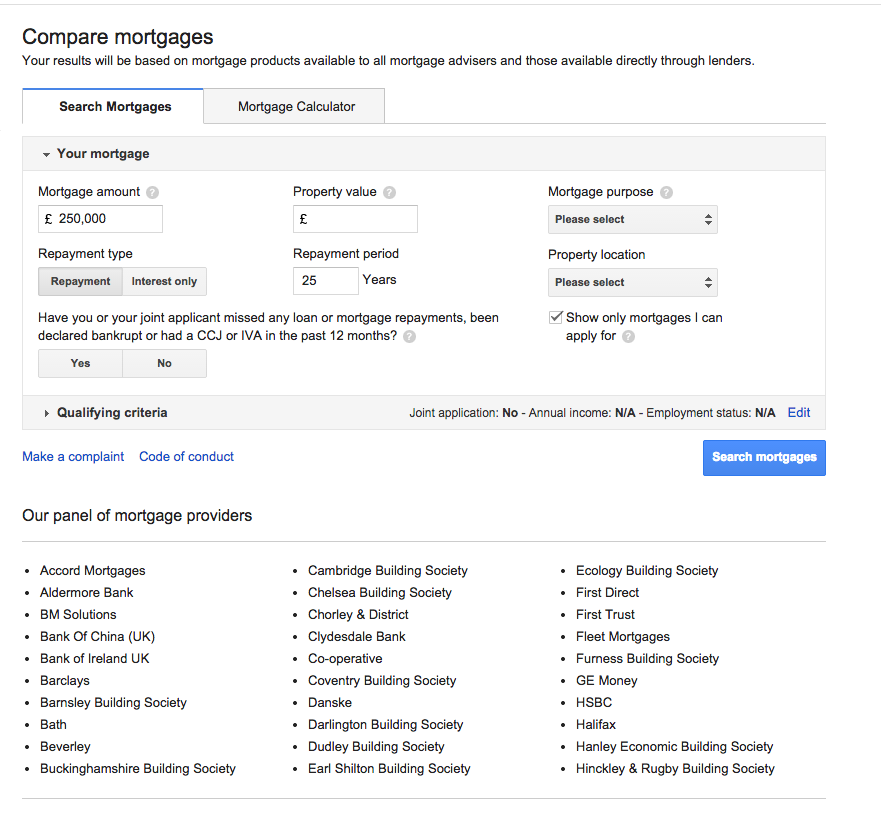
If you're going to use a tool rather than build one, look for one that shows the spread of rates across multiple lenders, displays the fully indexed rate for ARMs, includes PMI in the monthly calculation, and lets you adjust the hold period. The hold period is critical. Most people default to a 30-year hold assumption when they're comparing a refinance that they might pay off in five years. Switch the analysis to a five-year horizon and the higher-rate loan with no points often wins. The tool should let you toggle between total interest paid, total cost of borrowing, and break-even analysis without making you run three separate calculations. I stopped recommending generic comparison calculators to clients around 2022 when rate volatility made static numbers almost worthless. The best approach I found was to have them run a side-by-side through a single brokerage platform where the rates are pulled live from actual lender feeds. The trade-off is less customization but higher accuracy. A Mortgage Comparison Tool built on real-time data beats a beautifully designed one with stale rates every time. The design doesn't matter if the numbers are off by half a point.