How to Actually Use a Mortgage Deduction Calculator Without Getting It Wrong
Most people plug their numbers into a Mortgage Deduction Calculator and assume the output is final. It isn't. The output is a starting point, and the gap between that number and what actually shows up on your Schedule A is where most taxpayers lose money or trigger an audit flag. I've spent enough years reviewing tax returns to know that the real trouble isn't calculating the deduction. It's understanding what counts and what doesn't, then making sure your documentation survives scrutiny. Here's how it actually works when you stop treating it like a black box.Mortgage Deduction Calculator
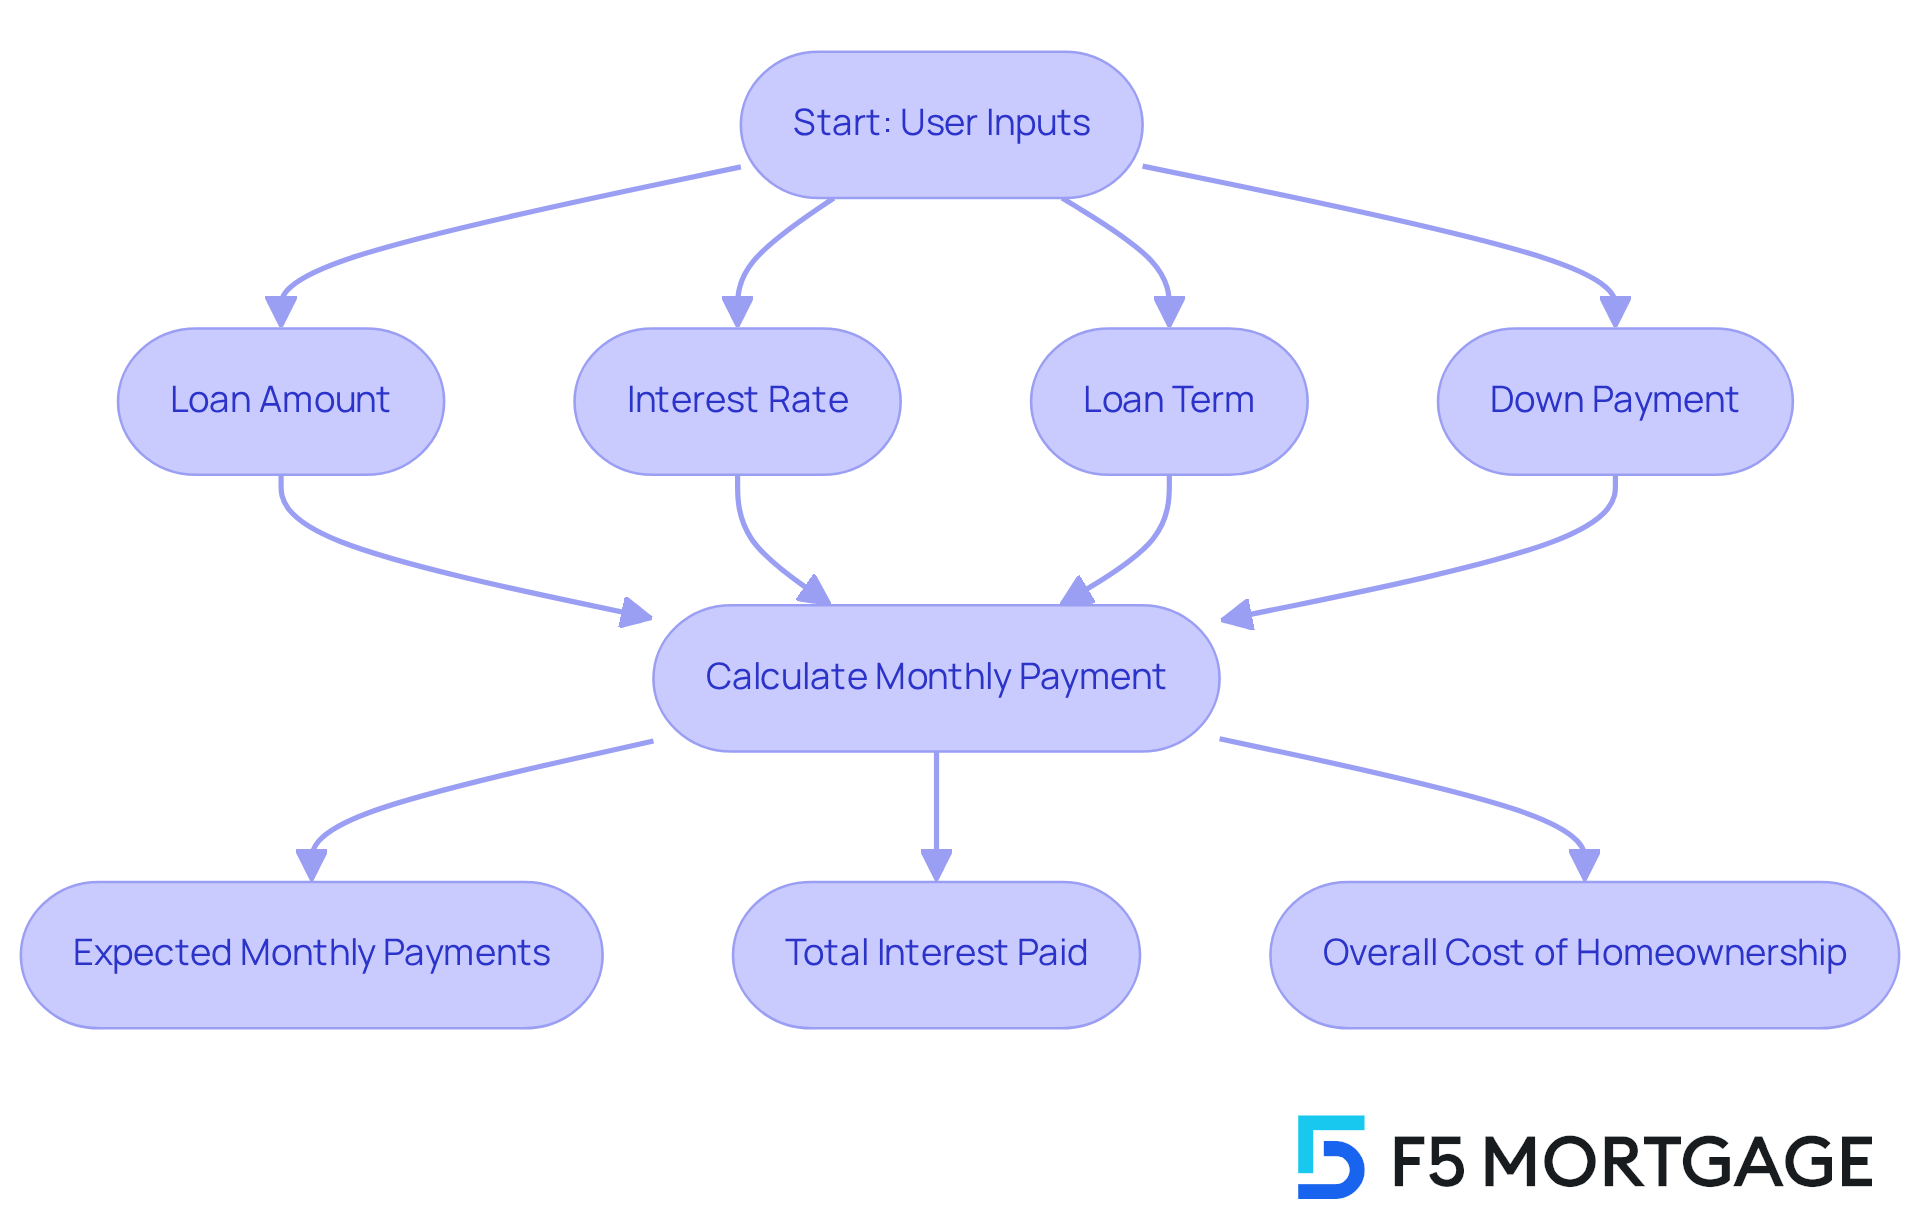
The basic function is straightforward. You enter your mortgage balance, your interest rate, and the loan start date. The calculator multiplies the outstanding principal by the rate to give you annual interest. That interest is what you're potentially deducting. Everything else—the escrow for taxes, the insurance, the PMI—is secondary and has its own rules. But here's the thing most calculators don't make clear: the limit on deductible mortgage debt depends on when your loan was taken out. Loans originated after December 15, 2017 are capped at $750,000 of acquisition debt. Loans before that date fall under the old $1 million rule. If you refinanced, the clock doesn't reset to today's date. The original loan date controls, and your refinanced amount has to stay within the applicable limit or the deduction shrinks proportionally. I had a client last year who refinanced a $900,000 loan taken out in 2015 down to $650,000, thinking the lower balance automatically qualified under current rules. It didn't. The original $900,000 still fell under the pre-2018 cap, but he had to prove the refinanced amount didn't exceed his original loan plus closing costs. That required pulling the original closing disclosure and comparing line items from three separate documents. Took me about forty-five minutes to sort through it, but without that work he would've claimed a deduction that would've been disallowed on audit. Another detail that comes up constantly and causes confusion: points. Points are prepaid interest, and they're deductible in the year paid only if they meet specific criteria. The loan has to be secured by your primary residence, the charge has to be an established business practice in your area, the rate has to be reasonable for your locale, and the points can't exceed what's typically charged. If any of those fail, you amortize the deduction over the life of the loan instead of taking it all at once. A Mortgage Deduction Calculator won't tell you which bucket your points fall into. That requires reading the Good Faith Estimate from your closing and checking state-level customary rates.
Let me walk through a realistic example. Say you have a $500,000 mortgage at 6.5% interest, taken out in March 2019. Your calculator spits out $32,500 in annual interest. That looks like your deduction. But you also paid $4,500 in property taxes and $1,200 in PMI during the same year. The total itemized deduction isn't just the interest. Property taxes are subject to the $10,000 SALT cap, which means if you also have state income tax, your combined deduction may be far less than you expect. PMI is deductible only if the loan was originated before 2026 and your income falls below certain thresholds, and even then it requires an extension to be in effect. For 2024 and 2025, the American Rescue Plan extension keeps PMI deductible up to $100,000 MAGI, phasing out above that. Without that extension, PMI premiums are simply not deductible at all. So the real workflow is this: run the calculator first to get your baseline interest number. Then cross-reference your closing documents against the acquisition debt limit for your loan date. Then check your points eligibility. Then layer in property taxes and PMI only if they qualify. Each step can change the final number significantly. I recommend keeping a single folder for your mortgage documents. Not scattered across email, cloud storage, and physical files. One folder. The original closing disclosure, the Final Settlement Statement, your annual 1098 from the lender, and any refinancing paperwork. When the IRS asks, and they sometimes do, having everything in one place cuts response time from days to minutes. It also prevents the embarrassing situation where you claim a deduction but can't produce the document that supports it within the statute of limitations.
Here's a counter-intuitive point that catches people off guard: paying extra principal doesn't reduce your mortgage interest deduction in the year you make the payment. It reduces future interest, which means future deductions shrink. If you're itemizing and planning to keep that strategy, making large principal payments earlier in the year actually gives you less to deduct that year. Some taxpayers intentionally time extra payments toward the end of the year because they've already maximized their itemized deductions and don't need the reduction. It sounds backwards, but it's a legitimate planning consideration if you're close to the standard deduction threshold. Also worth noting: mortgage interest on a second home is deductible, but only up to $100,000 of acquisition debt under the old rules or $375,000 under the post-TCJA rules, prorated across both homes if they share a combined limit above the per-home cap. A calculator might show interest on both properties, but the total deduction is capped at the lower of the combined limits. I've seen people deduct interest on two mortgages totaling $1.5 million because the software didn't aggregate them. That's an easy audit trigger. If you want to use a Mortgage Deduction Calculator effectively, treat it as one tool in a four-tool process. Run it for the baseline. Check your loan date against the debt limits. Verify points and PMI eligibility. Aggregate multiple loans if applicable. Do all four steps and you'll land on a number that's defensible. Skip any of them and you're guessing.
Get the Full Details