How Mortgage Estimators Actually Work (And Why the Numbers You See Are Sometimes Wrong)
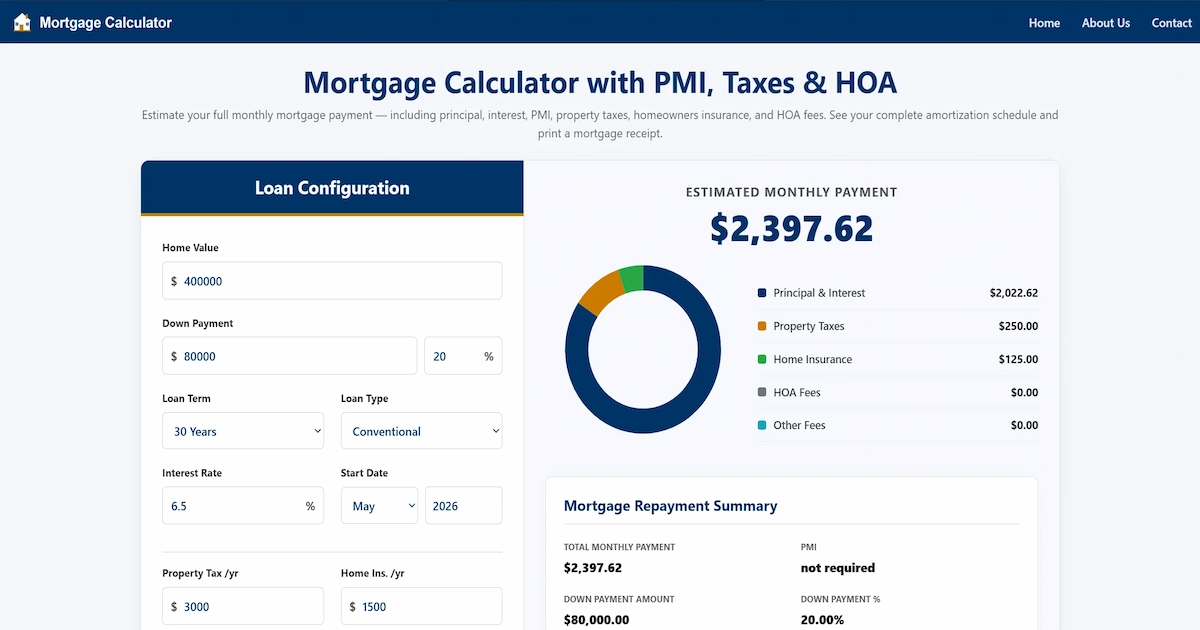
Most people type in a home price and interest rate and hit calculate, expecting a single monthly payment number. It doesn't work like that. A mortgage payment has at least four components, and any estimator you use needs to handle all of them. The problem is most free tools online either skip things or guess badly. Here's what goes into a real monthly payment: principal and interest, property taxes, homeowner's insurance, and either private mortgage insurance or HOA fees if applicable. That's PMIs for people who put down less than 20 percent. Any Mortgage Esrimator worth your time breaks these out separately rather than lumping everything into one opaque number. When they don't show you the breakdown, you have no idea what portion of your payment is going to escrow versus actually reducing your loan balance.
Calculating Principal and Interest Manually
The formula behind principal and interest is M = P × [r(1+r)^n] / [(1+r)^n - 1], where P is the loan amount, r is your monthly interest rate, and n is the total number of payments. You don't need to memorize that, but knowing how it works matters because it explains why the early years of your mortgage feel like you're barely making a dent. I remember running estimates for a client who was convinced their 30-year loan at 6.5 percent was costing too much monthly. The tool he'd been using showed a payment that looked reasonable on paper, but when we mapped out the amortization schedule, he'd paid down roughly $8,000 in the first year out of a $320,000 loan. The rest went to interest. That's not unusual, but people tend to underestimate how slowly equity builds early on. If you're planning to sell within five years, shortening the term or bumping your down payment changes the math significantly more than refinancing later ever will.
What Most Estimators Get Wrong
The biggest issue I've seen with online mortgage calculators is how they handle property taxes and insurance. A lot of them pull from county average tax rates and apply those across the board. That works fine if you're buying in a middle-of-the-road area, but property tax rates vary enormously even within the same county. I had a situation where two houses on the same street had different effective tax rates by nearly 40 percent because one had recently been reassessed after a sale and the other hadn't been updated in fifteen years. An estimator using generic averages would have been off by hundreds of dollars monthly. Another common problem is how PMIs are calculated. Some tools assume a flat 0.5 percent of the loan amount annually, others use 1 percent, and some still reference older tables based on credit score tiers. The actual PMI rate depends on your credit score, loan-to-value ratio, and the specific lender's requirements. If you have a score above 740 and put 15 percent down, your PMI could be half of what a basic estimator projects. On the other hand, if you're putting 5 percent down with a 680 score, it might be double what the tool shows.
Get the Full Details
A Practical Workflow I Use
When I need to give someone a reliable estimate, I start by gathering the actual numbers rather than relying on averages. That means calling the county assessor's office for the current tax rate on the specific parcel, checking the home insurance quote from at least two providers, and looking up theHOA fees if there's a community. Then I plug those real numbers into a calculator instead of letting the tool guess. For the PMI piece, I check the lender-specific requirements rather than using a generic rate. Most calculators online don't let you adjust for credit score, so I manually recalculate that component after getting the base payment. This usually adds about 20 minutes to the process, but it also means the estimate is accurate enough that people don't get blindsided during underwriting. If you want a free tool that does most of this reasonably well, the calculators at FRED from the Federal Reserve Economic Data are clean and pull real historical rates. For something more interactive, the Bankrate mortgage calculator lets you adjust property tax and insurance manually, which gets you closer to reality than the default inputs. There are also a few downloadable spreadsheets on financial forums that handle escrow calculations better than most web-based tools. Search for "mortgage amortization spreadsheet with PMI" and you'll find a handful that people maintain and update periodically.
When Estimators Completely Fail
Arms-length transactions, jumbo loans, and adjustable-rate mortgages after the initial period are where most estimators break down. If you're buying a fixer-upper where the assessed value hasn't caught up to the purchase price, the tax estimate will be wrong until the county reassesses. Jumbo loans often have different rate structures and PMI isn't always available, so you're dealing with different underwriting criteria entirely. And for ARMs, the estimator showing you the initial rate payment is giving you a number that won't reflect your actual payment after year five when the adjustment happens. There's also the case of FHA loans where the upfront mortgage insurance premium gets rolled into the loan balance. Standard calculators don't account for that correctly. You end up with a slightly higher principal than you expect, which means your interest calculations are off by a small but noticeable amount over the life of the loan. The workaround is to add the UFMIP to your loan amount before running the calculation, then factor the monthly MIP into your escrow line separately. The bottom line is that a mortgage estimator is a starting point, not a definitive answer. The tool gives you a ballpark figure, but the real numbers come from actual tax records, insurance quotes, and lender-specific terms. Spending an extra half hour gathering those inputs beats getting a surprise three hundred dollars higher payment at closing.