How FHA Mortgage Estimators Actually Work in Practice
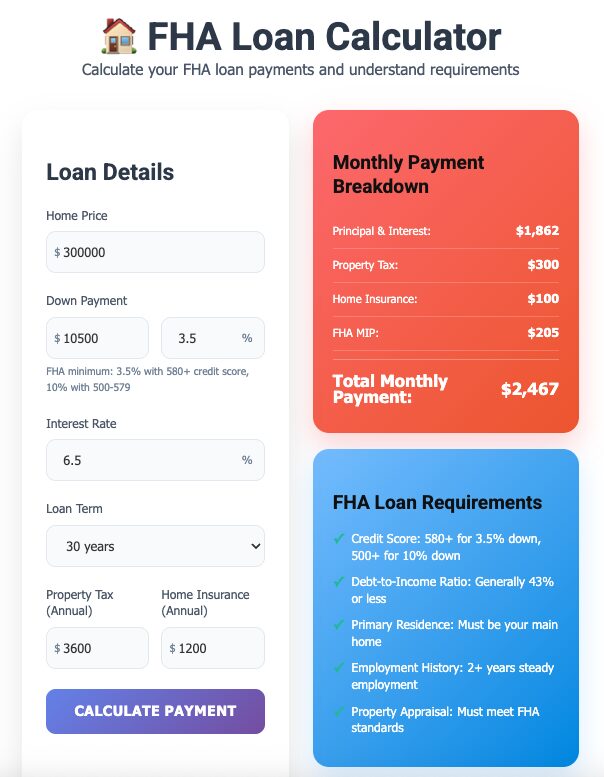
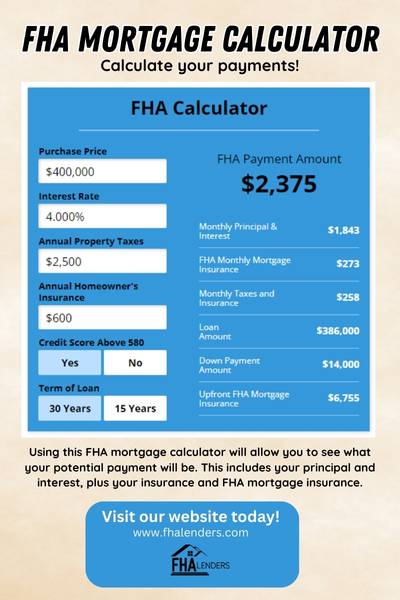
A mortgage estimator for FHA loans is a tool that approximates your monthly payment based on loan amount, interest rate, and the unique requirements that come with an FHA-backed loan. Most people find the estimates useful as a starting point, but they should understand what goes into those numbers before treating the output as gospel. The calculator takes your input data and runs it through a standard amortization formula, then layers on the FHA-specific costs on top. That layering is where things get tricky. A conventional loan calculator will show you principal, interest, taxes, and insurance. An FHA estimator adds two items most borrowers don't expect upfront: the upfront mortgage insurance premium and the annual mortgage insurance premium, both of which affect your monthly payment in ways that change over time. The upfront MIP gets rolled into your loan balance, which means you're paying interest on insurance. That's not intuitive, and most first-time FHA borrowers miss it entirely when they look at an estimate.
Using a Mortgage Estimator Fha Tool Effectively
I found this out the hard way back in 2019 when I was running estimates for a client who was shopping around between conventional and FHA options. She picked an FHA loan because the down payment was lower, and the estimator showed her a monthly payment that looked competitive with a conventional alternative. She almost committed before I caught that her estimated home price was right on the FHA loan limit for her county. Once you hit the conforming loan limit, the MIP calculations change because the insurance premiums are tiered by loan amount, and her payment jumped by about sixty dollars a month once the actual figures were pulled. We ended up switching to a conventional loan with PMI instead, and she saved roughly four hundred dollars over the life of that particular loan term. The main thing most people don't realize is that FHA mortgage insurance lasts for the entire loan term if your down payment is less than ten percent. If you put down ten percent or more, it drops off after eleven years. That timeline matters enormously for long-term affordability, and a basic estimator rarely makes that distinction clear. It shows you a monthly number and moves on. You need to ask whether that number stays the same for thirty years or decreases after year eleven, because that difference changes your real cost of borrowing substantially. Input accuracy is everything. If you round your home price, interest rate, or property tax estimate, the output shifts enough to mislead you. A quarter-point difference in interest rate on a two hundred thousand dollar FHA loan changes your principal and interest portion by roughly forty dollars monthly. Add in the fact that property tax estimates from online tools are often generic, and your total monthly figure could be off by a couple hundred dollars without warning.
Here is what you should do to get a reliable estimate. Start with your exact intended purchase price or appraisal value. Pull your actual credit score range because FHA rates vary by score tier. Get a property tax figure from your county assessor's office rather than using a generic national average. Run the numbers through multiple calculators to cross-check, and factor in the loan limit for your specific county since that directly affects MIP rates.
Get the Full Details

Common Mistakes When Using FHA Estimators
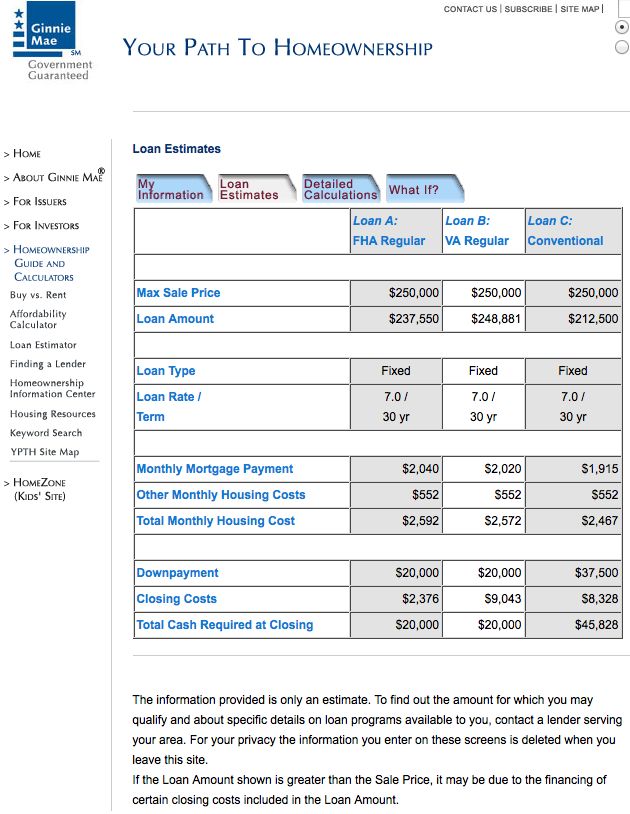
People treat the monthly payment estimate as the total cost of the loan. It is not. The estimator does not include closing costs, which for an FHA loan typically run between three and five percent of the purchase price. It also does not account for the funding fee, which is a one-time charge that ranges from one point four five percent to two point seven five percent depending on your down payment and whether this is your first FHA loan. Some estimators let you add these in manually, many do not. Another issue I see constantly is borrowers comparing FHA estimates directly against conventional estimates from different tools without adjusting for the different structures. Conventional loans with less than twenty percent down require private mortgage insurance, which can be removed once you reach twenty percent equity. FHA mortgage insurance has different rules and often costs more over the long run. The monthly payment might look identical on paper for the first few years, but the trajectory diverges significantly after year five or six. I recommend building a side-by-side projection that extends at least through the midpoint of your loan term, not just looking at year one numbers. Estimators also tend to understate the impact of homeowners insurance, especially in areas with high wind or flood risk. A thirty thousand dollar home in a coastal zone can have an annual premium that is three or four times the national average, and that changes your PITI calculation noticeably. Check your actual insurance quote before relying on any online estimate for final decision-making.
The most practical workaround I have found is to take the output from an online estimator and then verify every line item with your actual lender quote within the first week of application. Estimators are fine for screening and narrowing your search. They are not fine for signing documents. I always tell myself and the people I work with to treat an online estimate as a rough draft, not a final document, and to budget at least two business days for your lender to produce a Loan Estimate that matches the numbers closely enough to move forward confidently.