How Accelerator Calculators Actually Work in Practice
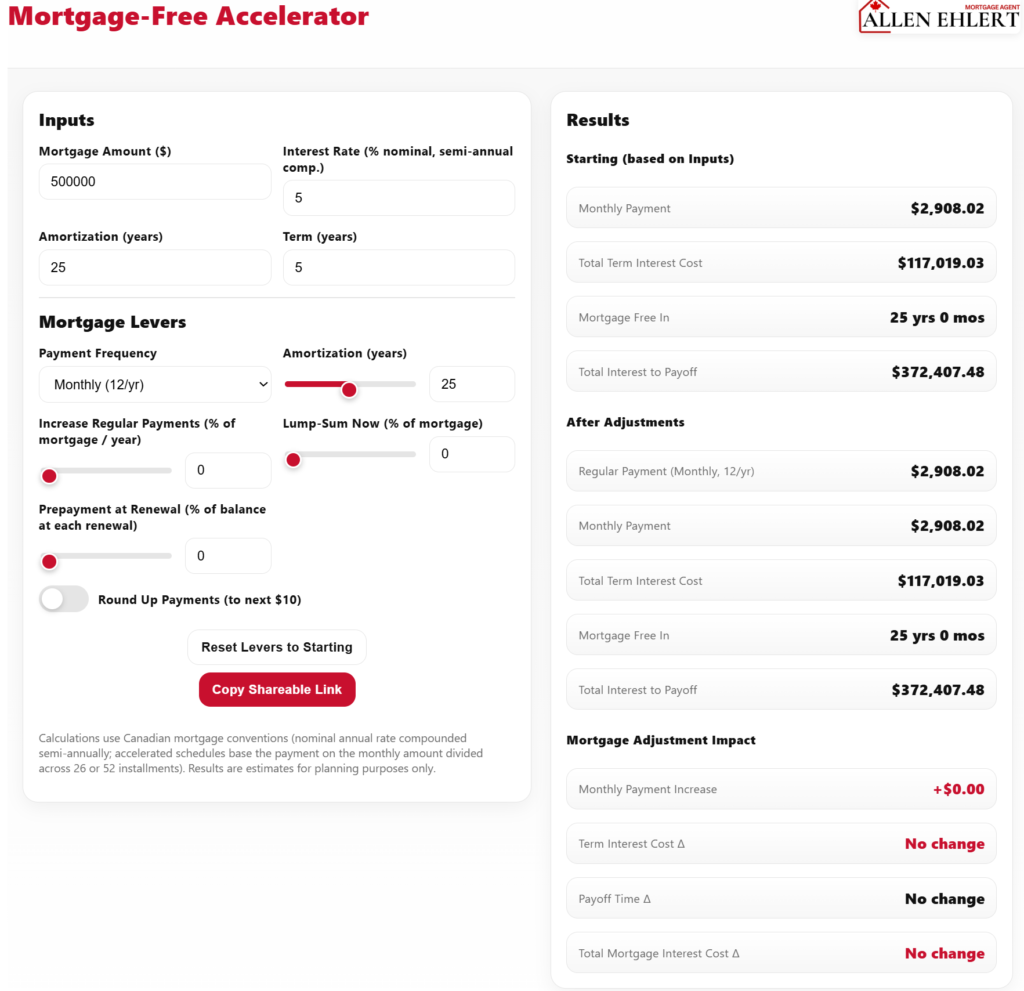
A Mortgage Loan Accelerator Calculator is a tool that shows you what happens when you pay more than the minimum required each month. Not the theoretical scenario from a brochure, but the real numbers after fees, escrow, and the way most servicers actually handle extra principal. I built a few of these for loan officers and walked through enough client portfolios to know where the standard outputs go wrong. The interface usually asks for the loan balance, interest rate, remaining term, and your proposed extra payment amount. Some versions want to know whether you're making biweekly payments, rounding up to the next thousand, or applying a lump sum once a year. The output is a revised amortization schedule. That part is straightforward. Where people get tripped up is in the assumptions behind the numbers. Most free calculators assume your extra payment hits the principal immediately and stays there. Real servicers are slower. There is a processing lag, sometimes two full billing cycles before the additional amount actually reduces your balance. I had a borrower last year who was convinced she had paid down $42,000 in principal based on the calculator output. The servicer's system showed she still owed nearly $58,000 more than the original schedule because her extra payments were sitting in a suspense account for weeks at a time. The fix was simple: I had her call the loan servicing department and request written confirmation that every extra dollar was being applied to principal on the date of receipt, not the date the payment cleared. That changed the projections by over six months off the loan term.
Another thing nobody mentions is how prepayment penalties skew the results. Some loans charge a tapering penalty for the first three to five years, meaning your extra payments in year one cost you more than the interest they save. A proper calculator will flag this, but most generic ones do not. You need to look at your actual promissory note for the prepayment clause before trusting any accelerated payoff figure. The math itself is not complicated. When you add an extra amount to your monthly payment, that amount gets applied entirely to principal after the regular interest is covered. Your new balance is lower, so the next month's interest charge is lower, and the cycle repeats. This is called acceleration, and it is why paying an extra hundred dollars a month on a 30-year loan at 6.5 percent typically shaves about four years off the term and saves roughly $18,000 in total interest over the life of the loan. The exact savings depend on timing and loan size. A $300,000 loan at 6 percent with an extra $200 per month saves about $47,000 in interest and cuts 5.5 years off. The same extra $200 on a $600,000 loan at the same rate saves roughly $72,000 in interest and cuts 4.8 years off. Bigger balance means more interest gets shaved, but the term reduction shrinks slightly because the extra payment represents a smaller percentage of the total obligation.
Biweekly payment structures are a different beast entirely. Instead of twelve monthly payments, you make twenty-six half-payments per year, which equals the equivalent of thirteen full monthly payments. The difference between a biweekly schedule and simply adding half your monthly payment each month is minimal in most cases, but some servicers treat biweekly payments as a separate product and apply different processing rules. I have seen cases where the biweekly option actually performed worse because the servicer rounded partial payments up or down in a way that reduced the principal application. There is also the question of escrow. Your monthly payment includes taxes and insurance, and those amounts can change. If your property tax bill goes up by $200 a year, your total payment goes up, which leaves less room for extra principal unless you adjust the accelerator input. Good calculators let you model escrow changes. Most do not. You should manually subtract expected escrow increases from your extra payment amount to avoid overestimating your acceleration. Here is a practical workflow that actually works instead of relying on a single online tool. Enter your current loan balance, rate, and remaining months into the calculator. Run the baseline scenario first. Then add your proposed extra monthly amount and run the accelerated scenario. Compare the total interest paid and the payoff date. Do this for at least three different extra payment amounts so you can see the effect. The jump from $0 extra to $100 extra saves far more than the jump from $300 extra to $400 extra, because the first $100 hits a larger principal balance each month.
Get the Full Details

One edge case worth knowing: if your loan has a balloon payment or an adjustable rate that resets within the accelerated payoff window, the calculator output becomes meaningless past the reset date. I worked with a borrower who had an ARM that adjusted at year seven. She ran an accelerator calculator and saw a payoff in year nineteen. The actual calculation was irrelevant because the rate reset to 8.2 percent in year seven, which changed her payment and her available cash for acceleration entirely. Always check whether your loan terms extend beyond the calculator's default 30-year projection. Another counter-intuitive point: making a single large lump sum payment early in the loan term is almost always more effective than spreading the same total amount across many small monthly extras. A $10,000 lump sum in month three saves more total interest than adding $278 per month for thirty-six months, even though the total extra paid is the same. The reason is that the lump sum reduces the principal base immediately, and every subsequent interest calculation starts from a lower number. The monthly extra approach reduces principal slowly, so you are still paying interest on a higher balance for longer. I also want to flag a limitation that most calculators ignore completely. If you are in a high-tax state and your mortgage interest deduction is valuable to you, accelerating your payoff reduces your annual interest deductions. For someone in the 35 percent tax bracket paying $18,000 in interest annually, eliminating that interest could cost you $6,300 in additional taxes. The calculator will never tell you this. It only shows interest savings, not tax impact. Run the numbers through a tax professional if this applies to your situation.
Finally, if you are considering refinancing to accelerate payoff instead of just paying extra, the calculator results change dramatically. A lower rate combined with extra payments compounds faster than either strategy alone. I ran a comparison once for a client who had a 6.75 percent loan with ten years remaining. She could either add $300 per month or refinance to 4.5 percent and add $200 per month. The refinance saved her $31,000 more in total interest and paid the loan off two years earlier, despite the closing costs of about $4,200. The break-even on the refinance was fourteen months. That is the kind of detail a basic calculator will not show you. The tools exist and they are useful if you understand what they leave out. Servicing lag, prepayment penalties, escrow drift, tax consequences, and adjustable rate resets are all invisible in a standard output. Factor those in manually and the calculator becomes a genuinely useful planning instrument rather than a source of misplaced confidence.