Building a Mortgage Amortization Calculator That Actually Holds Up
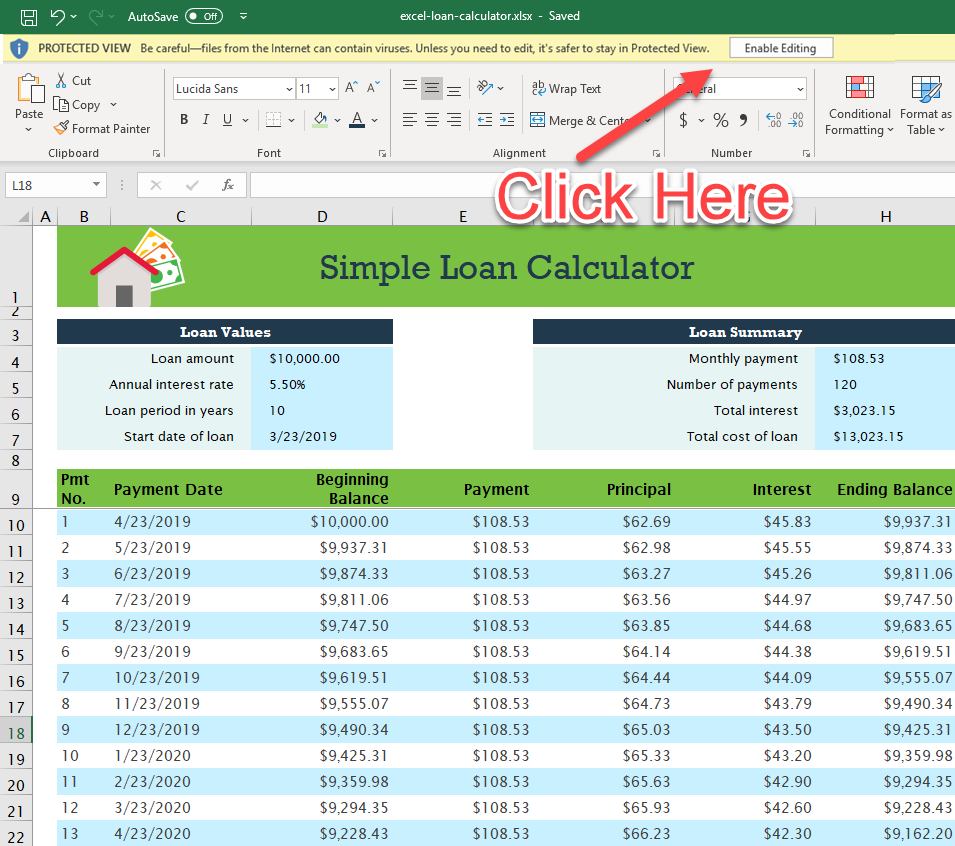
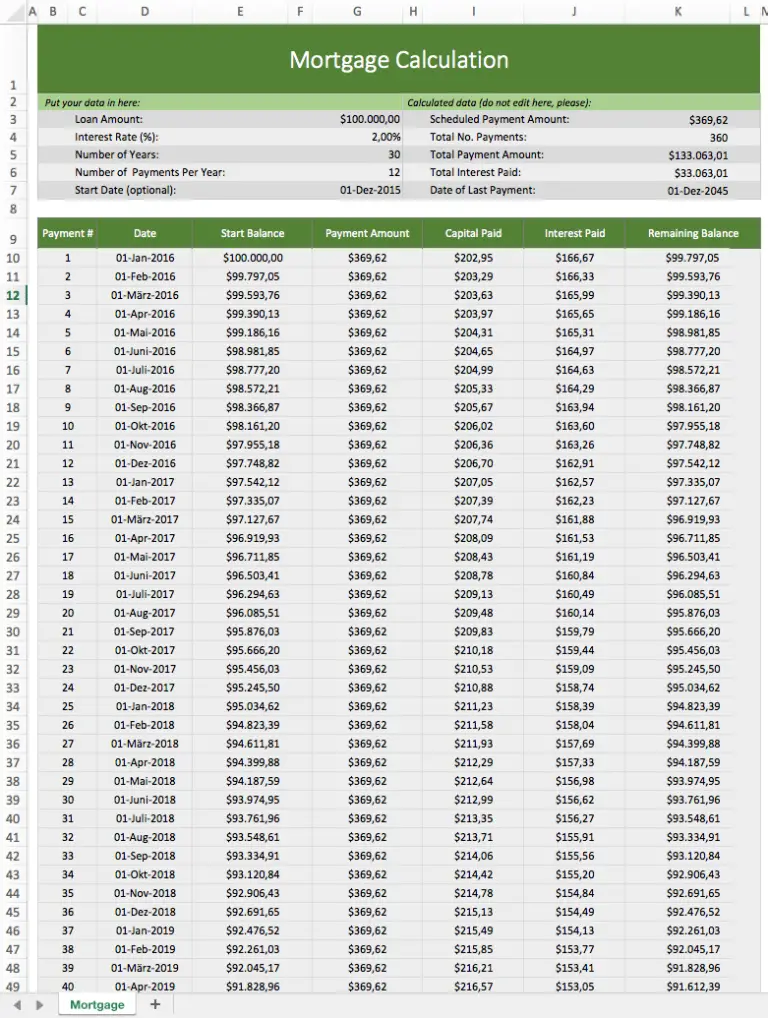
I've spent years maintaining loan schedules for commercial and residential portfolios. Most templates I see floating around are garbage, but the ones that work follow a few strict rules. Here is how I approach it. You need five input cells at minimum: loan amount, annual interest rate, loan term in years, start date, and payment frequency. Everything else is derived. Place your inputs in a locked section at the top so people don't accidentally delete them. I color-code inputs light blue with a border so they stand out from formulas. The payment formula is where most people go wrong. Do not use the generic PMT function alone. Use PMT(rate/periods_per_year, total_periods, -loan_amount). The negative sign on the principal makes the payment display as a positive number, which matters when you are building schedules for borrowers who are already stressed about money.
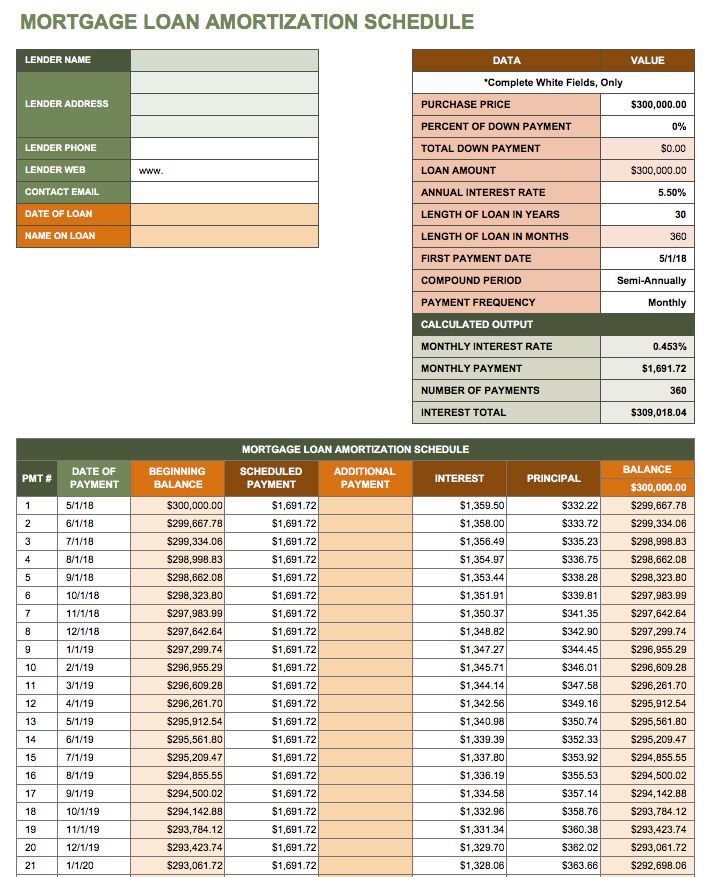
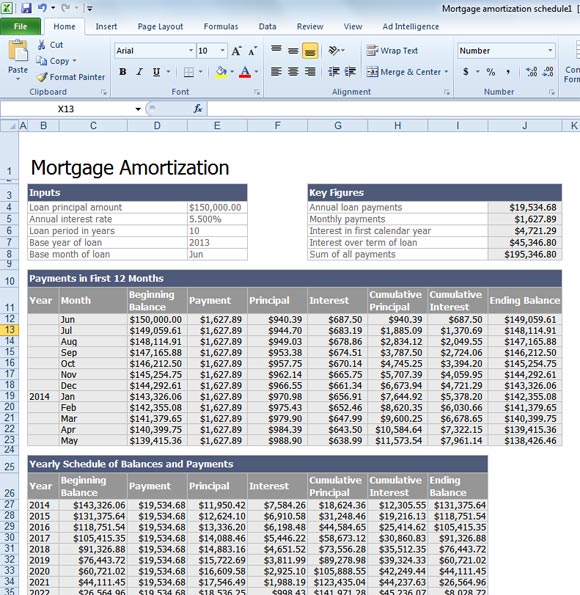
Below your inputs, build the amortization schedule. Column A is the payment number. Column B is the payment date, calculated as =EDATE(start_date, (row_number-1)*(12/periods_per_year)). Column C is the beginning balance. Column D is the payment amount. Columns E and F are principal and interest portions. Column G is the ending balance. This repeats until the balance hits zero.
Interest Calculation: The Trap Most People Miss
Here is something most template creators get wrong. When calculating the interest portion of each payment, do not simply multiply the beginning balance by the annual rate divided by periods. Some lenders use 30/360 day counting conventions while others use actual/365. If you are building this for a real lending scenario, you need to know which convention applies to your specific loan product. Mixing them up will throw off your final payment by a dollar or two, and borrowers notice. I use this formula for the interest portion in a standard 30/360 environment: =BEGINNING_BALANCE*(ANNUAL_RATE/12). For the principal portion: =PAYMENT-INTEREST_PORTION. The ending balance is simply =BEGINNING_BALANCE-PRINCIPAL_PORTION.
Get the Full Details
Edge Case: Prepayment and Partial Periods
A while back I was working on a template for a loan modification scenario where the borrower wanted to make extra principal payments irregularly. Standard amortization tables do not handle this cleanly because every formula assumes a fixed payment. The schedule breaks when you introduce ad-hoc prepayments mid-term. The workaround I ended up using was adding a separate section above the main schedule for additional principal payments. Each row in that section captures the payment date, the extra amount, and a running adjustment to the remaining balance. I then linked the beginning balance of the first period of the amortization table to pull from whichever section had the most recent adjustment. It added about twenty rows to the template but it handled everything cleanly without breaking the core formulas.
What Your Mortgage Loan Excel Template Should Include
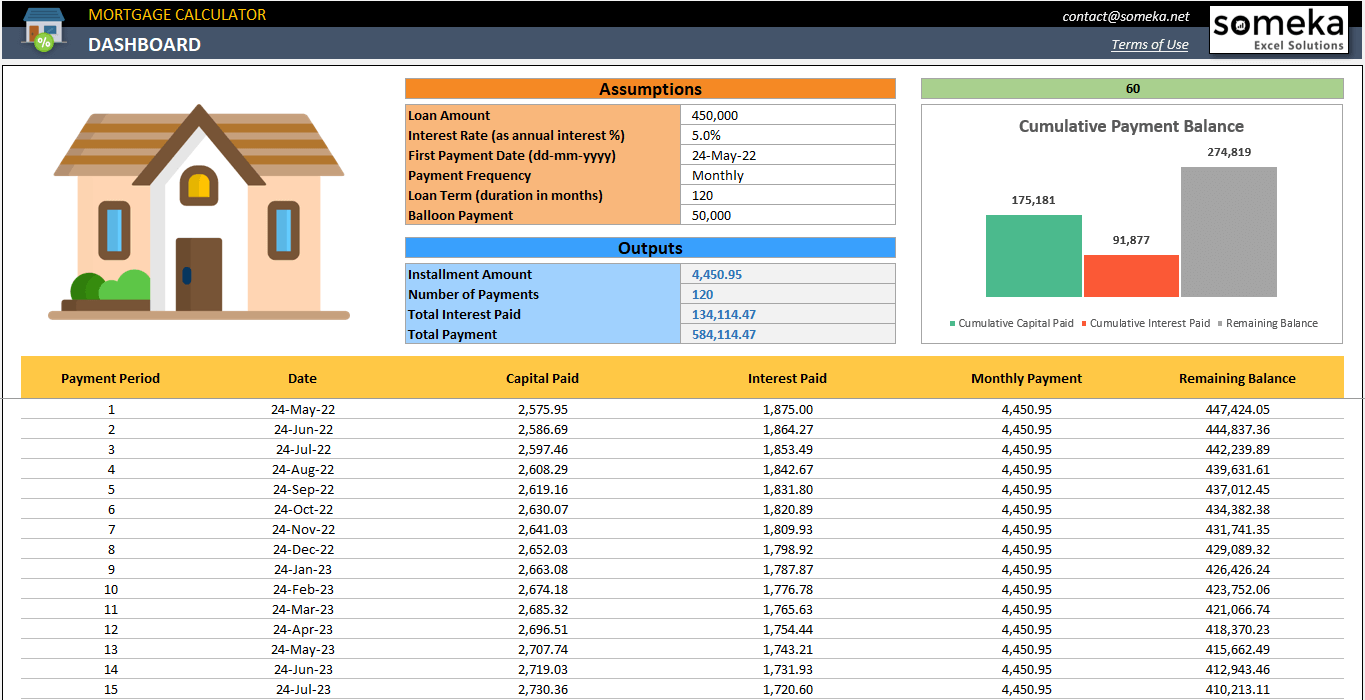
Beyond the basic schedule, any useful template needs these elements. A summary dashboard showing total interest paid over the life of the loan, monthly payment breakdown, and remaining balance at any given point. A principal vs interest pie chart is nice for presentations but practically useless for actual underwriting decisions. Skip the chart unless your audience is non-financial. You also need a refund schedule section for scenarios where the loan is paid off early. Most people do not account for this. If the borrower refinances or sells, you need to show exactly how much interest they saved versus how much they still owed. This is where the template earns its keep. Include a tax interest summary if the loan is for a residential property in the United States. Lenders require this for annual borrower statements. A simple SUMIF pulling all interest payments for a given tax year does the job. Formula: =SUMIF(date_range,">=1/1/2024",interest_column) repeated for each year.
Common Pitfalls
The most common mistake I see is not locking the interest rate input cell. Someone changes a cell reference thinking it is data and the entire schedule shifts. Always protect your input section. Select the input cells, right-click, format cells, protect tab, check locked, then protect the sheet with a password. Simple but effective. Another issue is rounding. Excel displays two decimal places but stores the full precision internally. Your ending balance may never hit exactly zero because of accumulated rounding differences. Add a rounding function to your final payment row: =ROUND(remaining_balance, 2). This adjusts the last payment slightly to close the loop.

Limitations
Excel-based mortgage templates are fundamentally limited when you deal with variable-rate loans, adjustable-rate mortgages, or loans with balloon payments. The formulas become fragile fast. For fixed-rate conventional loans under four hundred thousand dollars, a well-built template works fine. Beyond that, or for portfolio-level analysis across dozens of loans, you should be using dedicated loan servicing software or at least a database backend. Excel will slow down and become unreliable once you exceed a few dozen loan schedules in a single workbook. I recommend keeping your template simple and modular. Build one clean schedule per loan rather than cramming multiple loans into a single sheet. It makes error-checking faster and the formulas easier to audit when something goes sideways.