What Actually Gets You Approved for a Mortgage
Most people walking into a mortgage application have no idea what they're actually being measured against. The mortgage loan qualification process is not a single test with a clear pass or fail line. It is a bundle of overlapping criteria that different lenders weigh differently depending on their risk appetite and the current state of their portfolio. I spent years watching good borrowers get tripped up by things they never saw coming, and honestly, most of those problems are preventable if you understand what is happening behind the scenes. Let me walk through how this actually works in practice, not the version they put on a brochure.
Understanding Mortgage Loan Qualification Requirements
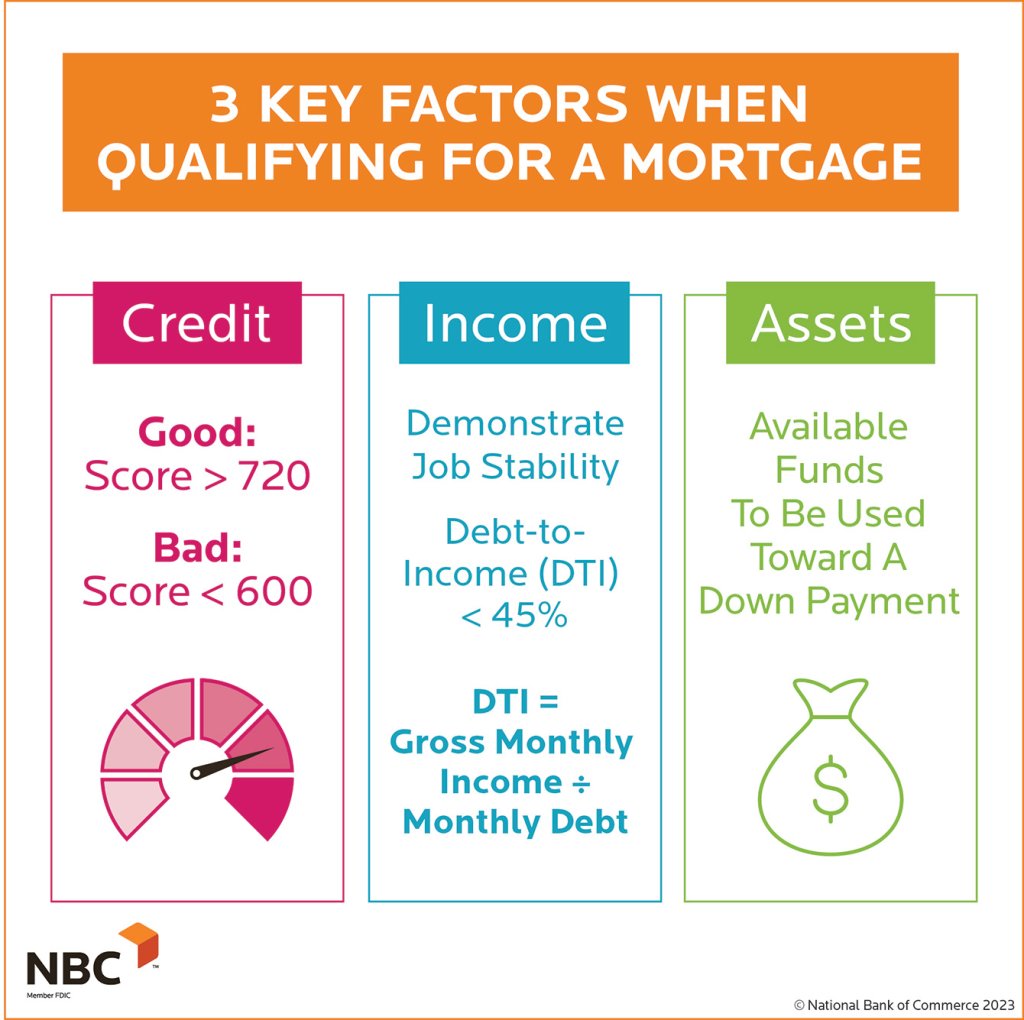
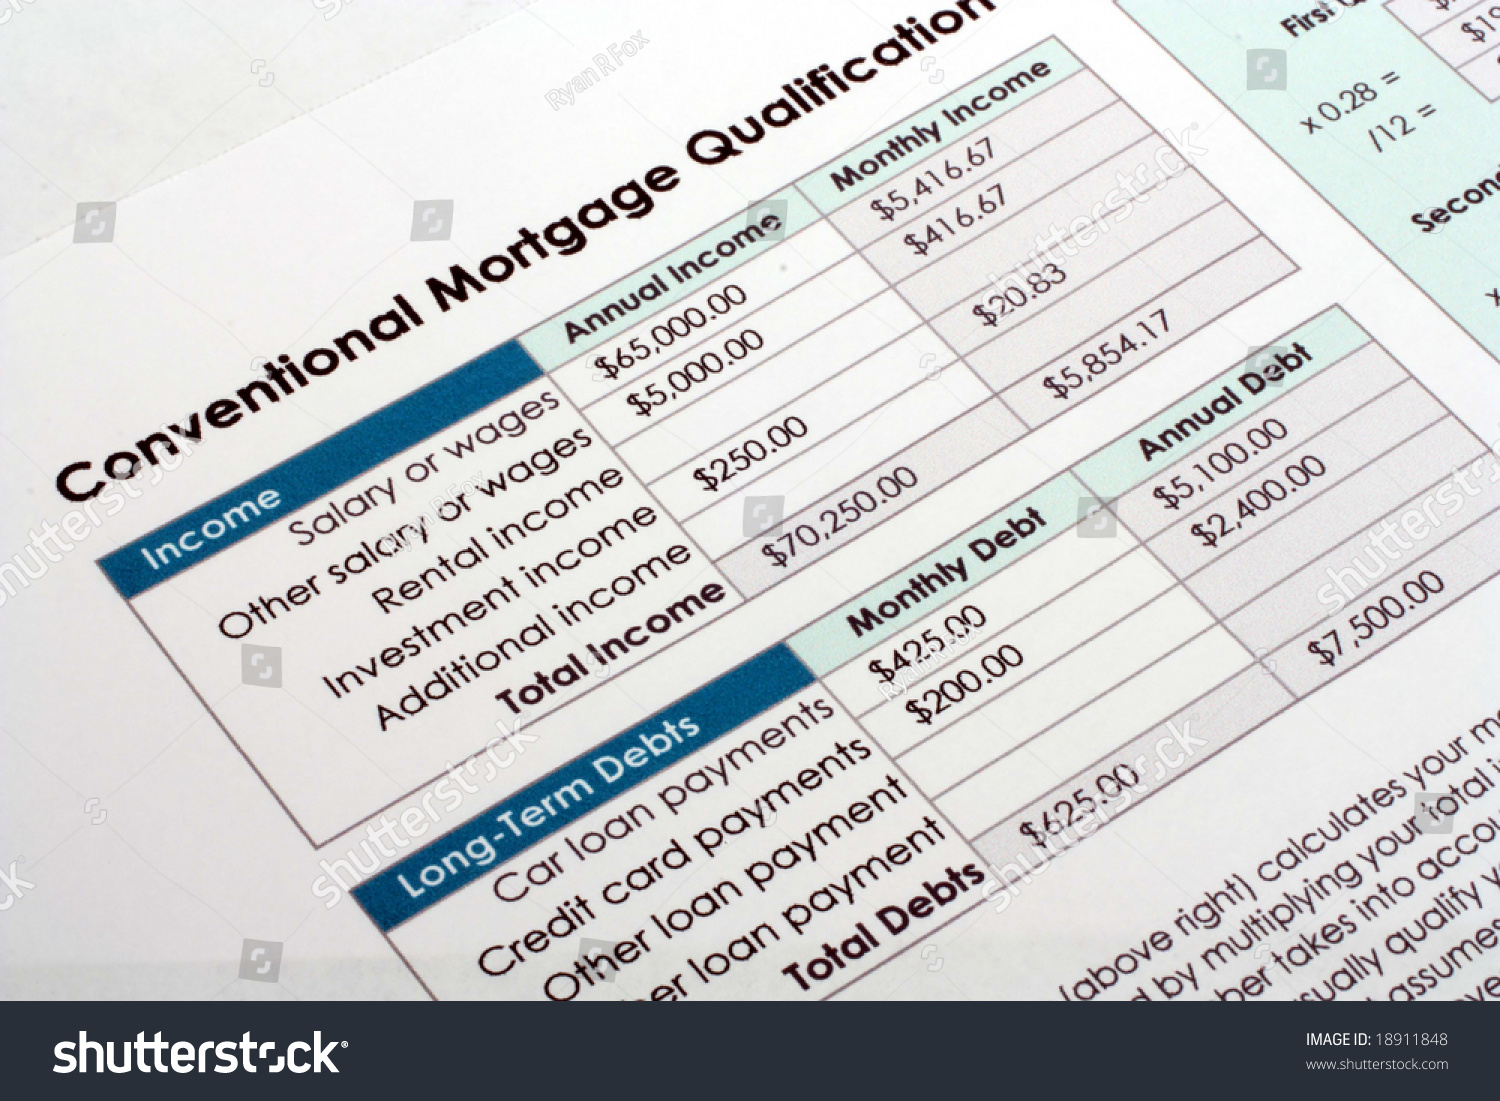
There are four main pillars that any lender looks at, and they all feed into each other in ways that are not always obvious. Credit score is the first thing people think about, but it is also the most misunderstood. A 680 score will get you approved in most cases, but the rate you're offered and the amount you can qualify for will shift significantly depending on where you sit between 660 and 740. That 740 mark matters because it is where most automated underwriting systems stop applying risk-based pricing adjustments. Going from 739 to 741 can literally save you thousands over the life of the loan, and it sounds ridiculous but it is a real thing that happens on every single loan file. The second pillar is debt-to-income ratio, commonly called DTI. This is where most people hit walls. Your DTI is calculated by taking your total monthly debt obligations and dividing them by your gross monthly income. Front-end DTI looks only at housing costs. Back-end DTI includes everything else. Most conventional loans want a back-end DTI below 43 percent, though some programs go higher with compensating factors. The tricky part is what counts as a debt obligation. Car payments, student loans, minimum credit card payments, child support, alimony — all of it gets pulled from your credit report and folded into that calculation. People routinely get shocked when they learn their credit card balances are showing up as monthly obligations even if they pay them off in full every month. The third pillar is employment and income stability. Lenders want to see two years of consistent employment history in the same general field. If you switched jobs recently, that is not automatically disqualifying, but it does add friction. Self-employed borrowers face a completely different set of hurdles because you cannot rely on a pay stub. You need two years of tax returns, and the income that shows on those returns needs to be sufficient. I have seen people make solid money but get denied because their business expenses brought their net income down on paper, even though their actual cash flow was healthy enough to cover the mortgage payment. That disconnect between tax income and real income is one of the most common problems I dealt with.
The fourth pillar is the property itself. Lenders need the home to appraise at or above the purchase price, and it needs to meet certain habitability standards. A roof with visible damage, active water intrusion, or structural issues can kill a deal regardless of how qualified the borrower is. Appraisals are not opinions. They are comparables-based valuations, and if comparable sales in the area do not support the contract price, you are either bringing more cash to the table or renegotiating.
Get the Full Details

How the Application Process Actually Unfolds
Here is the sequence most people don't know about. You submit a loan application, and within 72 hours you are legally required to receive a Loan Estimate document. This is not the same thing as pre-approval. A Loan Estimate comes after a formal application with verified income, assets, credit, and property details. Pre-approval is a lighter preliminary check that gives you some credibility with sellers but means very little once you start shopping around. After you receive the Loan Estimate, the lender orders the appraisal and pulls a second credit report to check for changes. This is where things can fall apart unexpectedly. If you open a new credit card, finance a car, or add any new debt between the initial application and the underwriting stage, your approval can be revoked or delayed. I had a borrower who was two days from closing when she bought a used car to replace her leaking transmission. The new auto loan added $450 a month to her DTI and pushed her over the limit. She had to delay closing by three weeks and re-underwrite the entire file. The loan was ultimately approved, but the interest rate locked had expired and her costs went up significantly. Once the underwriter reviews everything, you will either get a clear to close or a list of conditions that need to be satisfied. Conditions can be simple documentation requests or more complex issues like explaining the source of a large deposit. That last one is critical. Lenders need to verify the source of any deposits over a certain threshold, usually 50 percent of your monthly income, because they need to ensure the money is yours and not a secret loan that would inflate your DTI. Gift funds from family are acceptable but require a gift letter and a paper trail showing the money moved from the donor's account to yours. I spent an entire weekend tracking down a paper trail for a borrower whose father had wired money through a foreign bank account. The funds were legitimate, but the documentation gap almost cost him the deal.
Mortgage Loan Qualification: Common Pitfalls and What to Avoid
There are several mistakes people make repeatedly, and most of them are self-inflicted. The biggest one is making financial changes during the application process without telling your lender. This includes paying off credit cards, opening new accounts, changing jobs, or making large deposits. Some of these changes might seem like they will help you qualify better, but they often create new problems that slow everything down. Another common mistake is misunderstanding how different loan programs count income. Government-backed loans like FHA and VA have more flexible underwriting standards, which can be a lifesaver if you have a bumpy credit history or a higher DTI. But they come with their own requirements, like mortgage insurance premiums that can be surprisingly expensive over time. Conventional loans with private mortgage insurance are cheaper if your down payment is 20 percent or more, but getting that 20 percent upfront is the actual challenge most people face. The third mistake is assuming the lowest advertised rate is the rate you will actually get. Lenders advertise the best rate they can offer to the most qualified borrowers with the largest down payments in the strongest markets. Your rate will be different, sometimes significantly so. The real number you should be comparing is the annual percentage rate, or APR, which includes fees and other costs bundled into the loan. Two loans with the same interest rate can have very different APRs depending on how the lender structures the fees.
One of the least understood aspects of mortgage qualification is how your assets are evaluated beyond just the down payment. Lenders want to see that you have reserves remaining after closing. Reserves are the money left in your accounts after you pay for the down payment, closing costs, and prepaid items. Most lenders want you to have three to six months of mortgage payments in reserve, and they calculate this differently than you might expect. They look at your principal and interest payment plus property taxes, homeowners insurance, and HOA fees combined, then multiply by the number of months they require. If your total monthly housing payment is $2,500 and they want six months of reserves, you need $15,000 sitting in qualifying accounts after closing. That requirement varies by loan program and how many properties you already own, but it is a constraint that catches a lot of people off guard.

What Doesn't Work and When to Try Something Else
The conventional automated underwriting system, commonly called Desktop Underwriter, is fast and efficient for straightforward cases. But it is rigid. If your situation has any deviation from the standard profile, the system will flag it and send your file to manual underwriting, which takes longer and often requires more documentation. This includes self-employment income, non-traditional credit histories, unusual asset situations, and properties in non-standard conditions. If you find yourself in one of those categories, the automated route may not be your best option. A manual underwriter has more flexibility to consider compensating factors that a computer system cannot evaluate. For example, if your credit score is slightly below the ideal range but you have a strong employment history, significant reserves, and a low DTI, a human underwriter may approve you while the automated system declines. I have seen this happen repeatedly, especially with borrowers who are otherwise very qualified but have a single derogatory event on their credit report that automated systems treat as a hard stop. Another scenario where the standard path fails is seasonal or commission-based income. If your income fluctuates significantly month to month, averaging your earnings over the past two years may make your income look lower than what you actually bring in now. Some lenders will allow you to use year-to-date income projections instead, but not all of them do, and the ones that do tend to be less common. Shopping around for a lender willing to work with your specific income structure is something most people do not think to do until they have already been declined.
There is also the question of which loan type makes sense for your situation. FHA loans are accessible with lower credit scores and smaller down payments, but the mortgage insurance costs can be substantial and may last for the entire life of the loan if you put less than 10 percent down. Conventional loans are generally cheaper overall if you can meet the qualification thresholds. VA loans offer zero down payment and no mortgage insurance for eligible veterans, but the funding fee can be steep depending on your service history and down payment amount. Each program has trade-offs that are not always obvious from the marketing materials. The practical takeaway is that mortgage qualification is not a puzzle with one correct solution. It is a set of constraints you need to navigate, and the constraints shift depending on where you apply, what loan program you choose, and how your financial situation is structured. Getting pre-approved before you start house hunting gives you a realistic sense of your budget, but treat that number as a starting point rather than a guarantee. Things change between pre-approval and closing, and the people who lose deals are usually the ones who assumed nothing would change. If you are working with a lender and something shifts in your financial life, tell them immediately. Waiting until the last minute to disclose a job change, a new debt, or a large deposit is the fastest way to derail a transaction that was otherwise on track. Transparency is not optional in this process. It is the difference between a smooth closing and a week of panic and last-minute scrambling.