What a Mortgage Loan To Value Calculator Actually Does
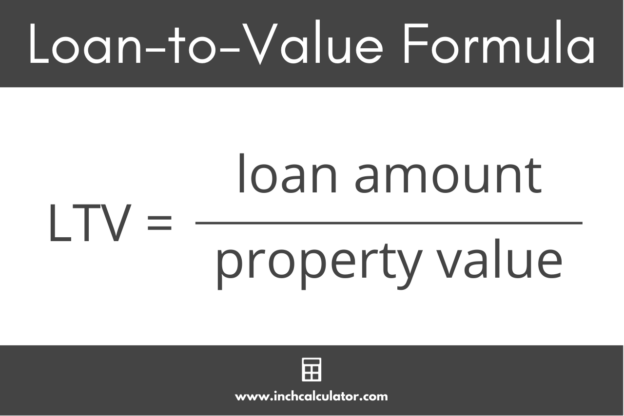
A Mortgage Loan To Value Calculator takes two numbers—your loan amount and your property value—and spits out a percentage. That percentage is the LTV ratio, and it matters more than most people realize when you're sitting across from a lender. I've seen borrowers walk away with better rates because they knew their LTV before the appointment. I've also seen them lose deals because they estimated wrong and got to the table unprepared. The math itself is trivial. Divide the loan amount by the appraised or agreed property value, then multiply by 100. That's it. But the implications behind that single number are where things get complicated, and where most guides stop being useful.
How to Use a Mortgage Loan To Value Calculator
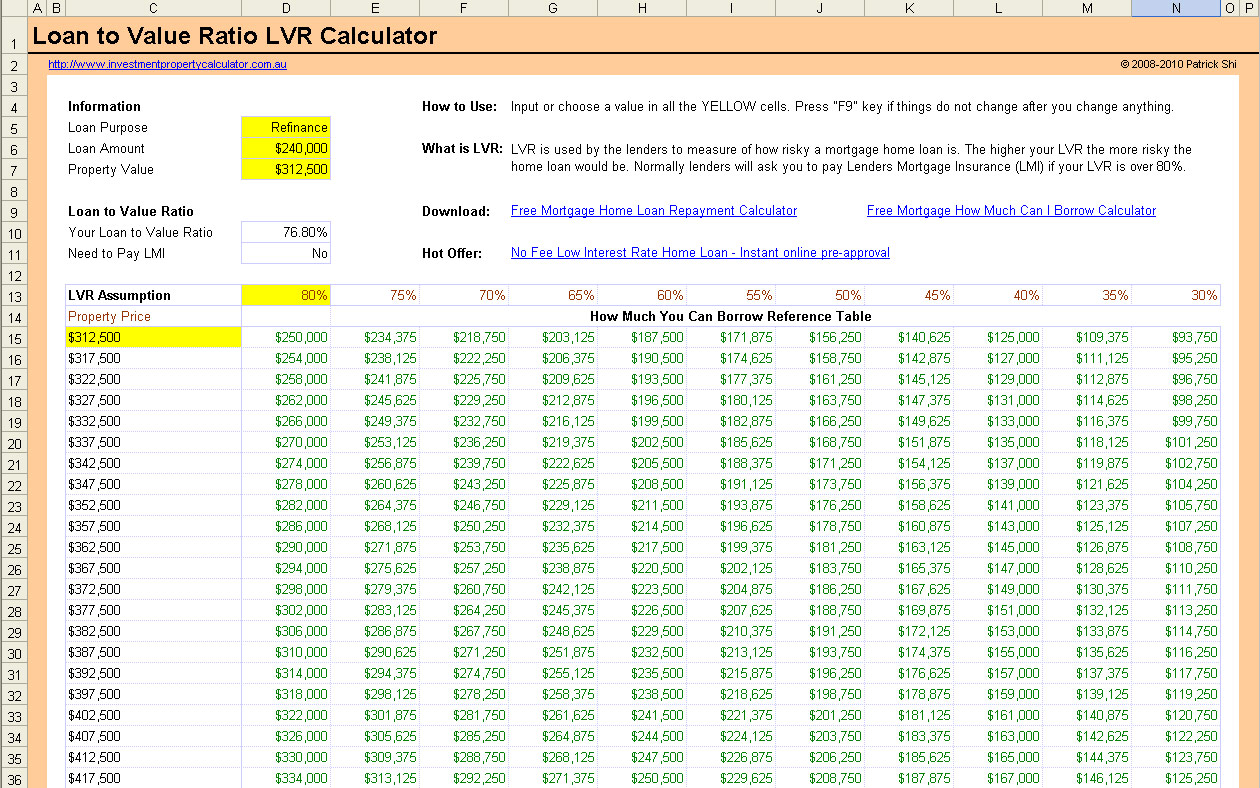
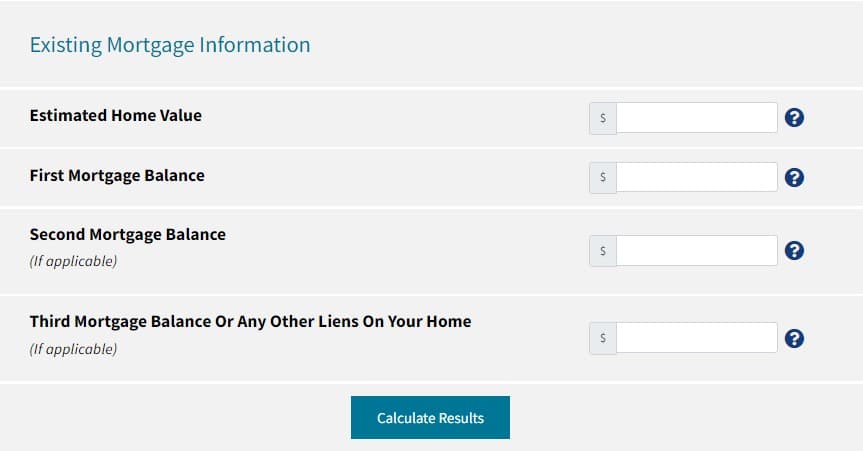
Here's the straightforward part. Open any basic LTV calculator tool online, enter the purchase price or appraised value of the property, then enter the mortgage amount you're seeking. The calculator returns the LTV ratio. If you already know your down payment, you can work backwards: take the down payment percentage, subtract it from 100, and that's your LTV. A 20 percent down payment means an 80 LTV ratio. A 5 percent down payment means 95 LTV. The relationship is linear and consistent. I keep a simple spreadsheet on my desk for quick reference. It calculates LTV from any combination of price, loan amount, or down payment percentage. Takes about three seconds. Most web-based Mortgage Loan To Value Calculator tools do the same thing in real time, though some of them have clunky interfaces that add unnecessary friction. I recommend finding one that lets you adjust both inputs simultaneously rather than recalculating after every keystroke. It saves minutes over the course of a real shopping process.
Where LTV Actually Matters in a Mortgage Deal
LTV isn't just a number for the application form. It determines whether you pay private mortgage insurance, what interest rate tier you qualify for, and whether the lender will even approve the file in the first place. Most conventional loans cap out at 97 LTV without PMIs. Above 80 LTV and PMI becomes mandatory on standard conforming loans. Jumbo loans often require 80 LTV or lower regardless of other factors. FHA loans go to 96.5 LTV with mortgage insurance. Each program draws the line at different thresholds. Rate adjustments tied to LTV are real and significant. Moving from an 85 LTV to a 75 LTV can drop your rate by a quarter point or more, sometimes a full half-point depending on the market. The difference compounds over the life of the loan. On a $400,000 mortgage over 30 years, a 0.25 percent rate difference is roughly $14,000 to $16,000 in total interest paid. That's not theoretical. That's actual money staying in your pocket or going to the lender. One thing nobody emphasizes enough: LTV is calculated at origination, but it changes as you pay down the principal and as the property value fluctuates. Your LTV at closing might be 88. But five years later, if you've paid down enough principal and the market held steady, you could be at 75 or lower without putting another dollar in. That shift matters for refinancing decisions. I had a client who refinanced at year four when his LTV dropped below 80 and cancelled his PMI. Saved him about $200 a month on insurance alone. The refinance closing costs paid for themselves in under eight months.
Get the Full Details
A Real Problem I Ran Into With LTV Calculations
Early in my career I dealt with a VA loan scenario where the LTV calculation wasn't straightforward. The property had just been through a major renovation, and the appraised value came in significantly higher than the contract price. The borrower wanted to finance the full purchase price plus renovation costs rolled into the loan. The LTV calculator output looked fine on paper—around 82 percent—but the underwriter flagged it because the combined loan amount exceeded the appraised value when you accounted for the seller's concessions and closing cost credits. The workaround was to recalculate LTV using the lesser of the purchase price or the appraised value as the denominator, which is actually the correct approach per investor guidelines. Most basic calculators don't account for this distinction. They just divide total loan amount by purchase price and call it a day. The fix involved running the numbers through the manual underwriting overlay matrix, breaking out the renovation funds from the base loan, and presenting the lender with a split-LTV analysis showing the base loan at 78 percent and the renovation portion at a separate tier. It added about forty-five minutes of work but prevented the file from getting bounced at secondary review. Since then, I always run LTV through a manual verification step before submitting anything with concessions or rolled-in costs.
Common Pitfalls That Break LTV Calculations
The biggest mistake people make is using the listing price instead of the actual appraised value or purchase price. If the house is listed at $500,000 but sells for $475,000, your LTV should be based on $475,000, not $500,000. Using the higher number makes your LTV look worse than it actually is. The second mistake is ignoring closing costs and prepaid items when calculating total loan amount. Some loans allow you to finance certain closing costs, and those counts toward the total debt. If you exclude them, your LTV is understated, and you might miss the PMI threshold entirely. A third error involves multiple loans on a single property. A first lien at $320,000 and a second lien at $80,000 on a $400,000 home doesn't give you two separate LTV ratios to consider. The combined LTV is 100 percent, and that's what determines your rate and eligibility. Separate LTVs might look manageable in isolation. Combined LTV is what the lender cares about for risk assessment. I've seen borrowers get surprised by this exact issue when they thought they qualified for a better rate based on the first lien ratio alone.
When an LTV Calculator Won't Help You
Online Mortgage Loan To Value Calculator tools are fine for estimates. They are not substitutes for a proper underwriting analysis. Several scenarios fall outside what a simple calculator can handle accurately. Self-employed borrowers with non-standard income documentation often face manual LTV adjustments by underwriters regardless of what the calculator shows. Investment properties use different LTV caps than primary residences even when the numbers look identical. Condominiums in buildings that haven't been approved by Fannie Mae or Freddie Mac face restrictions that have nothing to do with the LTV ratio itself. A calculator cannot account for these program-specific overlays. There's also the issue of portfolio lenders versus automated underwriting. A portfolio lender might accept a 90 LTV on a conventional loan if your credit profile is strong and your reserves are solid. An automated system running Fannie Mae guidelines might reject that same file outright. The calculator gives you the same percentage either way, but the outcome diverges significantly. This is one reason why running numbers through just a calculator and then walking into a bank can produce disappointing results. The machine approval and the human underwriter see the same LTV but weigh it differently.
Practical Steps to Get an Accurate LTV Before You Apply
Start by pulling a recent comparable sales report for your target property. Even a rough estimate from three nearby sales within the last ninety days is better than guessing. Enter that estimated value into your calculator along with your intended loan amount. Then add a five to ten percent buffer for appreciation or depreciation depending on your local market direction. If you're in a hot market, assume values could be 5 to 8 percent higher than what comparable sales suggest. In a cooling market, assume the opposite. This buffer prevents you from planning around a number that might shift before closing. Once you have your working LTV, check the PMI threshold for your specific loan program and lender. Many lenders require cancellation eligibility at 78 percent automatically, but some hold onto it longer. Knowing your path to PMI removal helps you plan payoff strategy. If your LTV is above 80 and you're shopping rates, consider making a larger down payment to cross that 80 percent line. The rate savings typically outweigh the opportunity cost of tying up extra cash, especially if you plan to stay in the property for more than three years. I run a quick breakeven analysis every time a client is considering this tradeoff. It usually takes two minutes and clarifies the decision immediately.