Getting a Mortgage on a 650K Property: What Actually Happens
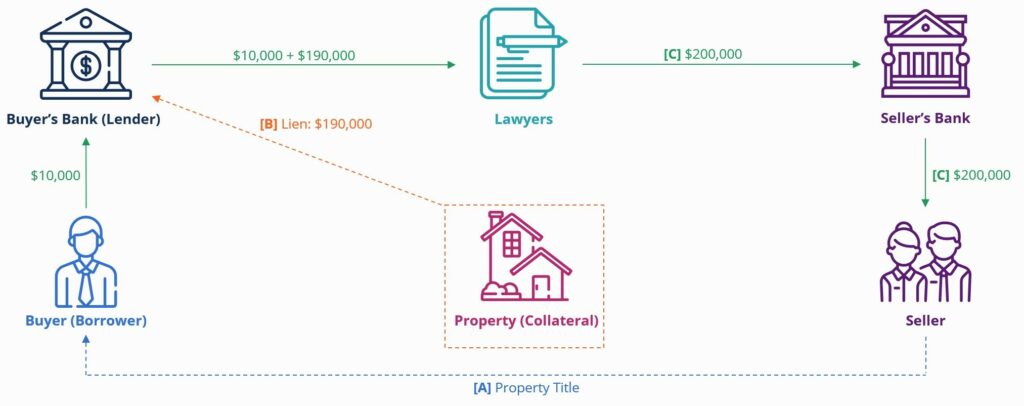
I need to clarify something right away because people confuse this constantly. When you see Mortgage On 650K, you're looking at a loan for a property appraised or purchased at six hundred fifty thousand dollars. That's it. There's no special program attached to that price point. The mechanics are the same as any conventional mortgage, just with larger numbers and slightly tighter scrutiny from lenders who see high-balance applications flood their queues every month. The down payment question is where most first-time buyers at this price level stall out. With a 650K home and a conventional loan, you're typically looking at a minimum of 5 percent down if your credit is solid. That puts you at roughly $32,500 out of pocket before closing costs. Most people I work with plan for between 10 and 20 percent though, which means budgeting somewhere between $65,000 and $130,000 for the down payment alone. It's not optional to underestimate this. I had a client last year who showed up with 8 percent and thought they were cleared. The appraisal came in two percent low, which shifted everything, and we had to renegotiate the terms before the file could even restart processing. She ended up covering the gap with a piggyback second, but it cost her an extra point in fees and added three weeks to closing.
Understanding Mortgage On 650K Loan Options
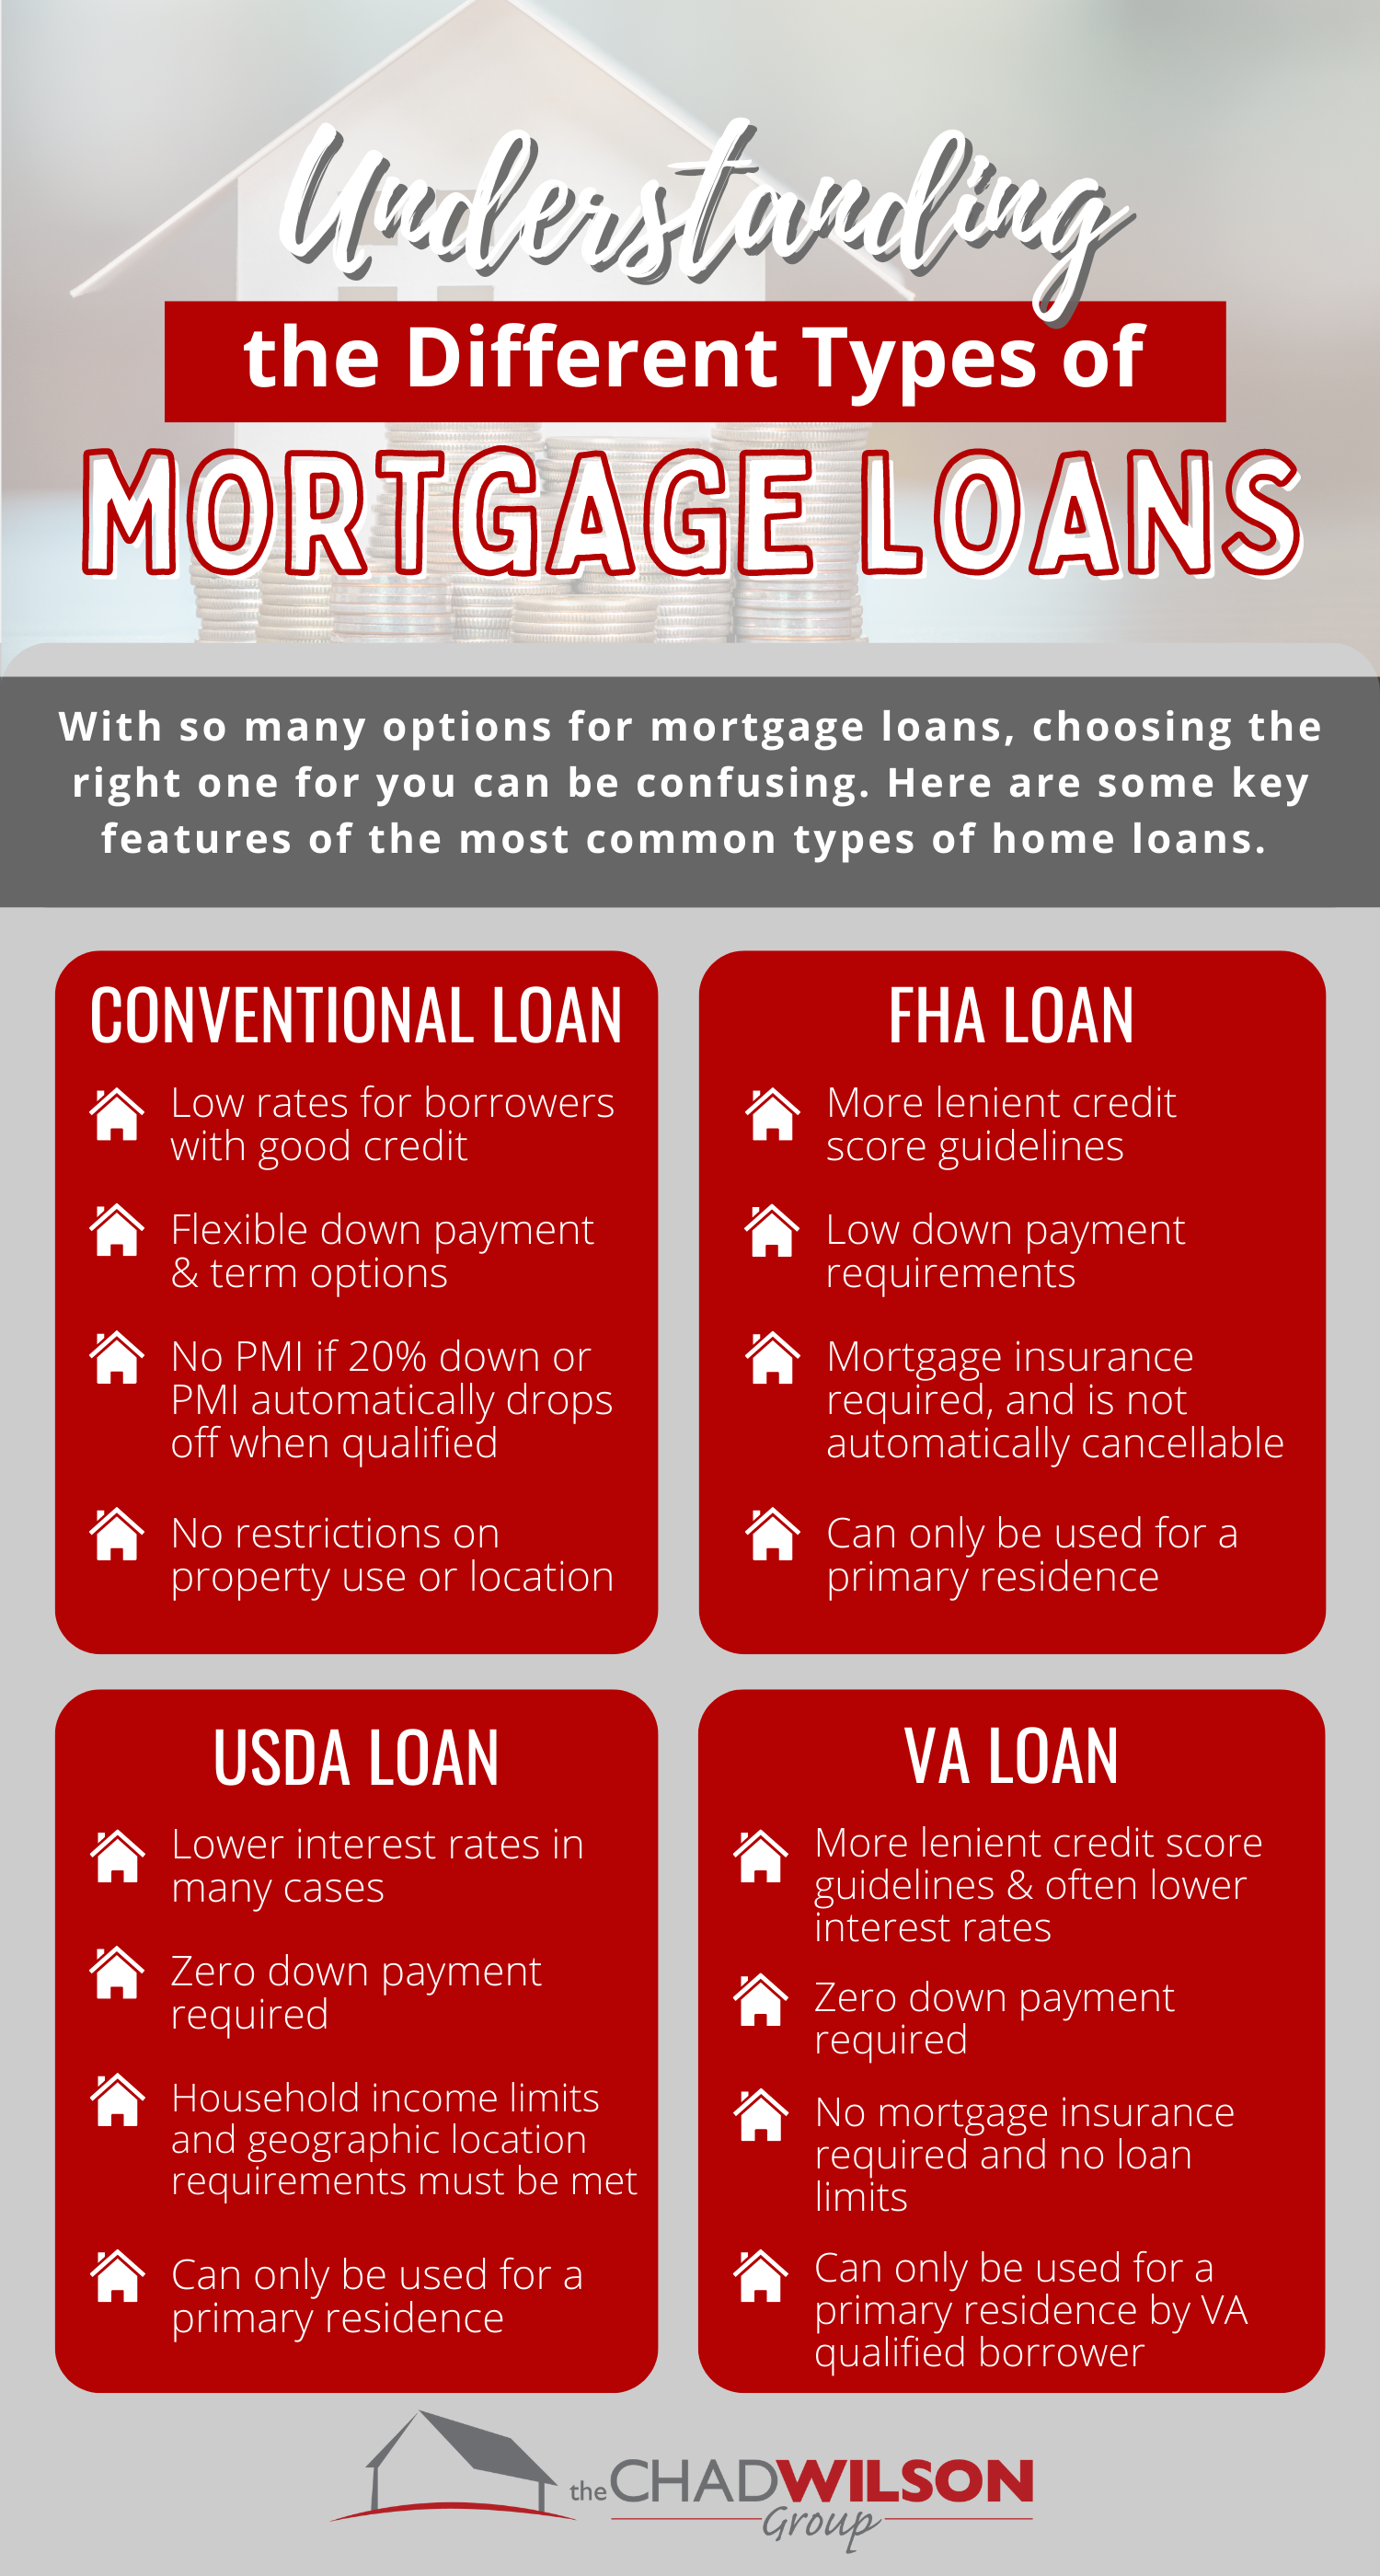
Conventional loans dominate at this price range, but there are nuances most guides skip. Jumbo loans kick in once you exceed the conforming loan limit, which as of 2024 sits at $766,550 for most areas and $1,149,825 in high-cost counties. If you're in a standard metro area, a 650K mortgage likely stays within conforming limits and you get better rates. A 97.5 percent LTV product exists for certain credit profiles, but it requires private mortgage insurance and the rate premium on that structure is significant enough that some buyers are better off putting 10 or 15 percent down and skipping PMI entirely. The math works out in your favor pretty quickly if you hold the loan for more than three years. FHA loans are technically available at 650K, but they carry upfront and annual mortgage insurance premiums that scale with the loan amount. On a $650,000 purchase with 3.5 percent down, you're looking at roughly $4,550 in upfront MIP rolled into the loan, plus 0.55 percent annually. That adds about $380 a month to your payment compared to a conventional structure. It only makes sense if your credit is below 580 or you have qualifying reasons you can't access conventional financing. Otherwise, it's an expensive detour. VA loans and USDA loans have income and property eligibility restrictions that disqualify a lot of buyers at this price point. VA funding fees are reasonable, and there's no PMI, but the property value limits for USDA can exclude a lot of homes at 650K depending on the county. Veterans should check their entitlement before assuming eligibility.
The real complication comes from state-specific programs and local first-time buyer assistance. Cities like Austin, Denver, and Portland run their own down payment assistance programs that can stack with conventional loans. These aren't gimmicks. I filed a transaction in King County, Washington where the buyer used a combined grant from the state housing finance authority and a city-level assistance program that covered about 4 percent of the purchase price. The lender required it to be a second lien in a subordinate position, and the appraisal needed to confirm the equity position, but it went through without issue. The key was ordering the appraisal early and making sure the assessor's value aligned with the contract price. Mismatches here delay everything by weeks.
Get the Full Details

How the Application Process Actually Works
Pre-approval at the 650K level takes longer than pre-approvals for smaller loans. Expect 2 to 5 business days if your paperwork is complete. You'll need W-2s from the last two years, year-to-date pay stubs, bank statements for all accounts for the past two to three months, tax returns if you're self-employed, and documentation for any other income like alimony or rental properties. Lenders want to see two full years of tax history for self-employed borrowers because the math doesn't work the same way. Debt-to-income ratio is the gatekeeper. Most conventional lenders cap DTI at 45 to 50 percent, with some exceptions up to 55 percent if your credit score and reserves are strong enough. For a 650K home with a 20 percent down payment, a 30-year fixed at current rates would produce a principal and interest payment around $3,100 to $3,400 per month depending on the exact rate. Add property taxes, homeowners insurance, and HOA fees if applicable, and your total housing expense climbs to somewhere between $4,000 and $4,800 monthly. That means you need a gross monthly income of roughly $8,000 to $10,000 to stay within acceptable DTI thresholds. It's not a hard rule, but it's the threshold where approval becomes straightforward rather than negotiated. Closing costs on a 650K loan typically run between 2 and 5 percent of the purchase price. You're looking at $13,000 to $32,500 depending on location, lender fees, and whether you buy points. Title insurance, appraisal, credit report, processing fees, and origination charges make up the bulk of it. In some states, transfer taxes and recording fees add several thousand more. I've seen close estimates go as high as 6 percent in certain counties with aggressive local transfer taxes, so get a detailed Good Faith Estimate from your lender and compare line items from at least two other lenders before committing. The variance between lenders on the same loan type can be several thousand dollars.
Common Pitfalls That Trip People Up
One thing nobody warns buyers about is the impact of large deposits in the weeks before closing. If you move $20,000 into your checking account two weeks before the application, the underwriter will ask for a paper trail. Source of funds documentation is mandatory. I once watched a borrower lose their rate lock because their sister deposited $15,000 into their account right before underwriting and couldn't produce a gift letter in time. The loan fell apart. Get your money in order before you apply, or expect delays. Appraisal issues are the second biggest problem area. At 650K, appraisers are comparing your property against recent sales in the neighborhood, and if those comparables are weak, your loan could come in short. A low appraisal means the lender won't finance above the appraised value unless you bring additional cash to closing or renegotiate the purchase price. This happens more often than you'd think in markets where prices have risen faster than nearby sales data can catch up. The workaround is simple but unglamorous: request a reappraisal with better comps, or adjust the purchase price. I've also seen buyers use a second appraisal from a different provider when the first one was questionable, though that costs another few hundred dollars and isn't guaranteed to help. Credit score expectations shift at this price point. While 620 is technically the floor for conventional loans, pricing tiers improve significantly at 680 and above. A 740 or higher gets you the best available rate. If your credit sits between 660 and 680, you can still qualify, but expect a rate that's 0.25 to 0.5 percent higher, which translates to hundreds of dollars per month over the life of the loan. Don't open new credit lines before applying. Hard inquiries and new accounts can drop your score just when you need it highest.
When a 650K Mortgage Doesn't Make Sense
Sometimes the numbers don't work and sellers and buyers both know it. If you're putting less than 20 percent down on a 650K home and your DTI is already near the limit, the monthly payment could consume more than half your take-home pay. That's a fragile position. One job loss or unexpected expense and you're underwater financially. I've seen this happen repeatedly in markets where buyers stretch to afford homes they can't sustain. The alternative is either a smaller property, a longer commute to a more affordable area, or waiting to build savings until the math is comfortable. No loan program will fix a payment that's too large for your income. Another scenario where this breaks down is when the property has unique characteristics that make it hard to appraise or finance. Custom homes, properties with unusual square footage, or homes in neighborhoods with few recent sales all create friction. Lenders want to see comparable sales data. If there's nothing recent to support the price, the file stalls. In those cases, cash buyers have a distinct advantage, and financed offers may need creative structuring or a lender willing to underwrite non-standard properties, which usually means higher rates or stricter requirements. The bottom line is that a 650K mortgage operates the same way as any other conventional loan, just with bigger stakes and more consequences when things go wrong. Plan your down payment realistically, shop multiple lenders, understand your total monthly obligations, and don't skip the step of checking local assistance programs. The process is predictable if you prepare properly, and the hardest part is usually making sure the numbers work before you fall in love with a property.