How Overpaying Your Mortgage Actually Works
The standard approach people take is just plugging extra money into their monthly payment and hoping the bank applies it correctly. Most of the time it does, but not always, and that gap between what you expect and what actually happens is where people lose thousands in interest without noticing. I spent years working with mortgage portfolios before moving to the advisory side, and the single most common mistake I see is people assuming their overpayment calculator output translates directly into savings. It doesn't, because lenders calculate interest daily on the remaining balance, and a lot of online tools get the compounding wrong or use simplified amortization schedules that don't match real British or American mortgage structures.
Using a Mortgage Overpayment Calculator Correctly
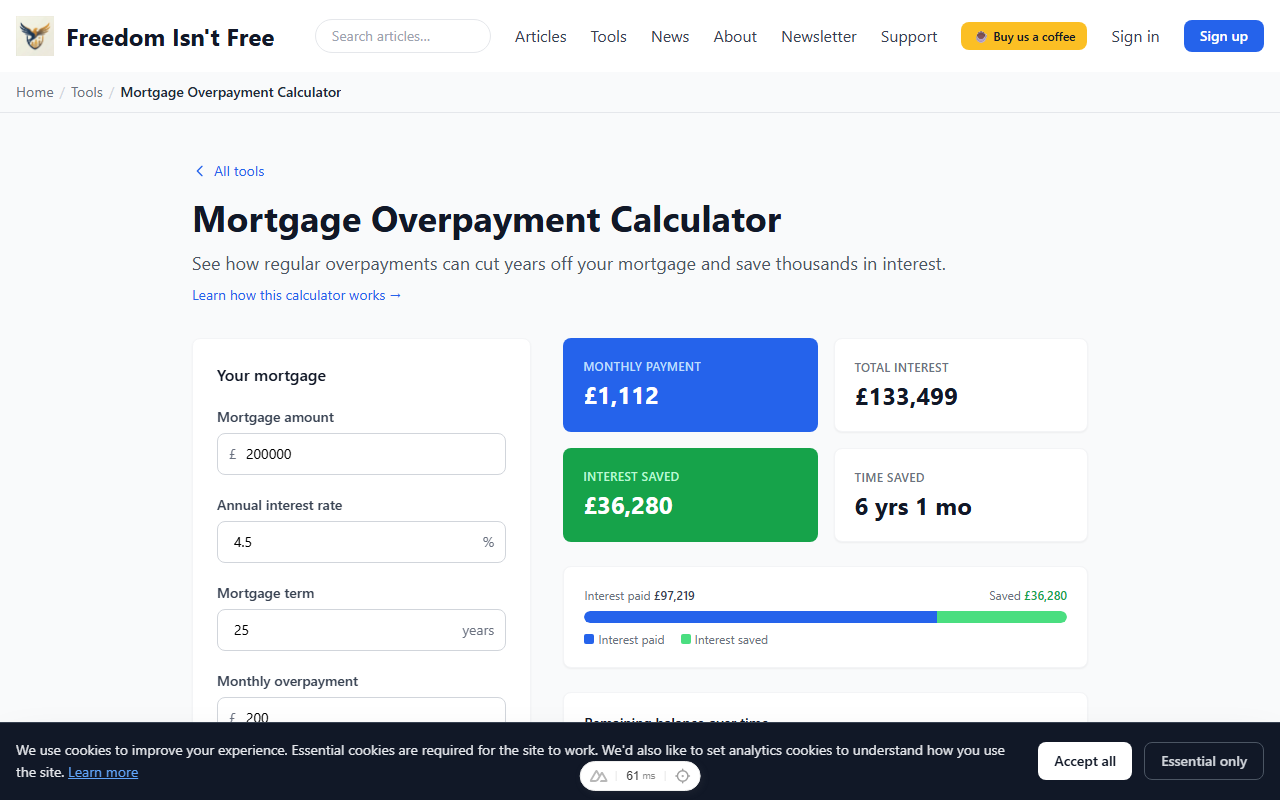
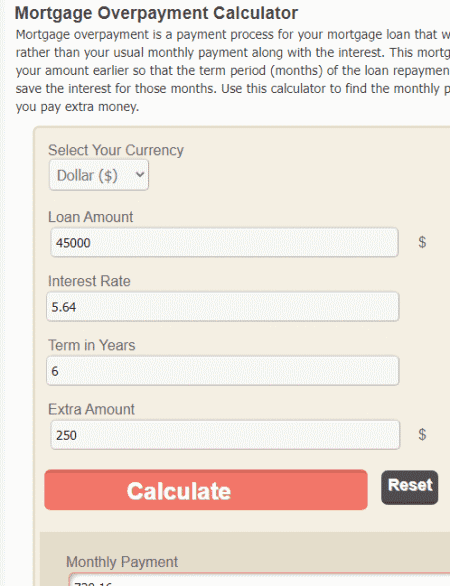
Start by gathering four pieces of information: your current outstanding balance, your remaining term in months, your annual interest rate (not the monthly rate your lender quotes you), and how much extra you're planning to pay each month or as a one-off lump sum. Put those into the calculator, but don't trust the first number it gives you for total interest saved. Here's the part most guides skip. When you make an overpayment, it can be applied in one of two ways depending on your lender: either it reduces your monthly payment amount while keeping the term the same, or it reduces the term while keeping your payment the same. These produce completely different results. The second option almost always saves more interest, sometimes dramatically more, because you're shrinking the principal faster. A good Mortgage Overpayment Calculator will let you choose between these two scenarios. If yours doesn't, you should find one that does or just do the math yourself in a spreadsheet. I learned this the hard way back in 2018. A client came to me with a screenshot from a popular online calculator showing that overpaying £500 a month on his £180,000 mortgage at 3.5% would save him £23,000 in interest. I ran the numbers manually using the actual amortization formula and the real answer was closer to £19,400. The calculator had assumed the overpayment reduced the term, but his lender's policy at the time applied all overpayments to reduce the monthly payment instead. That difference between £19,400 and £23,000 was the gap between a realistic expectation and a misleading one. I made him call his lender and confirm their overpayment treatment policy before he committed to anything.
The Math Behind It
Mortgage interest is typically calculated on a daily basis using the outstanding principal multiplied by the daily interest rate, which is your annual rate divided by 365. Each payment covers the accrued interest for that period first, and whatever's left goes toward reducing the principal. When you overpay, that extra money hits the principal directly, so future daily interest calculations start from a lower base. The formula itself isn't complicated. The remaining balance after n payments is: B = P × [(1 + r)^n (1 + r)^k] / [(1 + r)^n 1]
Get the Full Details
Where P is the original principal, r is the monthly interest rate, n is the total number of scheduled payments, and k is the number of payments remaining. When you add an overpayment each month, you're essentially reducing P every period, which compounds downward. The savings aren't linear, which is why an amortization schedule is necessary rather than a simple multiplication. For a quick manual check without a spreadsheet, you can estimate the impact by recognizing that each £1,000 of extra principal paid early in the term saves roughly £300 to £600 in total interest over a typical 25-year mortgage at current rates, depending on the exact rate and whether it reduces the term or the payment. That's a rough rule of thumb, not a precise figure, but it's useful for sanity-checking what a calculator is telling you.
Common Pitfalls
One thing people consistently overlook is the overpayment limit. Most UK lenders cap voluntary overpayments at 10% of the outstanding balance per year without penalty. If you overpay beyond that, you'll hit an Early Repayment Charge, which can easily wipe out any interest savings you gained. On a £200,000 mortgage, that means the first £20,000 in extra payments over a rolling 12-month period is usually fine, but anything above that gets expensive fast. ERCs are typically 1% to 5% of the amount that exceeds the limit, and they apply to the portion over 10%, not the whole balance. Another issue is that some lenders don't process overpayments immediately. There can be a lag of several weeks between when you instruct the payment and when it actually reduces your balance. During that lag, you're still paying interest on the higher amount. If you're making regular overpayments, this lag accumulates, and the actual savings will be slightly less than the calculator predicts. I've seen discrepancies of £200 to £400 on a five-year overpayment plan because of this. Fixed-rate mortgages also complicate things. If you're on a two-year fix and you overpay significantly during that period, you might think you're set for the reversion rate. But when the fix ends, your lender may recalculate your payment based on the remaining term and the new rate, which could end up being higher than you expected if the term has shortened considerably. Check what happens at rate transition before you overcommit.
When a Calculator Falls Short
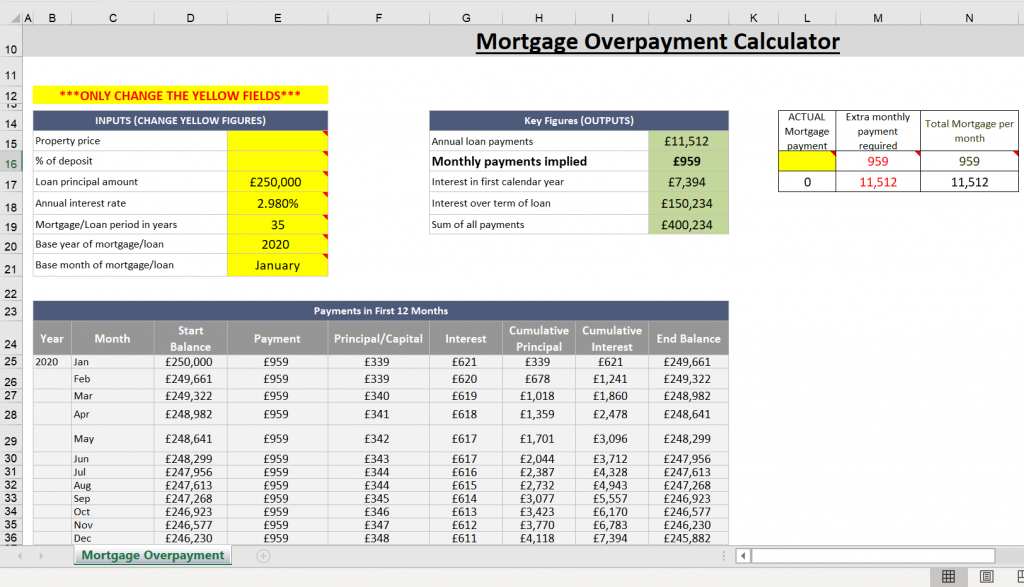
Online tools are fine for a ballpark figure. They're not fine for making decisions. The core problem is that they use generic assumptions about your lender's policy, their fee structure, their overpayment caps, and their early repayment charges. None of that is baked into the average free calculator, so the output is always a best-case scenario that doesn't match your actual contract. If you want accuracy, the workaround is straightforward. Take the first output from the calculator and then build a month-by-month spreadsheet. Columns should include: month number, opening balance, interest charged that month (opening balance × daily rate × days in month), your regular payment, your overpayment, total principal reduction, and closing balance. Repeat for 60 to 120 months and compare the total interest paid against your original schedule. This takes about 20 minutes and gives you a result accurate to within a few pounds, assuming your lender applies overpayments correctly. There's also the edge case of repayment versus interest-only mortgages. An overpayment calculator for a repayment mortgage is one thing. For an interest-only mortgage, overpayments go toward a separate repayment vehicle or directly reduce the principal, and the math is completely different. Most free calculators don't handle this distinction at all. If you're on interest-only, you need a calculator specifically designed for that product type, or you need to model it yourself.
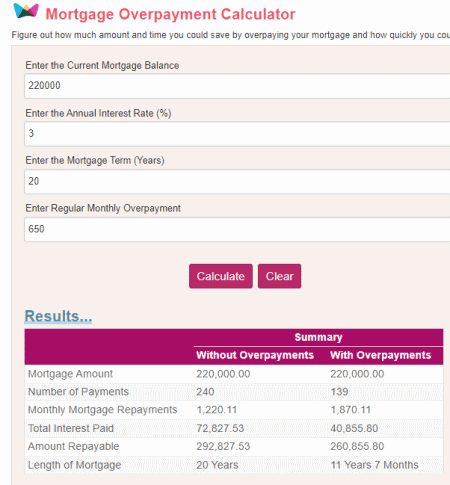
The biggest blind spot I've encountered is what happens with tracker mortgages when the base rate changes. A Mortgage Overpayment Calculator will show you a static plan, but if the Bank of England raises rates, your monthly interest charge goes up even though your principal is shrinking. The overpayment stops being as effective as it looked on paper. I had a client in 2022 who had aggressively overpaid on a 2% tracker and then watched the rate jump to 5%. His overpayment plan suddenly looked inadequate because the higher rate meant more of each payment went to interest and less to principal. He had to adjust his strategy mid-stream, which most calculators won't help you with. The bottom line is that an overpayment calculator is a planning tool, not a precision instrument. Use it to understand the direction and rough magnitude of the savings. Then verify the output against your actual lender terms and run a manual amortization schedule before you make any commitments. That extra effort prevents surprises and makes sure the savings you calculated are the savings you actually get.