Breaking Down How Mortgage Payment Actually Works
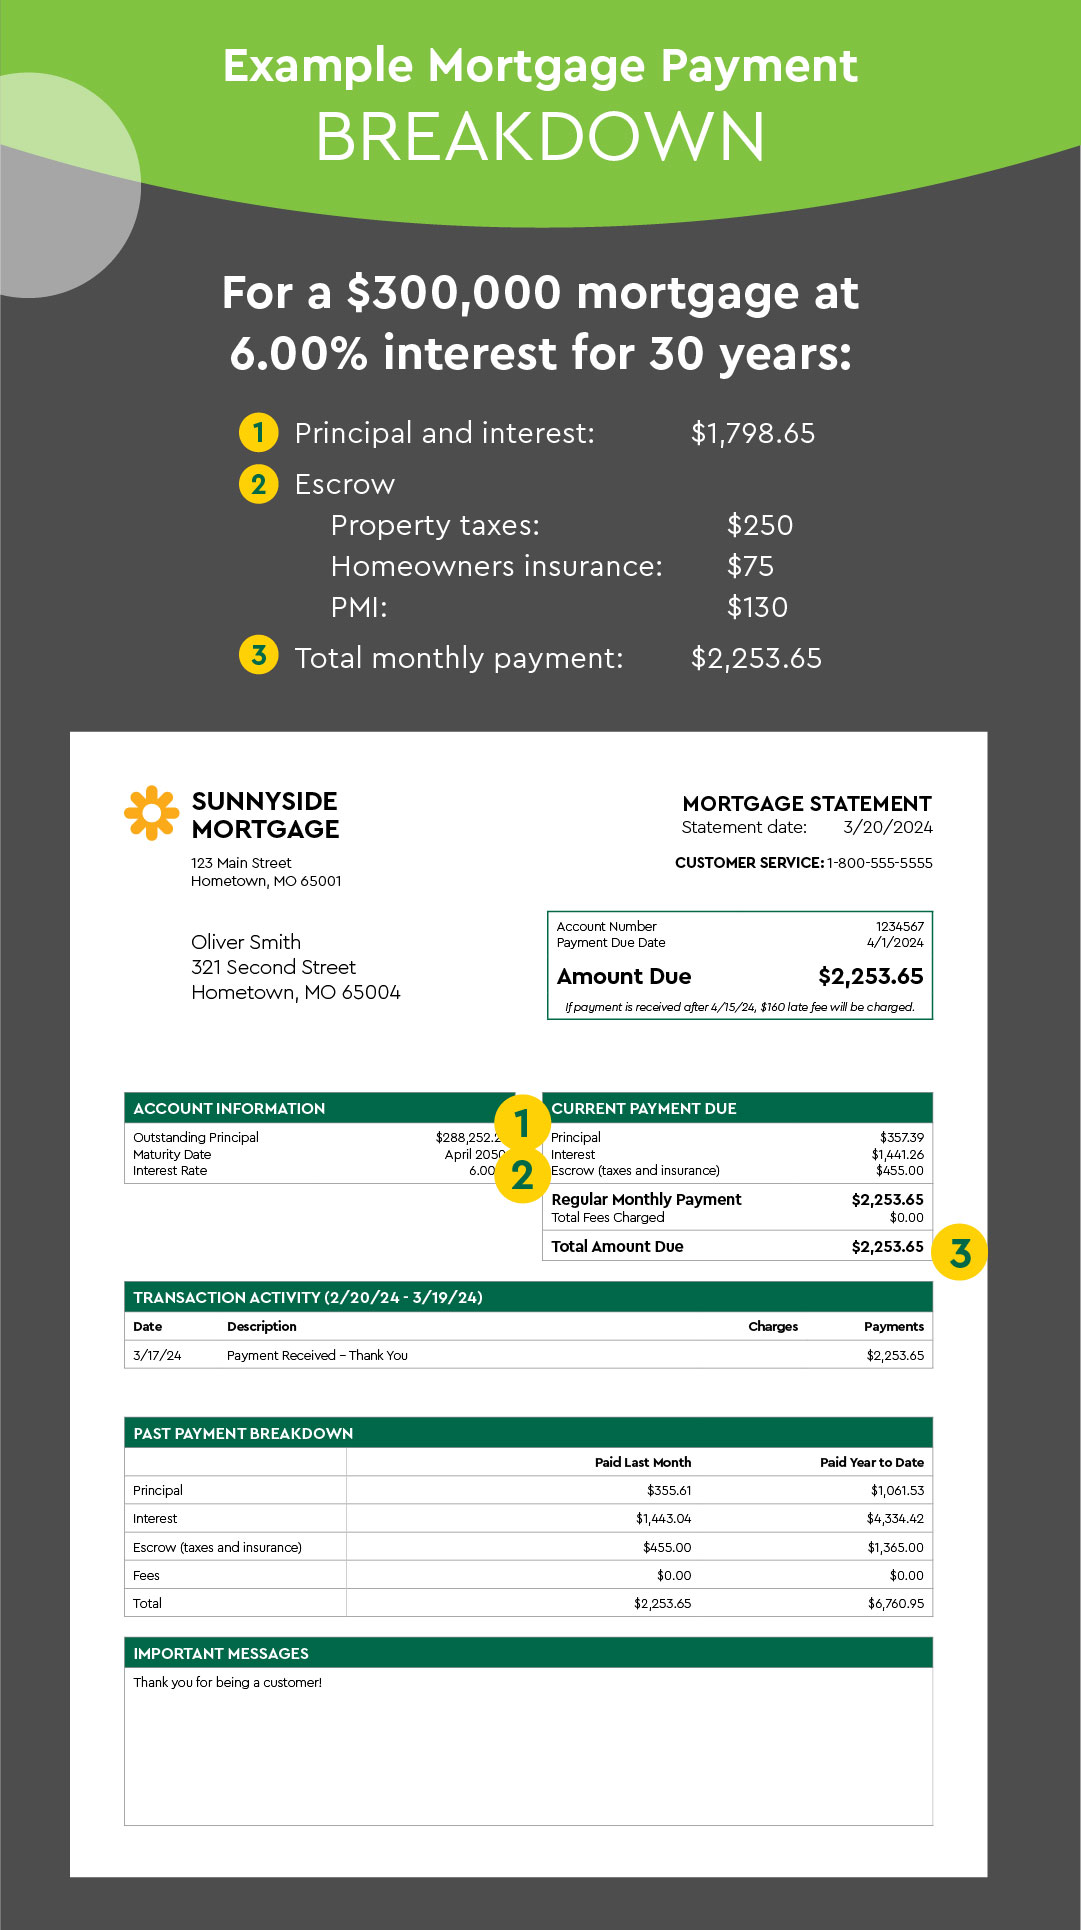
The monthly amount you send to your lender isn't just principal and interest. It includes escrow for taxes and insurance bundled into one payment. Lenders require this because they need to protect their collateral, and if property taxes go unpaid, the county can place a lien on a house they financed. The formula itself is straightforward. Take your loan amount, divide the annual interest rate by twelve to get the monthly rate, multiply that by the total number of payments, then divide the loan amount by that result minus one, and finally multiply the monthly rate by the numerator. That gives you the principal and interest portion. Add your estimated monthly tax and insurance, and you have the full figure. I have run this calculation dozens of times for clients who received statements that didn't match their expectations. One thing people consistently miss is how much the early years of a mortgage eat into equity. With a standard 30-year loan at current rates, you will pay more in interest than principal for roughly the first eight to ten years. I had a client in 2023 who refinanced without realizing they were only three years into a new 30-year term. Their balance barely moved from the initial amount. They ended up resetting the clock unnecessarily and paying tens of thousands more over the life of the loan. They should have made additional principal payments instead of refinancing.
How to Calculate Your Monthly Mortgage Payment by Hand
Start with the loan amount. For a $350,000 loan at 6.5% annual interest over 30 years, the monthly rate is 0.005417, which is 0.065 divided by twelve. The total number of payments is 360. You plug those into the amortization formula. The principal and interest comes to approximately $2,212 per month. Then add escrow. If your annual property taxes are $4,200 and your homeowners insurance is $1,800, that adds $517 to the monthly bill. The total monthly Mortgage Payment is about $2,729. Lenders use slightly different rounding methods, so your actual statement might vary by a few dollars. There is a common misconception that making extra payments toward principal does not matter because interest is calculated upfront. That is not true. Interest is recalculated monthly based on your remaining balance. If you send an additional $200 each month and designate it as principal-only, your balance drops faster, your interest charge shrinks the following month, and you save money across the entire life of the loan. I recommend sending a separate check or using your lender's online portal to mark the extra amount specifically as principal. Some servicers will apply unexpected overpayments to future escrow instead, which defeats the purpose. The escrow portion deserves more scrutiny than most borrowers give it. Your lender is supposed to hold a cushion of up to two months of escrow payments, but they also perform an annual escrow analysis. If your property taxes increase significantly, like they do in jurisdictions reassessing after a market boom, your monthly payment can jump unexpectedly. A homeowner I worked with in 2024 saw his escrow shortage hit $1,400 after his county reassessed his property. His lender amortized that shortfall over twelve months, adding nearly $120 to his monthly payment for the rest of the year. He should have called the county assessor first and checked his reassessment appeal options before accepting the higher estimate from his lender.
Ways to Reduce Your Total Payment
The most direct route is a lower interest rate. A half-point reduction on a $350,000 loan over thirty years saves roughly $220 per month and about $80,000 in total interest. Points cost money upfront though. Buying down the rate at closing makes sense if you plan to stay in the home long enough to recoup the cost. At a typical buydown price of one percent of the loan amount, you need to stay roughly seven years for the monthly savings to offset the initial fee. If you move sooner, you lose money on the transaction. Shorter terms work the other direction. Switching from a 30-year to a 15-year loan at the same rate increases your monthly payment but cuts total interest dramatically. A $350,000 loan at 6.5% over fifteen years comes to about $3,062 per month in principal and interest, which is higher than the 30-year figure but saves roughly $95,000 in interest over the life of the loan. The tradeoff is real. That higher monthly obligation leaves less room for other expenses or emergencies. Biweekly payments are another option that some lenders advertise aggressively. Instead of twelve payments per year, you make twenty-six half-payments. This effectively adds one extra full payment annually. The mathematics check out, and you will pay off the loan faster while reducing total interest. The problem is that not all servicers handle biweekly processing cleanly. A few still apply payments on a calendar basis rather than tracking them against the principal reduction schedule, which can create confusion during payoff statements. If you go this route, verify with your lender exactly how the payments are applied before committing.
Get the Full Details

When Your Mortgage Payment Is Wrong
Statements occasionally contain errors. I have seen lenders miscalculate escrow by including fees that should not be part of the insurance line item, such as flood zone surcharges or windstorm deductibles listed separately. Another common mistake is a typo in the interest rate used to compute the principal and interest portion, usually off by a single decimal place. If your payment does not match the figure from your closing documents, request a full amortization schedule from your servicer. They are required to provide it within thirty days of a written request under regulation X. Compare the opening balance, the interest rate, and the payment amount line by line. Servicers sometimes misapply payments too. If you made a voluntary principal-only contribution and your statement shows it went to escrow or future installments, call the servicer immediately. Document the call with the representative's name, date, and reference number. Keep copies of your payment confirmations and the statement in question. Escalation through the lender's complaint department works faster than waiting for the next billing cycle, especially when the error affects your principal balance and ongoing interest calculations.
Tools That Handle the Math for You
Spreadsheets remain the most reliable option for modeling different scenarios. Build a simple table with columns for payment number, beginning balance, monthly interest, principal portion, ending balance, and cumulative interest paid. The interest column uses the formula of beginning balance multiplied by the monthly rate. The principal column is your total payment minus the interest. Drag the formulas down three hundred sixty rows and you can see exactly how the split shifts over time. I typically add a column for extra principal payments to show how additional contributions change the payoff timeline. This approach takes about twenty minutes to set up and works better than most online calculators because you control every variable. Online mortgage calculators are fine for quick estimates but they often hide assumptions. Some include property tax and insurance based on national averages rather than your actual figures. Others do not account for escrow shortages or annual adjustments. If you need accuracy, enter your exact numbers manually. For a more complete picture, pull your closing disclosure and use those exact figures instead of round estimates. The difference between an estimated payment and your actual payment can be significant enough to affect your budgeting, especially when taxes and insurance climb. The bottom line is that a Mortgage Payment is a combination of several components that change over time. The principal and interest stay fixed on a standard loan, but taxes and insurance do not. Understanding how each piece works and where errors commonly occur saves you from overpaying or missing opportunities to reduce your balance. Keep your closing documents, track your amortization, and verify your statements annually. The effort pays for itself.