Working Backward From the Number You Can Actually Afford
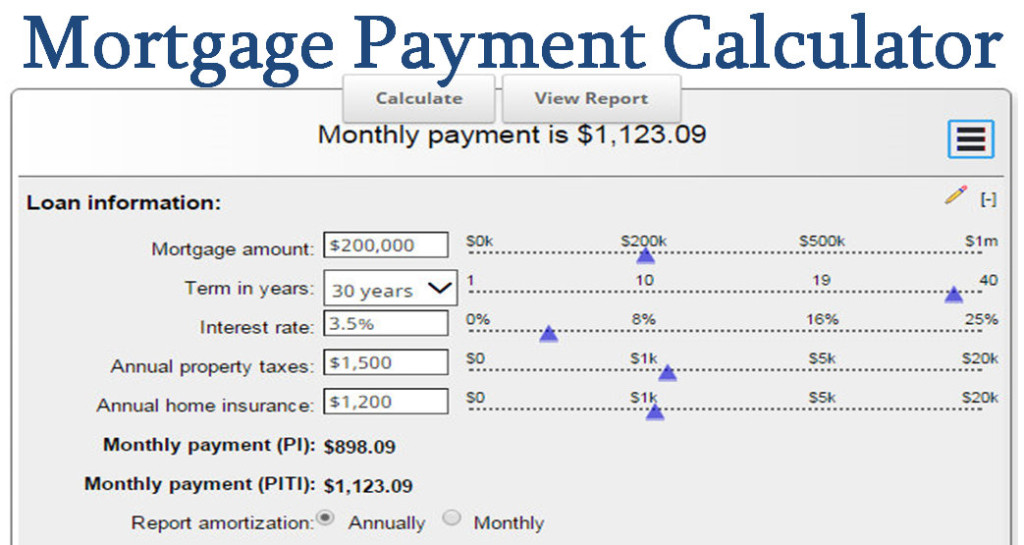
Most mortgage payment calculators ask you to plug in a loan amount, interest rate, and term, then spit out a monthly figure. That direction works fine for estimation. The reverse calculation—taking the number you think you can manage each month and finding the loan it supports—is genuinely more useful when you are trying to figure out whether a house price is even in your range before you go hunting. I keep a spreadsheet with this logic because the one-shot web calculators rarely let you solve for principal or property value cleanly.Mortgage Payment Calculator By Monthly Payment
The core equation most people never see is the annuity formula rearranged to isolate principal. If your target payment is P and your monthly rate is r over n periods, the borrowable principal equals P multiplied by (1 minus 1 divided by (1 plus r) to the n), all divided by r. It looks dense until you put it into a single cell with a Goal Seek or Solver behind it, then you can flip between payment targets and purchase prices without re-deriving anything. I used to do this by hand with a financial calculator during the height of the last rate spike, when payments swung enough that listing prices meant nothing without knowing the actual housing expense. A common pitfall is forgetting that lenders do not calculate payment from just interest and principal. Property taxes, homeowners insurance, and HOA fees usually get wrapped into the PITI number they use for qualification, which means the amount available for debt service shrinks the moment you add those line items back in. In practice, that difference can swallow forty to eighty dollars a month depending on where the property sits and what the tax rate looks like.
What You Need Before You Start
Grab a current rate for the loan product you are actually targeting. Investor rates, owner-occupant rates, and jumbo rates diverge enough that using a generic index number introduces real error. Note the loan term, the points you plan to pay if any, and whether you are looking at a fixed rate or an adjustable one. If it is an ARM, you need the initial fixed period, the adjustment caps, and the margin, because the payment shock later in the term changes the affordability picture entirely. Then list the recurring costs tied to the home. Property tax rate by jurisdiction, annual insurance premium, and any mandatory HOA dues. These are not optional additions, they are structural. Skipping them makes your maximum purchase price look artificially high and leads to the classic situation where you get pre-approved for a number you cannot actually carry once closing happens.
The Actual Mechanics
Build a base model with five inputs: target monthly payment, annual interest rate, loan term in years, property tax rate, and insurance plus HOA annual cost. From there, subtract the non-debt portion of the payment first. Multiply the assessed value by the tax rate, divide by twelve, add the insurance and HOA monthly equivalents, and subtract that total from your target payment. What remains is pure principal and interest. Feed that remainder into the annuity formula to recover the loan amount you can support. Loan amount divided by down payment percentage gives you gross purchase price, then you add estimated closing costs to get the full cash required. That final number is what actually matters for filtering listings. I learned to track it separately because a calculator that only returns loan size leaves you guessing about whether the down payment and closing costs are realistic for your cash reserves. If you want this to adjust dynamically rather than manually recalculating, set up a simple iterative solve. Put a placeholder for purchase price, derive the loan amount from that price minus your down payment, compute the expected PITI, and then run Goal Seek to make the computed payment equal your target. One solver call does the whole loop. In my experience this replaces about an hour of manual tinkering with roughly five minutes once the template is built, assuming you already have the rate and tax data sitting in front of you.
Get the Full Details
A Real Edge Case I Hit Recently
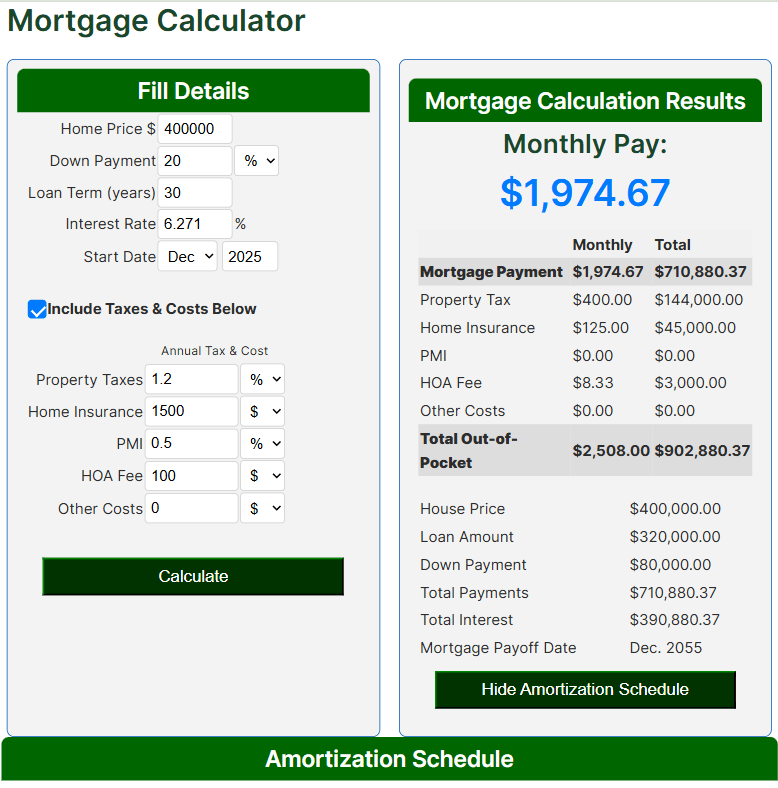
Last year I was working with a client who had a hard ceiling of two thousand three hundred dollars per month for total housing cost, and the calculator kept spitting out purchase prices that felt too aggressive for the local market. The issue was mortgage insurance. Because the target came in under twenty percent equity on most search results, PMI was eating roughly one hundred and twenty dollars a month on top of everything else. The model treated PMI as a fixed add-on, but the premium itself scales with loan-to-value and credit tier, so the initial output was off by about four thousand dollars in purchasing power. The fix was to add a conditional layer. If the loan-to-value ratio exceeds eighty percent, pull an annual PMI rate based on the LTV band and credit profile, convert that to a monthly charge, and include it in the PITI sum before running the reverse solve. Once I did that, the affordable price range dropped to a zone that actually matched inventory. It is a small adjustment, but it is the kind of thing that separates a calculator from a usable planning tool.
Where This Breaks Down
The reverse calculation assumes the payment stays level, which is false the moment you introduce an ARM or an interest-only period. With an ARM, the initial payment is misleading because the fully indexed rate often lands significantly higher, and the payment can jump at each adjustment. If you only back-solve on the teaser rate, you will overstate what the loan can support by the time the rate resets. A practical workaround is to run the reverse solve twice: once on the initial rate and once on the cap-locked fully indexed rate, then take the lower purchase price as your real ceiling. Another limitation is tax deductibility. Mortgage interest and property tax deductions shift depending on whether you itemize, which changes effective affordability for some buyers but not others. Most calculators ignore this because the variable makes the model messy. If you need precision there, you should layer in a tax scenario or consult a preparer, but for quick filtering, treating the payment as gross is usually sufficient. Then there is the problem of seller concessions and lender credits. A calculator will happily output a maximum loan amount, but if you are relying on a closing cost credit to keep the payment down, that credit is temporary and capped. Once you remove it, the payment climbs. I always run a second pass without concessions to confirm the payment still fits the budget, because relying on credits to hit a payment target is a common way to get surprised at closing.
How I Use This Day to Day
I build a single workbook with three sheets. The first holds current market data: rate, terms, tax ranges by county, and insurance estimates. The second is the reverse calculator where I enter payment targets and instantly get purchase price, loan amount, and cash needed. The third tracks scenarios side by side so I can compare fixed thirty-year, fifteen-year, and various ARM structures against the same payment ceiling. The workbook takes about ten minutes to load with live data and then runs the reverse solve in seconds per iteration. When I am helping someone narrow a search, I feed in their real numbers: the payment they are comfortable with, the local tax rate, their intended down payment, and the loan product they qualify for. The output tells them which neighborhoods and price bands actually match, instead of wasting time on listings where the PITI clearly exceeds their limit. That alone cuts the browsing phase dramatically, usually from several hours of scrolling to under thirty minutes of targeted lookups. If you do not want to maintain your own spreadsheet, there are online calculators that allow payment-to-price solving, but most of them stop at principal and interest unless you upgrade to a paid version or manually add tax and insurance. Free tools tend to favor the forward direction because that is what most lenders publish. The tradeoff is speed versus accuracy, and the gap widens quickly once you move into markets with volatile tax rates or high HOA fees.

The honest takeaway is that working backward from monthly payment is straightforward mathematically but messy in practice because the assumptions around taxes, insurance, PMI, and rate type stack up fast. Build a model that forces you to specify those inputs rather than leaving them blank, run at least two scenarios for adjustable products, and check the result against actual listings in the target area. The formula does the heavy lifting, but the input quality determines whether the answer is useful or just impressive.