Building a Mortgage Calculator That Actually Handles Extra Payments
Most people try to use the PMT function and call it a day. It works for a basic monthly payment, but the moment you want to model extra payments—whether that's $200 a month toward principal or a random $5,000 chunk in year three—the standard formulas fall apart. The built-in Excel mortgage calculator doesn't support this either. You have to build something custom. Here is how I approach it, and more importantly, what goes wrong when you don't think about the amortization schedule structure first.
How a Mortgage Payment Calculator With Extra Payments Excel Works Under the Hood
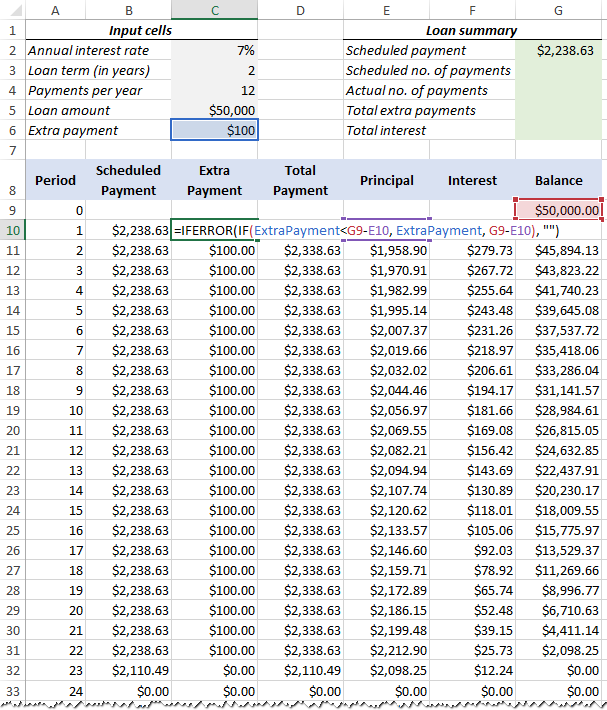
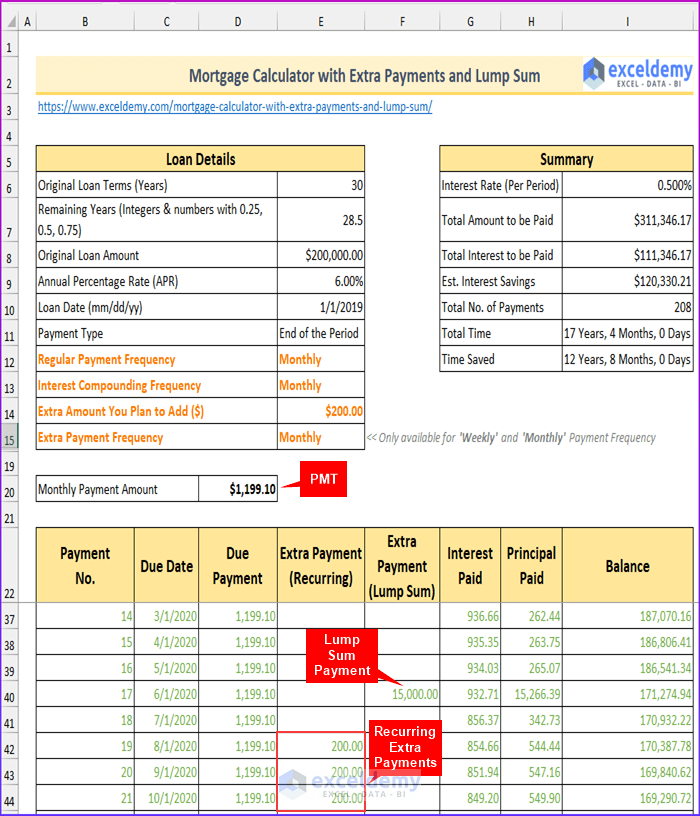
The core idea is simple but most people mess up the setup. You build a running amortization schedule where each row represents one month, and the extra payment column feeds directly into the principal reduction. The standard PMT function gives you the base payment. Everything after that requires an iterative calculation row by row. Start with these columns: Date, Beginning Balance, Total Payment, Principal Portion, Interest Portion, Extra Payment, Ending Balance. That is the entire structure you need. The interest portion is your Beginning Balance multiplied by your monthly rate (annual rate divided by 12). The principal portion is your Total Payment minus Interest. Then Ending Balance becomes Beginning Balance minus Principal minus Extra Payment. Next row's Beginning Balance is last row's Ending Balance. Repeat until the balance hits zero. The extra payment column is where this differs from a basic calculator. You can put a fixed amount in every row, or you can reference a separate cell for one-time lump sums. I usually set up an "Extra Payments" table somewhere on the sheet with dates and amounts, then use INDEX and MATCH or XLOOKUP to pull those into the schedule. This way a $10,000 payment in month 24 doesn't require you to manually edit the spreadsheet.
The Calculation Chain You Need
Your monthly payment stays constant. That is the PMT output: =PMT(rate/12, nper, -loan_amount). This never changes even when you add extras. What changes is how much of that payment goes toward principal versus interest each month, and how fast the balance shrinks when you layer in additional principal. Put the base payment in a clearly labeled cell. Then in your schedule, the Total Payment column references that cell. The Interest calculation uses the monthly rate. The principal without extras is Payment minus Interest. Add the extra payment to that principal amount. Subtract the total principal reduction from the beginning balance. That is your ending balance for the month. When the ending balance drops below the regular monthly payment amount, you have reached the payoff point. The last row needs a adjustment because the final payment will be smaller than the scheduled amount. You either cap the last principal payment at the remaining balance or let the formula naturally produce a smaller final payment. Both work. The second approach is cleaner.
Get the Full Details
What Actually Goes Wrong
I spent two days debugging a spreadsheet for a client who wanted to model biweekly payments. The schedule looked correct for the first six months, then the numbers started drifting. The issue was not the formula. It was the date column. I had been using a simple date plus 30 days increment, which creates an uneven schedule because months vary in length. Switching to EOMONTH fixed it immediately. The payment count jumped from 359 months to 360 and the interest total diverged by over $400 from the correct figure. Date handling in Excel mortgage models is one of those things nobody warns you about until you lose hours chasing a phantom error. Another common problem: people put the extra payment directly inside the PMT function or try to adjust the loan term dynamically. Neither works well. The PMT function assumes level payments over a fixed term. Extra payments change the term, they do not change the payment amount. Keep them separate. The schedule handles the term reduction automatically through the declining balance.
Key Metrics to Pull Out
Once the schedule is built, you can extract everything you need. Total interest paid is SUM of the Interest column. Total cost of the loan is principal plus total interest. The payoff date is the date in the final row. Time saved by extra payments is the difference between the original amortization end date and the actual payoff date. For a quick summary section, use COUNTBLANK on the Ending Balance column to count how many months remain, or find the last non-zero balance row with a combination of INDEX and MATCH looking for the first zero or negative value. I typically use =MATCH(0, Ending_Balance_Column, 1) to find the payoff month index, then pull the date from the corresponding row.
Mortgage Payment Calculator With Extra Payments Excel — Practical Output
A well-built version of this gives you immediate visibility into how much interest you save and how many months you shave off. Running a $350,000 loan at 6.5% over 30 years with an additional $300 per month toward principal reduces the term from 360 months to approximately 267 months and saves roughly $78,000 in interest. A single $10,000 lump sum payment in the first year cuts about 14 months off the term and saves around $9,200 in interest. These are realistic numbers, not rounded promotional figures. The Excel file itself should be structured so a user only needs to change three inputs: loan amount, annual interest rate, and loan term in years. Everything else flows from those. Keep the input cells visually separated from the schedule. Label them clearly. If someone opens the file six months later, they should not have to guess which cell is which.
LIMITATIONS You Should Know About
This approach assumes a fixed-rate mortgage. If you are dealing with an adjustable-rate mortgage, the model breaks down because the rate changes at set intervals and the payment recalculates. You would need to rebuild the schedule with rate adjustment points and recalculate the payment at each reset. It is possible but significantly more complex and usually not worth the effort unless you are modeling ARMs professionally. Another limitation: Excel recalculates on every change, and large amortization schedules with thousands of rows can slow things down noticeably. If you are modeling a 30-year loan with biweekly payments, you are looking at 720 rows. That is manageable. Push it much further and you will feel the lag. For most residential mortgages, a 360-row schedule is more than sufficient. Also, this calculator does not account for property taxes, homeowners insurance, or PMI. Those are separate line items that some lenders escrow. If you need those included, add columns for tax and insurance and sum them with the principal and interest payment. But that moves the model into a total monthly housing cost calculator, which is a different tool entirely.
Setting Up the Final Sheet
Start with a clean input section at the top. Loan Amount, Annual Rate, Term in Years, Monthly Extra Payment, and an optional section for lump-sum payments with dates. Below that, build the amortization table. Format the currency columns with dollar signs and two decimal places. Use conditional formatting to highlight the payoff row so it stands out. Freeze the top rows so the headers stay visible when you scroll through 300-plus months of data. Add a summary block near the top or on a separate tab that shows total interest, total principal, total paid, payoff date, and months saved compared to the baseline scenario. This is what users actually care about. They do not need to see every single row to make a decision. The summary tells the story. The schedule backs it up if they want to dig deeper. The whole thing should take about 20 to 30 minutes to build from scratch if you already know the structure. First time, maybe an hour. After you have done it a few times, you can spin one up in ten minutes because the logic is identical every time. The only variable is the input assumptions, and those are just cell references.