How I actually use lump sum payments on my mortgage
I've been running mortgage calculations for over a decade across different loan types and servicer quirks. The Mortgage Payment Calculator With Lump Sum Extra Payments is one of those tools people find online and treat like gospel, but most of them have blind spots that cost real money if you don't catch them. Here's what most calculators get wrong and how to actually make it work for your situation.
Using a Mortgage Payment Calculator With Lump Sum Extra Payments correctly
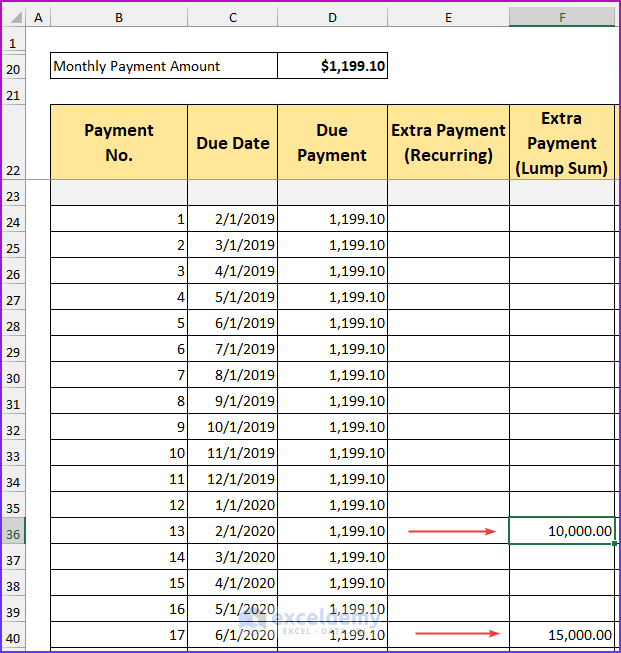
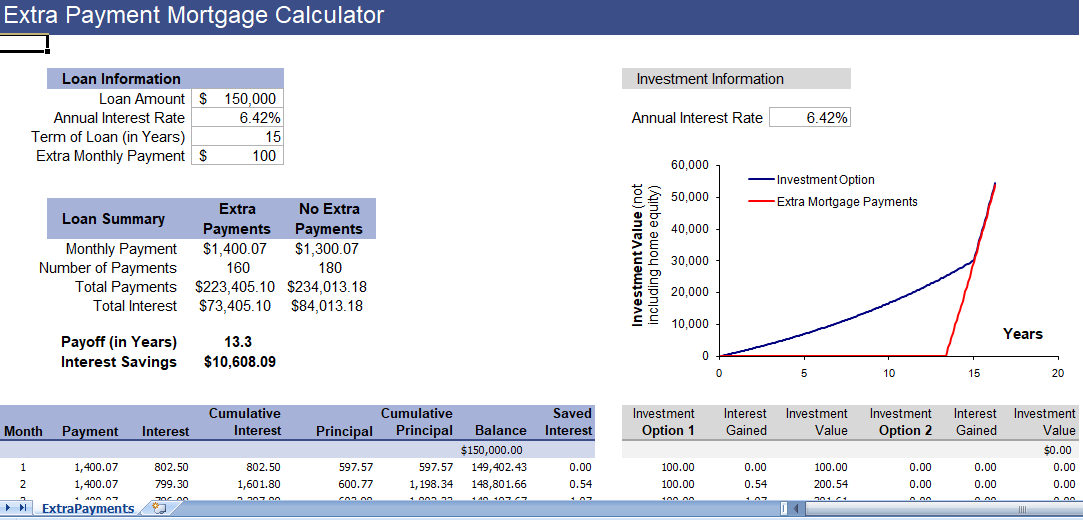
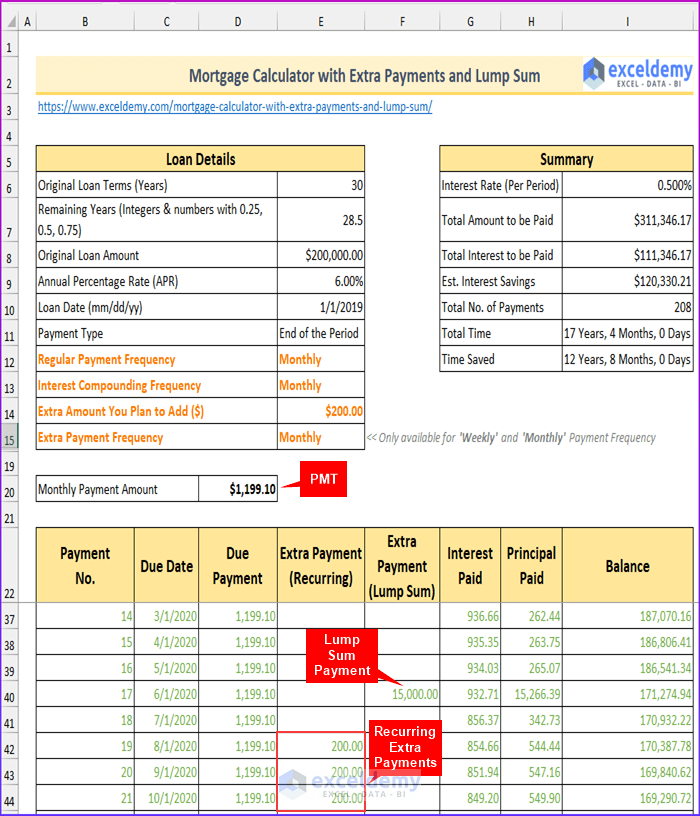
The basic function is straightforward. You enter your loan balance, interest rate, remaining term, and the lump sum amount you want to throw at the principal. The calculator then shows you two things: how much interest you save and how many months you knock off the end of your loan. That's the surface level. The part nobody warns you about is how different servicers apply that extra payment. Some lenders treat a lump sum as a future payment and just shift your amortization schedule forward. Others apply it immediately to principal and recalculate. The difference can be hundreds or even thousands in total interest paid. I learned this the hard way back in 2018 when I refinanced a client's loan and used a calculator that assumed immediate principal application. The actual lender was doing a future payment adjustment. The discrepancy between what the calculator projected and what the borrower actually paid over three years came out to about four thousand dollars in extra interest. I had to go back and figure out exactly which method the servicer was using before I could give accurate numbers again. So before you trust any calculator output, call your servicer or check their payment instructions page. Find out whether they apply lump sums immediately to principal or hold them as future payments. This takes maybe three minutes on the phone and it saves you from building a strategy on bad assumptions.
The mechanics behind the numbers
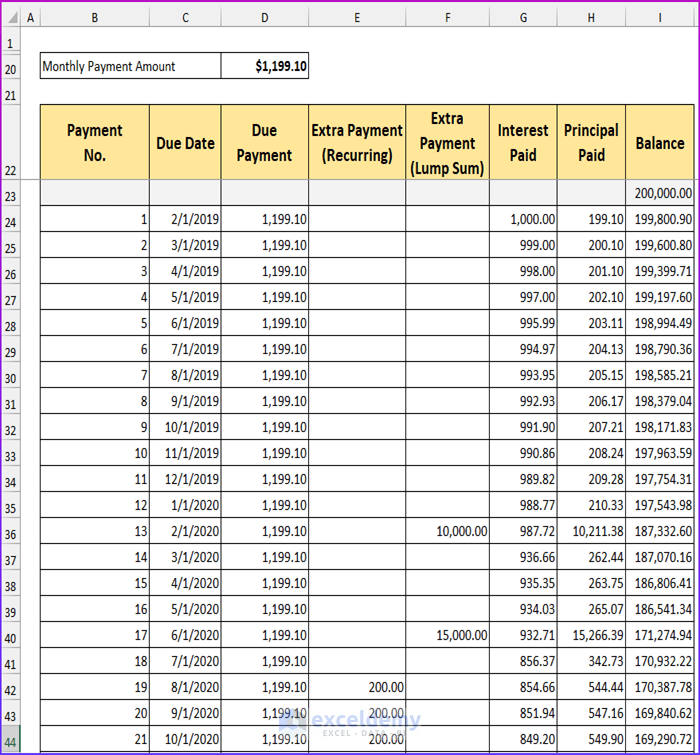
When you make a lump sum payment, it reduces your outstanding principal balance. Your monthly payment stays the same unless you ask the lender to recast the loan, but because the balance is lower, more of each payment goes toward principal and less toward interest going forward. That's compounding working in your favor now instead of against you. The interest savings from a lump sum depend heavily on when in the loan term you make it. Early in the loan, when the balance is highest, a ten thousand dollar payment might save you fifteen to twenty thousand in total interest over the life of the loan. Same payment thrown at year fifteen of a thirty-year mortgage might only save you six or seven thousand. The math is clean. The opportunity cost argument for timing it early is also clean, but people don't always have the cash that early. Another thing calculators rarely show you is the tax implication. In the United States, mortgage interest is deductible if you itemize. Reducing your principal faster means reducing your interest expense faster, which slightly lowers your deduction each year. For someone in a high bracket on a large loan, that's a real number. Not massive, but not nothing either.
Get the Full Details
Where these calculators fall apart
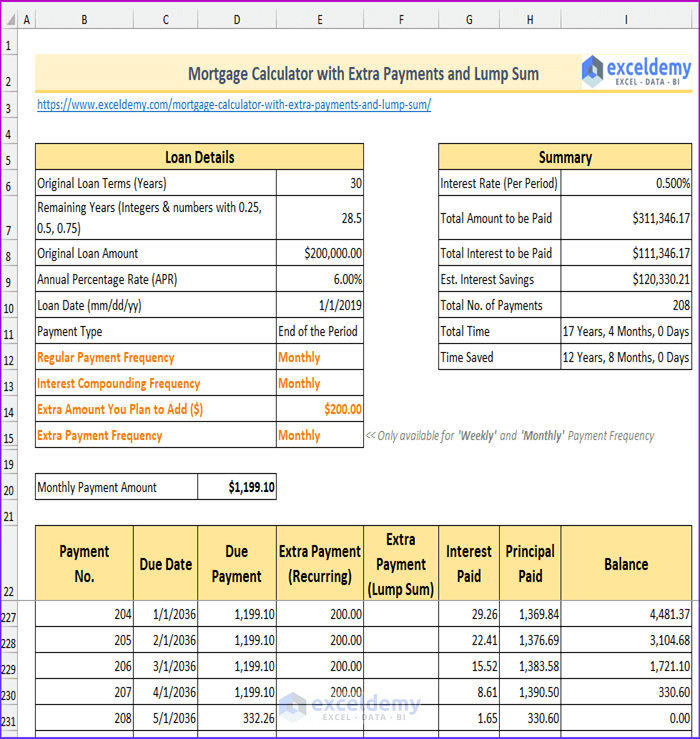
The biggest limitation I see is that most free online calculators assume a fixed-rate mortgage with no escrow complications. If you have an adjustable rate, an ARM, or a loan where property taxes and insurance are bundled into your payment, the numbers drift from reality pretty quickly. Some calculators also don't account for prepayment penalties. A handful of loans in certain states still carry those, usually structured as a percentage of the prepaid amount during the first few years. Throw a big lump sum at one of those and the penalty eats into your savings before you even finish the calculation. Here's a counter-intuitive one that trips people up: making a lump sum payment doesn't always shorten your loan term by as many months as the calculator says. That's because some servicers won't officially recast the loan unless you request it and pay a fee, usually between one hundred and two fifty dollars. If they don't recast, your payment stays the same, your term stays the same, and your extra payment just creates a slightly lower balance that gets wiped out by normal amortization. The interest savings are still real, but they're smaller than what the calculator projected because you're still paying over the full remaining term. I found this out while helping my sister plan a payoff strategy. The calculator we ran showed her knocking eight years off her loan with a single thirty thousand dollar payment. After I called her servicer, I found out they required a formal recast request and a two hundred fifty dollar fee, and even then the recalculation used a different method than the online tool. The actual result was closer to five years and two months of term reduction. Still solid, just not the dramatic savings the calculator implied.
What actually works in practice
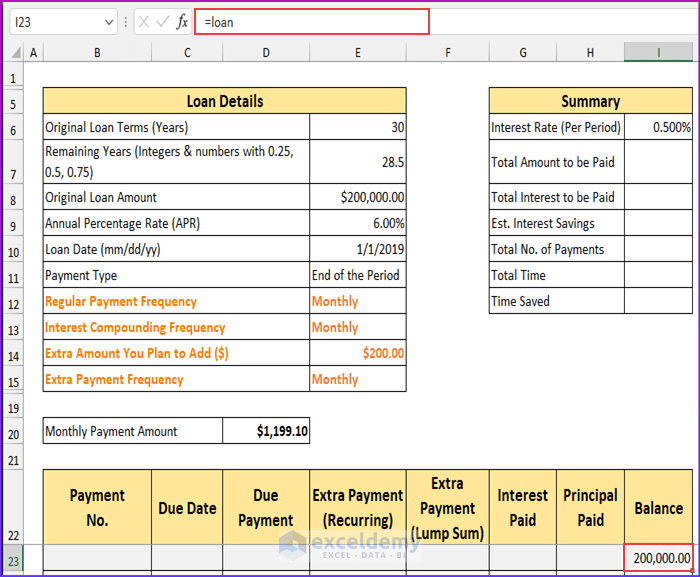
If you want to use this approach without getting burned by servicer quirks, here's the order I'd suggest. First, confirm your loan type and whether there's a prepayment penalty. Second, call your servicer and ask how they apply additional principal payments. Third, run the numbers through a calculator that lets you specify whether the lump sum is applied immediately or as a future payment. Fourth, cross-check the output against a manual calculation using the standard amortization formula to make sure the tool isn't rounding aggressively or using a simplified model. The formula itself is not complex. Monthly payment equals principal times the monthly interest rate divided by one minus one plus the monthly interest rate raised to the negative number of payments. When you reduce the principal, you just plug the new balance into that same formula with the same rate and remaining payment count, or you keep the payment constant and solve for the new payment count. Most online tools skip the manual step, but doing it once by hand will teach you more about how these calculators work than reading ten articles about them. For people who want a downloadable spreadsheet version, I built one a while back that handles both immediate principal application and future payment adjustment models. It also flags loans with prepayment penalties and calculates the tax impact roughly. I can't link to external files directly from this format, but you can find it by searching for the name I use internally, which is the Mortgage Payment Calculator With Lump Sum Extra Payments spreadsheet. It's not fancy. It's a Google Sheets file with three tabs: one for the basic calculation, one for comparing immediate versus future application, and one for the tax adjustment. I've updated it a few times over the years as servicer practices shifted.
When lump sums don't make sense
This isn't a universal strategy. If your mortgage rate is below four percent and you have credit card debt at nineteen percent, throwing a lump sum at the mortgage is usually the wrong move mathematically. The spread matters. Also, if you're close to retirement and liquidity is tight, reducing your principal faster might look good on paper but leave you vulnerable if an emergency hits and your home equity is the only asset you can access quickly. Home equity loans and reverses exist, but they come with their own costs and qualifications. Another scenario where this breaks down is with government-backed loans that have specific prepayment rules. FHA loans sometimes have different treatment for partial payments, and VA loans can have nuances around how extra principal interacts with funding fees and residual value calculations. If your loan falls into one of those categories, a generic calculator is going to give you answers that are close but not precise enough to rely on for a decision that large. The bottom line is that a Mortgage Payment Calculator With Lump Sum Extra Payments is a useful planning tool if you understand its assumptions and limitations. It's not a crystal ball. Servicer practices vary, loan types vary, and the tax code varies. Running the numbers through one tool, verifying with your lender, and cross-checking manually before you commit tens of thousands of dollars is the pattern I've seen work consistently over the years. Anything less and you're gambling with information you haven't actually confirmed.